The 2024 Year-End "Performance Report" for Lithium Carbonate Is Here!
I. Price Review
The year 2024 was marked by significant fluctuations in lithium carbonate prices. Although it was not as dramatic as the "free fall" from 500,000 yuan/mt to 100,000 yuan/mt in 2023, the prices in 2024 experienced a "roller coaster" ride due to cyclical supply-demand mismatches and occasional overseas export rush for installations. The peak price hovered around 110,000 yuan/mt, while the lowest point dropped to 72,000 yuan/mt, with an annual average price of 90,000 yuan/mt. Following the saying "after all the ups and downs, it still returns to 90,000," the annual average price in 2024 once again settled at 90,000 yuan/mt.

Phased Price Review:
January 2024-Early February 2024
In the short term, futures prices were higher than spot prices, strengthening the sentiment of some lithium chemical plants to transfer to delivery warehouses and stand firm on quotes. In late January, some cathode plants, considering the suspension of logistics during the Chinese New Year, conducted minor pre-holiday restocking, slightly boosting lithium chemical prices.
Late February 2024-Early April 2024
Environmental protection checks in Jiangxi, combined with maintenance and production cuts at leading lithium chemical plants in Sichuan, led to market expectations of a short-term supply reduction for lithium chemicals after the holiday. Additionally, the price war in the EV sector and the launch of new car models in March significantly boosted demand, driving up spot lithium chemical prices. Meanwhile, some lithium chemical enterprises stood firm on quotes and were reluctant to sell, resulting in a scarcity of low-priced goods in the spot market and a steady price increase.
Late April 2024-Late August 2024
Upstream lithium chemical supply remained at high levels, but the slowing growth in new energy end-use demand caused cathode plant production schedules to decline. Most cathode plants maintained high lithium chemical inventory levels in Q2, and long-term contracts and customer-supplied volumes recovered significantly from May to July. Spot orders were primarily just-in-time procurement, with no plans for restocking. The spot lithium carbonate trading market was relatively quiet, and prices continued to decline.
Early September 2024-Late November 2024
In September, significant production cuts at leading lithium chemical plants in Jiangxi notably impacted downstream customer supply levels. Coupled with the continued increase in downstream production schedules and widespread pre-National Day restocking, spot lithium carbonate procurement demand was significantly boosted, slowing the decline in spot prices and causing a slight rebound. From late October, driven by year-end rush for installations by end-user enterprises, both downstream material plants and upstream smelters increased production schedules. Spot lithium carbonate transactions became relatively active, slightly lifting the price center of spot lithium carbonate transactions in October and November.
Early December 2024-Late December 2024
The price rebound stimulated upstream smelters' production enthusiasm, leading to a continuous increase in domestic lithium carbonate supply. However, during the period of negotiations for 2025 long-term contract discounts, upstream lithium chemical plants maintained a strong sentiment to stand firm on quotes for both long-term contracts and spot goods. From the December transaction data, downstream material plants had already begun pre-Chinese New Year restocking. Traders, facing high inventory levels, aimed to destock and recover funds by year-end, promoting transactions with downstream material plants at relatively low price points. Market transactions were relatively active, with prices showing a slight downward trend.
II. Review of the Supply Side
1. Domestic Output
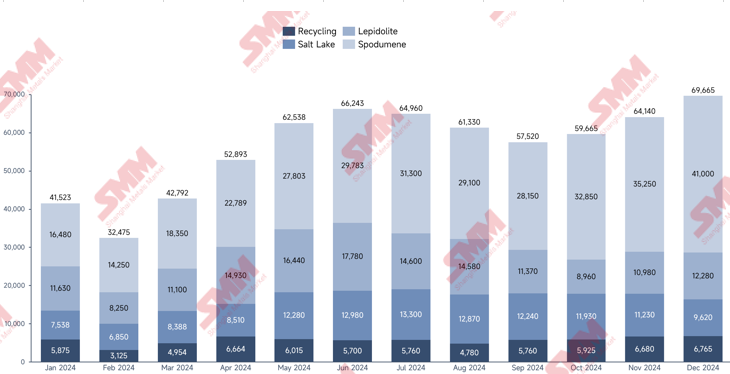
In 2024, the total domestic production of lithium carbonate is expected to reach 680,000 mt, up 47% YoY. By raw material type, spodumene accounts for nearly half, with a share of approximately 48%, up 116% YoY. This significant increase is mainly driven by the commissioning of new production lines at integrated lithium chemical plants, the relatively sluggish demand in the lithium hydroxide market, and the continued widening of the lithium carbonate-lithium hydroxide price spread, which has led some lithium hydroxide production lines to shift to supplement lithium carbonate production. On the lepidolite side, production growth slowed, up 17% YoY, due to high cost pressure and environmental protection issues, coupled with tight supply of high-grade lepidolite in Jiangxi. On the salt lake side, production increased steadily, up 37% YoY, benefiting from its cost advantages. On the recycling side, structural shortages of raw materials caused by regional mismatches in waste battery resources, combined with underutilized capacity and profit losses, resulted in a 19% YoY decline in production in 2024, with a share of only 10%.

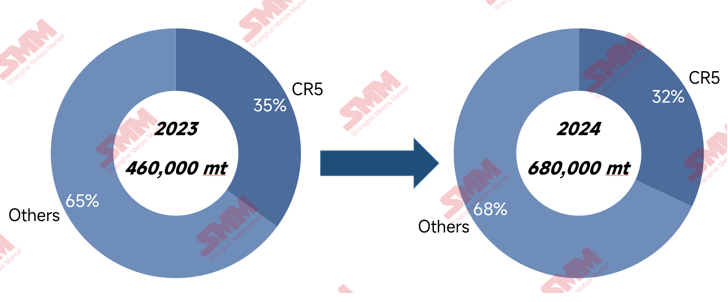
From the current changes in CR5 market share, the industry concentration of lithium carbonate enterprises remains relatively small, with numerous industry participants. With the continuous addition of new capacity, industry concentration is further declining.
According to customs data, China's lithium carbonate imports in 2024 are estimated at 230,000 mt, up 46% YoY. Chile and Argentina remain the main sources of China's lithium carbonate imports. Imports from Chile are approximately 180,000 mt, up 29% YoY, accounting for 78% of China's total imports, while imports from Argentina are about 45,000 mt, up 156% YoY, accounting for 20% of China's total imports.
Export side, China's lithium carbonate export share is relatively small, and there are still no clear signs of significant improvement in overall overseas demand at present. The production cost of lithium carbonate from overseas salt lakes is relatively more price-competitive, and China's lithium carbonate export volume in 2024 is expected to be less than 5,000 mt.
III. Demand Side Review
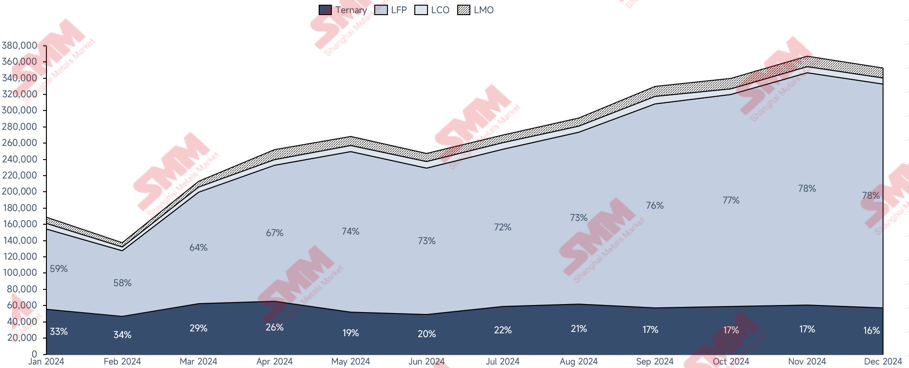
With the rapid development of the NEV sector and ESS market, China's lithium carbonate demand in 2024 is estimated at 850,000 mt LCE, up 44% YoY. By application, 67% is used for LFP cathode material production, and 12% for ternary cathode material production. Ternary cathode materials not only saw a decline in market share but also a reduction in lithium carbonate consumption. On one hand, apart from domestic NEVs favouring LFP battery cells, the ESS market has also been expanding its share due to the high safety of LFP battery cells. On the other hand, the increasing proportion of high-nickel in ternary 6-series has further reduced its lithium carbonate consumption.
On one hand, the policy uncertainty brought by the US presidential election results is expected to drive domestic battery cell enterprises to start a rush for overseas installations in Q4 2024; on the other hand, the domestic trade-in policy continues to intensify, with its cumulative effects becoming increasingly evident, while promotional activities by various regions and enterprises persistently boost enthusiasm for vehicle sales. With both domestic and overseas demand exceeding expectations, the period following the September-October peak season ushers in an even more prosperous November-December, with demand reaching its annual peak.
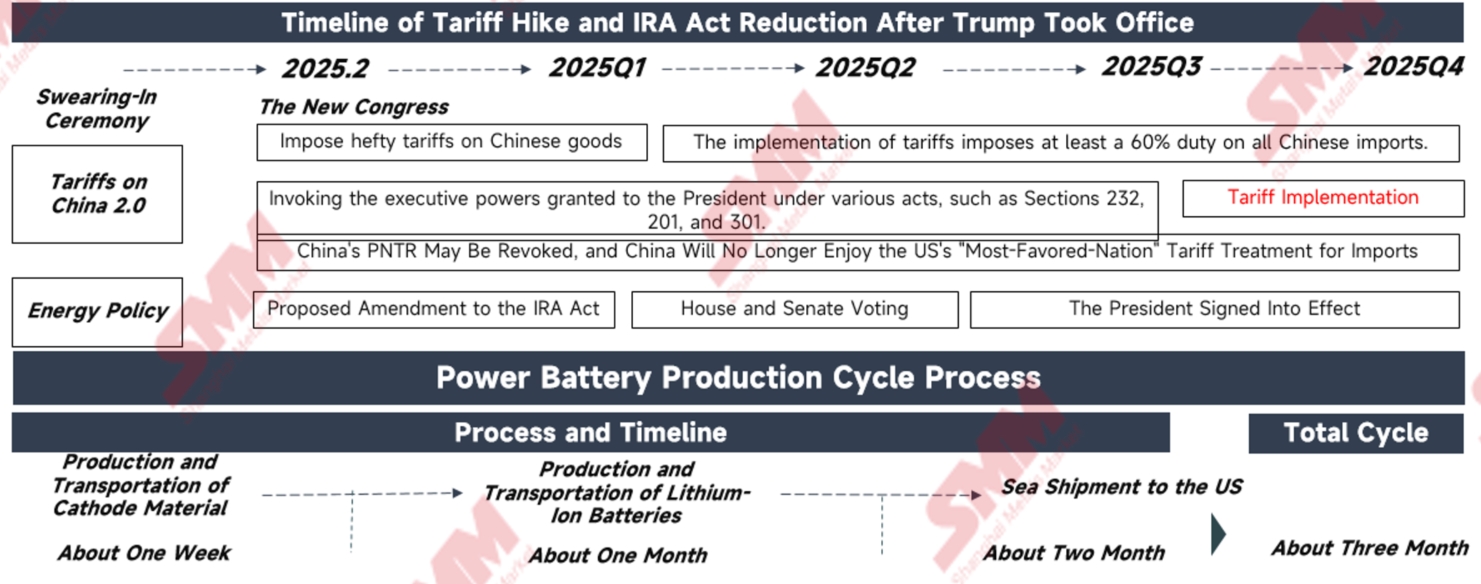
However, the rush for installations driven by the US election is merely an advance on future demand. Although the recent surge in volume has been rapid, it is expected to deplete long-term demand, and subsequent overseas export volumes may pull back.
IV. Supply-Demand Balance
In 2024, lithium carbonate is expected to continue its inventory buildup pattern, with an annual surplus of approximately 60,000 mt and cumulative inventory reaching around 110,000 mt (sample statistics). On one hand, the significant reduction in lithium carbonate supply caused by production cuts at a leading lithium chemical plant in Jiangxi in early September is notable; on the other hand, the stronger-than-expected demand has led to a destocking pattern from September-November due to the peak season effect. Overall, the supply and demand surplus pattern is expected to persist.
V. Outlook for 2025
Demand side, China remains the leading country for NEVs and ESS. NEV market, the Central Politburo held a meeting on December 9, stating that the policy environment in 2025 is expected to remain favorable, supporting the healthy development of the automotive industry. Additionally, as 2025 marks the final year of the 14th Five-Year Plan, consumer demand for vehicle replacement is expected to surge. SMM holds an optimistic outlook for vehicle sales in 2025, forecasting an annual growth rate of over 20%. ESS market, driven by policy support, China is expected to continue its strong performance in 2025, with growth also projected to exceed 20%.
Supply side, the current overall operating rate of upstream lithium chemical plants is only 50%-60%. Moreover, some new capacity is expected to come online in 2025, with domestic lithium carbonate output projected to grow by over 25%. In the future, the degree of industry integration is expected to deepen gradually. Additionally, with the continuous release of overseas lithium carbonate capacity and the relatively slower growth in overseas demand, the surplus of overseas lithium carbonate is expected to intensify, leading to more low-cost lithium carbonate flowing into the Chinese market. This will pose certain challenges to the production increase of high-cost lithium chemical plants, potentially causing reductions or even their exit from the market.
In 2025, both supply and demand for lithium carbonate are expected to grow, but supply growth is likely to outpace demand, further amplifying the annual surplus. Lithium carbonate prices are expected to face some downside room. Although current prices are already approaching the cost line of some lithium mines, the strong sentiment to stand firm on quotes among lithium miners may provide some support for lithium carbonate production costs. However, with the deepening of low-cost integration in the industry and the continuous increase in imports, the price center of domestic lithium carbonate is still expected to decline. The industry's hope for lithium carbonate prices to return to 100,000 yuan/mt may remain an optimistic aspiration.