SHANGHAI, Apr 15 (SMM) - This is a roundup of China's metals weekly inventory as of April 15.
Aluminum Ingot Social Inventory in China Declined when Compared to last Thursday
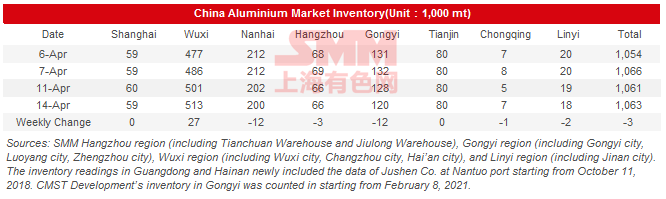
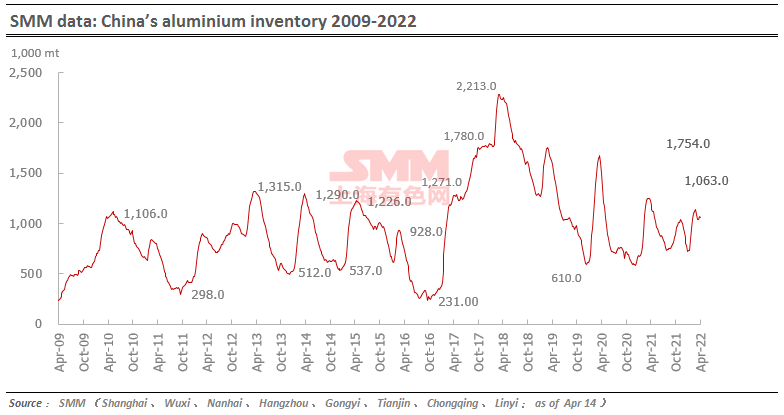
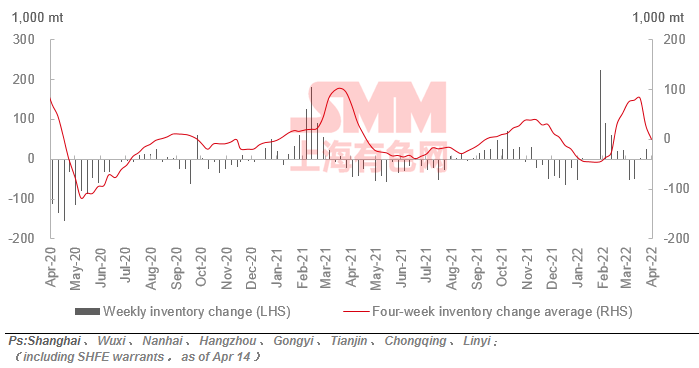
As of April 14, the aluminium ingot social inventory across China’s eight major markets totalled 1.06 million mt, down 3,000 mt from last Thursday, but up 2,000 mt from this Monday. The inventory in Wuxi increased by 27,000 mt from last Thursday as arrivals were unaffected while shipments out of warehouses were restricted by pandemic control measures. The inventory in Nanhai declined 12,000 mt as local downstream producers stocked up after aluminium prices pulled back. Spot premiums were reported in Foshan on April 14. The inventory decreased by 12,000 mt in Gongyi, where transportation and pick-up of cargoes were little affected. The efficiency of truck transportation in many areas declined sharply amid the outbreak of COVID-19. Starting from April 13, Dali Town, one of China’s top aluminium semis production areas, required that vehicle drivers shall not enter or exit unless they hold the traffic permits, which will greatly reduce transportation efficiency and increase transportation costs. China is unlikely to achieve zero COVID cases in a short period of time, hence the transportation problem will continue to interfere with the normal operation of the entire industry chain.
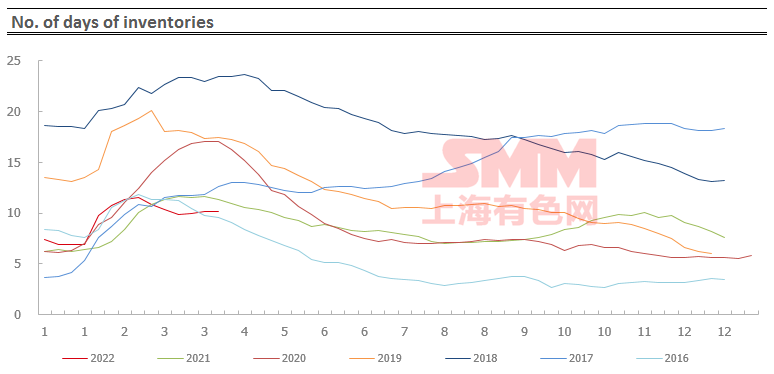
Aluminium Billet Inventory in China Declined
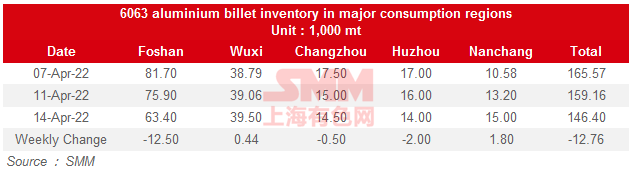
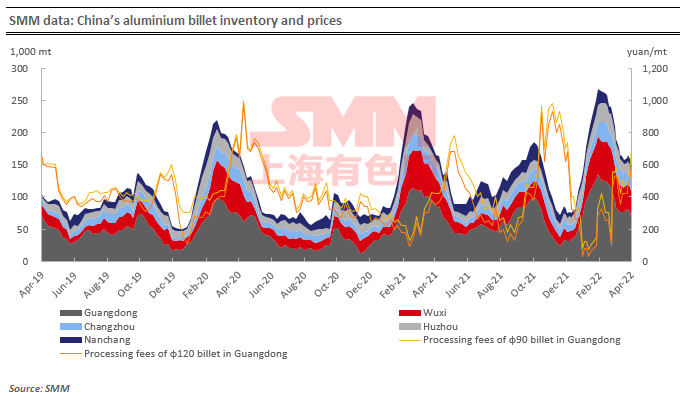
The domestic aluminium billet inventories stood at 146,400 mt as of April 14, a drop of 8.02% from a week ago. The inventory changes in the five major regions were as follows: Foshan (-12,500 mt or16.47%); Wuxi (+400 mt or 1.13%); Changzhou (-500 mt or 3.33%); Huzhou (-2,000 mt or 12.5%); Nanchang (+1,800 mt or 13.64%). The destocking in Foshan accelerated as downstream producers became more willing to restock after aluminium prices fell to a low of 20,000 yuan/mt. The inventories in east China did not change much as both inflows and outflows of cargoes were severely disrupted by the pandemic. The inventories in Nanchang continued to grow due to sluggish downstream consumption. The inventory changes in east China will still depend on how the pandemic evolves. The inventories in Foshan may continue to fall next week.
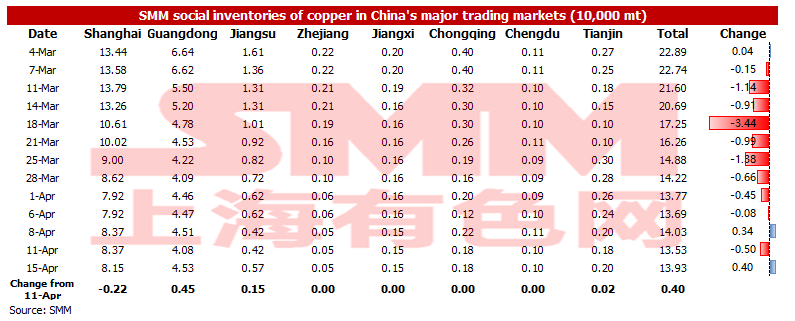
SMM China Copper Inventory across Major Market Dropped 1,000 mt on Week
As of April 15 Friday, SMM China copper inventory across major markets in China added 4,000 mt from Monday April 11 to 139,300 mt, down slightly by 1,000 mt from last Friday. The weekly inventory dropped again after a short increase last week. Compared with the domestic inventory recorded on Monday, the local stocks all added except for Shanghai during this period.
In details, the inventory in Shanghai dropped 2,200 mt to 81,500 mt from Monday April 11, added 4,500 mt to 45,300 mt in Guangdong, rose 1,500 mt to 5,700 mt in Jiangsu, and climbed 200 mt to 2,000 mt in Tianjin.
Since the Ministry of Transport issued a document in the middle of the week, the logistics blockage situation has slightly improved, especially in east China which has been greatly hit by the pandemic. According to SMM understanding since Wednesday, buyers could pick up goods at warehouses in Shanghai, but a 24-hour negative nucleic acid testing is required with other strict rules. Although buyers can pick up goods, the freight costs have skyrocketed. The normal shipping per tonne of copper from Shanghai to Changzhou and Wuxi is 70 yuan original, which has been around 300 yuan at present. Downstream manufacturers rarely take goods from Shanghai unless they are making urgent purchases. The stocks in Jiangsu and Guangdong regions are seeing an increase due to improved arrivals by railway, and more goods are shipped to social warehouses approaching the delivery of SHFE 2204 contract.
Looking forward, the social inventory is expected to fall again after the transport returns to normal, when downstream processing companies will resume their production.
SMM China Zinc Inventory across Major Market Rose 6,100 mt on Week
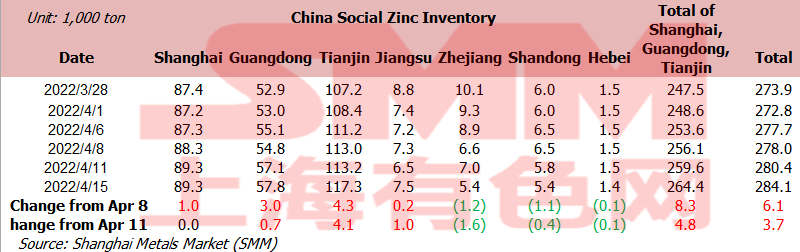
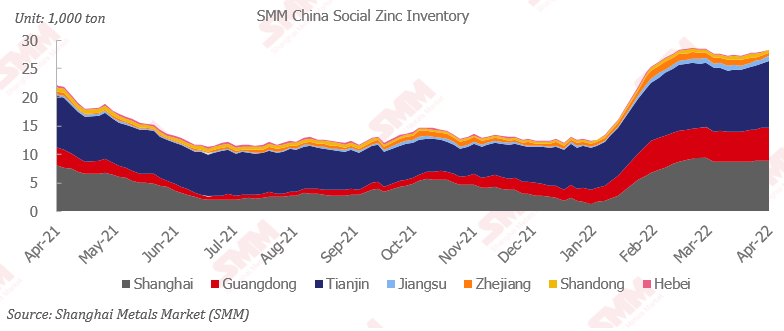
Total zinc ingots inventories across seven major markets in China stood at 284,100 mt as of April 15, up 6,100 mt from April 8, down 3,700 mt from April 11. Domestic inventories increased. In Shanghai market, due to unchanged transport restrictions, the costs of delivery increased sharply, resulting in little change in the inventory of Shanghai market. In Guangdong market, the arrivals were stable. But the recurred pandemic lowered the direct delivery of downstream, and the downstream picked up goods from the warehouses, resulting in increasing shipments. Downstream consumption has not seen an improvement with increasing inventory in Guangdong market. In Tianjin, some brands arrived amid concentrated deliveries. In the case of poor profits of enterprises in Tianjin, the operating rates were not high and the weak consumption has led to the sharp increases in Tianjin inventory. Inventories in Shanghai, Guangdong and Tianjin rose 8,300 mt, and inventories across seven Chinese markets increased 6,100 mt.
Nickel Inventory in Shanghai Bonded Zone Remains almost Unchanged this Week
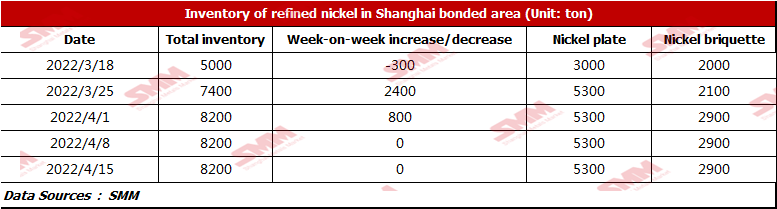
This week, LME nickel maintains a volatile trend. Although the trend of SHFE nickel prices is strong, the imports are still at losses. Nickel inventory in Shanghai bonded zone was 8,200 mt this week. The inventory of nickel briquettes and nickel plates was 2,900 mt and 5,300 mt respectively, flat from last week. Due to the COVID-19 outbreak, the operation in Shanghai bonded zone stagnates. At present, the circulation of LME nickel has not recovered. Moreover, due to weak demand, the SHFE nickel prices are under pressure. Therefore, the import will remain at losses next week.
Copper Inventories in Domestic Bonded Zone up 3,600 mt from Monday
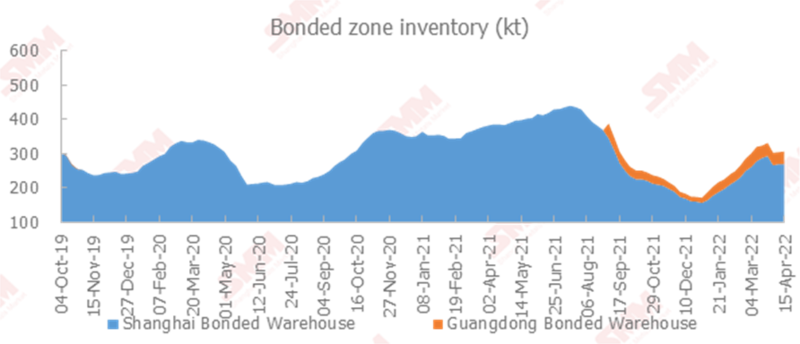
Copper inventories in the domestic bonded zone increased 3,600 mt from April 8 to 310,100 mt on April 15, according to the SMM survey. Inventory in the Shanghai bonded zone increased 3,000 mt to 272,800 mt, and inventory in the Guangdong bonded zone rose 600 mt to 37,300 mt. Although the SHFE/LME price ratio is slightly repaired this week, the imports are still at losses, and the demand for customs declaration imports is sluggish. This week, the operation in Shanghai bonded zone was restored. Truck drivers with permits can transport goods, and some goods that have already arrived at ports have been moved into the bonded warehouse. However, importers in Shanghai are still working from home, and the difficulty in flowing documents hinders the import trading, thus the circulation of imported copper will remain low.
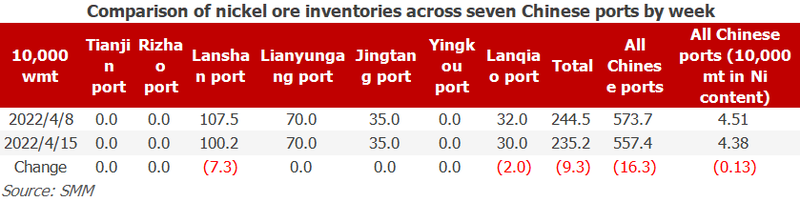
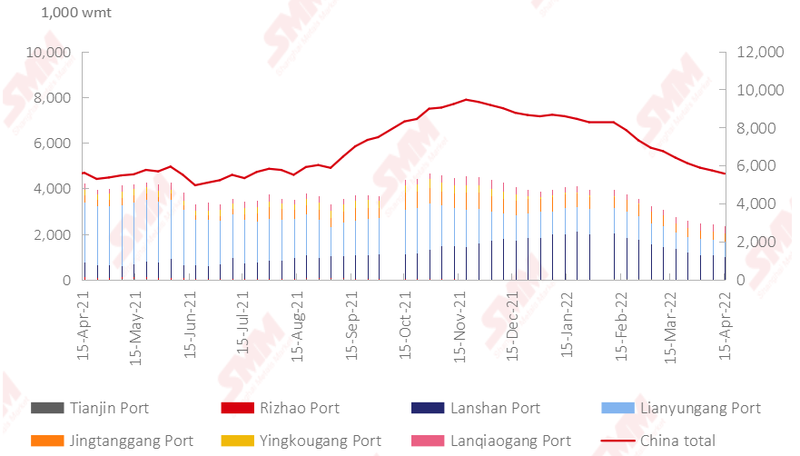
Nickel Ore Inventories at Chinese Ports fell 163,000 wmt
As of April 15, the nickel ore inventory at Chinese ports dipped 163,000 wmt from a week earlier to 5.574 million wmt. Total Ni content stood at 1,300 mt. The total inventory at seven major ports across China stood at 2.352 million wmt, 93,000 wmt lower than the previous week. The destocking speed is slowing down. The reasons are as follows. First of all, although the Philippines is at the end of the rainy season, the shipment volume is still unstable due to the poor weather condition. Moreover, in the short term, shipments from mines are unlikely to increase significantly. Secondly, the demand for nickel ore in the NPI plant is good. High NPI prices boost the production in NPI plants, which consumes a large amount of nickel ore. SMM expects that the increase in inventory will appear in May, while in the short term, the inventory will decrease slowly.
Disclaimer:
The above representation and data is based on market information SMM believes to be reliable at the time of acquiring as well as the comprehensive assessment by SMM research team, and any and all information provided in this article is for reference only. This article does not constitute a direct recommendation for investment or any decisions in any form and clients shall act on their own discreet and any decisions made by clients are not within the responsibility of SMM.