[SMM Thread] Regional differences are prominent, and spot prices fall differently after National Day.

Published: Oct 22, 2019 17:29
Recently, environmental production restrictions have not been significantly effective, supply does not reduce but rose slightly, making the market bearish sentiment shrouded in heavy inventory for a long time. According to SMM statistics, the current mainstream market thread spot price decline in 30-270 yuan / ton, of which most concentrated in the 100-200 yuan / ton decline range. Due to the great differences between regions, SMM has carried out a follow-up study of this phenomenon.

SMM10, 22nd:

Recently, environmental production restrictions have not been significantly effective, supply does not reduce but rose slightly, making the market bearish sentiment shrouded in heavy inventory for a long time.
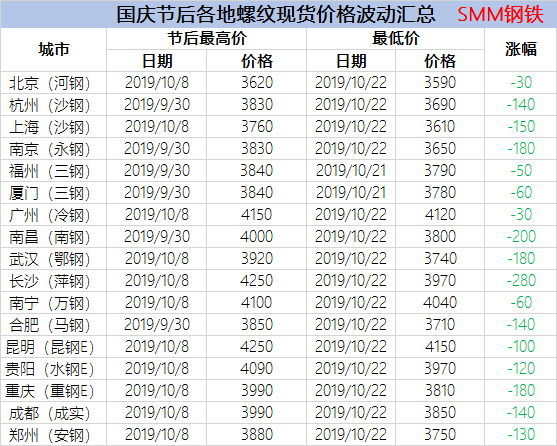
According to SMM statistics, the current mainstream market thread spot price decline in 30-270 yuan / ton, of which most concentrated in the 100-200 yuan / ton decline range. Due to the great differences between regions, SMM has carried out a follow-up study of this phenomenon.

Tons of steel fell in the area of 100-200 yuan: the mainstream area.

According to SMM research, in addition to the northeast due to the gradual cold weather, demand weakening, the current rigid demand for building materials in other regions show full toughness, good shipping condition. However, the phenomenon of large inventory pressure is more common. And at present, in addition to Beijing, Tianjin, Hebei and surrounding areas, other areas controlled by environmental protection and production restrictions in previous years (such as Jiangsu) have no policy notice, the market generally has increased expectations for supply pressure, so the operation of selling goods at low prices before the arrival of the off-season is more common.

At the same time, as pessimism still occupies the mainstream of the market, if the scope of production restriction has not been further expanded, the late spot price or weak back to the sky, continue to operate weakly.

In the range of $30 to $60 per ton of steel:

North China: Hebei, Shanxi and other Beijing-Tianjin-Hebei and surrounding areas have entered the stage of environmental protection and production restriction during the heating season, especially under the influence of pollution weather. Tangshan City, a "major town", issued two more stringent notices on the 15th and 18th of this month, and a number of traders reported that they had fewer supplies in their hands, supporting the market price to a certain extent. In addition, in Beijing, for example, inventories in September have been lower than in the same period last year. Although the recent year-on-year growth turned negative to positive, but the current local demand performance is still good, inventory pressure is not great, so the market mentality is also more rational, spot prices are more resilient.

Fujian market: steel mills have a large bargaining power for the market, with a strong willingness to raise prices, coupled with some business feedback has part of the phenomenon of relative shortage of specifications.

South China market: the demand performance is good, the Nanning market has the specification shortage situation, the spot price has the strong support. However, it is reported that the north material southward is already in the start-up, and there will be a more concentrated increment in November, when the increase in supply pressure will suppress the local spot price.

Region with a decline of more than 200 yuan per ton of steel: Hunan

Spot prices in Hunan rose rapidly in September, mainly due to on the one hand, a number of mainstream steel mills production reduction, making the market out of stock phenomenon is more common; on the other hand, the demand suppressed by torrential rain has been concentrated.

The production of mainstream steel mills resumed in October, and due to the high prices in the previous period and the small inflow of external resources, the shortage phenomenon was solved, at the same time, the demand was also stable, so the decline in spot prices after the festival was also beyond the reach of other regions.


 

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
Sep 11, 2026 18:30
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
Read More
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
On September 9, 2026, Australia initiated its second sunset review of anti-dumping measures on galvanized steel sheet from India, Malaysia and Vietnam, and separately launched a sunset review of countervailing measures on imports from India. The review covers July 2025-June 2026, with the final report expected by February 11, 2027. As galvanized steel is the largest end-use sector for zinc, the measures directly affect export costs and competitiveness, potentially impacting Australia’s domestic zinc demand and supply chain. Maintaining the duties would provide some protection for domestic steel and coating capacity, while termination could increase low-priced imports and affect regional zinc consumption. The final outcome remains subject to the authorities’ determination.
Sep 11, 2026 18:30
JCC Hongyuan Copper's $200M Expansion Project Aims to Boost Capacity to 550,000 mt by 2027
Sep 7, 2026 15:43
JCC Hongyuan Copper's $200M Expansion Project Aims to Boost Capacity to 550,000 mt by 2027
Read More
JCC Hongyuan Copper's $200M Expansion Project Aims to Boost Capacity to 550,000 mt by 2027
The 300,000 mt/year copper cathode expansion project of JCC Hongyuan Copper, a subsidiary of Jiangxi Copper Corporation, entered the pre-approval public notice stage of its environmental impact assessment on September 4, with a total investment of approximately 1.416 billion yuan. The project is planned to start construction in September 2026 and be completed in December 2027. Upon completion, JCC Hongyuan's total capacity will jump from 250,000 mt to 550,000 mt.
Sep 7, 2026 15:43
Japanese Yen Increases USD/JPY Drops Below 159 Amid Intervention Speculation
Sep 3, 2026 19:00
Japanese Yen Increases USD/JPY Drops Below 159 Amid Intervention Speculation
Read More
Japanese Yen Increases USD/JPY Drops Below 159 Amid Intervention Speculation
[SMM Precious Metal Express] The Japanese yen spiked sharply during Wednesday's trading, with USD/JPY falling below 159 and closing down 0.92% at 158.69, sparking speculation of Japanese currency intervention. The dollar index also dropped sharply, with a weaker dollar environment providing support for precious metals.
Sep 3, 2026 19:00

