

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
[SMM Analysis] India’s BESS Manufacturing Push Accelerates, but Cell Dependence Remains a Key Bottleneck
In the first quarter of 2026, global energy storage system shipments reached 100.0 GWh, a 96.5% increase from 50.9 GWh in the same period of 2025, bringing quarterly shipments to an entirely new scale.
Sep 30, 2026 08:50 (GMT+8)
SMM Launches Aluminium CBAM Calculator: What Cost Estimates Mean for EU-Bound Offers【SMM Analysis】
As the EU Carbon Border Adjustment Mechanism (CBAM) enters its definitive phase, aluminium trade with Europe requires carbon costs to be assessed alongside metal prices, processing charges and logistics. SMM has launched its Aluminium CBAM Calculator , bringing together product codes, origin, emissions data and certificate prices to support export quotations, European procurement and internal budgeting. The aluminium module offers 58 CN codes and 68 origin/default-value categories, covering unwrought aluminium, profiles, sheet, strip, foil and other products. Annual parameters are available for 2026–2030. Users enter a tonnage and select default emissions or enter verified actual emissions. The page then displays estimated certificates per tonne, total certificates, cost per tonne and total budget, with primary and secondary aluminium routes matched to the applicable data basis. The practical benefit is that assumptions and results appear together. Exporters can specify the product, origin, import period and emissions basis behind a quotation, while buyers can compare sources under consistent conditions. The page includes Chinese and English interfaces, parameter tables and a printable cost-sheet option. How the associated costs are shared between buyers and sellers remains a contractual matter. Certificate exposure should be distinguished from its monetary value. As of 29 September 2026, the calculator incorporates official prices of €75.36 per certificate for Q1 2026 and €75.28 for Q2. The Q3 price has not yet been published. Where a price is unavailable, the page retains certificate-volume estimates and leaves costs blank, rather than substituting an assumed price. The current version excludes deductions for carbon prices paid abroad and assessment of the annual import threshold. Its actual-emissions calculation for complex aluminium goods also lacks the free-allocation adjustment attributable to precursors. The analysis below therefore uses the checked default-value calculation. Results are commercial estimates, not final statutory surrender obligations. For market comparisons, the same aluminium product can carry materially different estimated costs depending on its origin-specific default value. Consider CN 76012040—unwrought aluminium alloys in billet form—with primary route K, the Q2 2026 certificate price and a quantity of 1,000 tonnes. Estimated costs under the Chinese, Indian and Canadian default-value cases are €143.98, €50.41 and €57.86 per tonne, respectively. These figures include the annual default-value mark-up and the benchmark-based free-allocation adjustment. The Chinese and Indian default-value cases differ by approximately €93.57 per tonne. Comparing only the metal price or processing charge may therefore miss a meaningful difference in the buyer's budget. Where other commercial terms are similar, estimated CBAM costs could affect an offer's attractiveness. However, this is not a ranking of producers' actual carbon intensity. Freight, customs duties, quality and delivery terms are also outside this comparison, so the figures alone cannot determine the preferred supplier. This highlights the commercial value of supplier emissions documentation. For producers whose actual emissions are below the applicable default value, supported by compliant verification, actual data may change a buyer's cost assessment. Buyers can use defaults for an initial budget when documentation is unavailable, then reassess using supplier evidence. Exporters consequently have a reason to prepare emissions information alongside their product offers, rather than negotiate solely around country-default differences. Annual parameter changes also warrant attention. Holding the Chinese product's base default value, route and benchmark constant, and assuming that the import year and applicable reporting year coincide, estimated certificate exposure rises from 1.912575 per tonne in 2026 to 2.248150 in 2027—an increase of approximately 17.5%. This reflects a higher default-value mark-up and a smaller free-allocation deduction; it does not imply a rise in future certificate prices. For supply arrangements spanning different years, companies can first compare certificate exposure, then discuss price-update mechanisms and cost sharing. Even while future certificate prices remain unknown, identifying that exposure and obtaining supplier documentation can improve the comparability of offers and procurement budgets.
Sep 29, 2026 17:32 (GMT+8)
[SMM Analysis] Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?
[SMM Analysis: Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?] BHP and Amazon’s EAC pilot separates verified emissions reductions from physical copper trade, giving low-emissions primary copper a new source of environmental value. Recycled copper retains a major energy advantage, but future competitiveness may depend more on traceability, recycled content and verified carbon data, potentially adding an environmental dimension to pricing.
Sep 29, 2026 16:03 (GMT+8)
Latest News

What Could a Cobre Panamá Restart Mean for Global Copper Supply? [SMM Analysis]
7 hours ago

[SMM News] Brazil regulator orders partial halt at Sigma Lithium mine over ‘imminent risk’
9 hours ago
[SMM News] Lithium Argentina outlines phased expansion plan for Cauchari-Olaroz
9 hours ago
[SMM News] Patagonia Lithium completes 72-hour pump test at Cilon
Patagonia Lithium completed a 72-hour pump test at well eight on its Cilon concession, with a flow rate of 2,043 litres/hour and 146,800 litres extracted. Lithium concentration reached 232 ppm at 250m depth. About 34 kg of lithium was pumped, equal to 180 kg of lithium carbonate equivalent (LCE). In the 24-hour recovery test, the water level returned from 52.4m to the static level of 3.64m. The company identified an aquifer zone of interest between 226m and 324m depth and is updating its mineral resource estimate, with a scoping report to follow. The project is at the exploration stage, and no production timeline has been announced.
9 hours ago
[SMM News ] Eramet plans $504.1 million Argentina lithium expansion
On October 2(nd), Eramet is considering a US$350 million brownfield expansion of its Centenario-Ratones lithium project in Argentina, which would add 11,000 mt/y of lithium carbonate equivalent (LCE) capacity to the existing nameplate capacity of 24,000 mt/y. The investment is subject to a final investment decision (FID), which Eramet says could be made by end 2027, and detailed engineering studies are underway. The project reached 90% of nameplate capacity in June, expects it to reach close to 100% by the end of this year. Eramet plans to apply for inclusion under Argentina's Large Investment Incentive Regime (RIGI).
9 hours ago
[SMM News] Prairie Lithium garners C$6.3m federal Canadian funding to reach initial production
SMM Sep 29: Prairie Lithium has secured C$6.3 million in federal financing for its Saskatchewan project through the Business Scale-up and Productivity Program, administered by Prairies Economic Development Canada. The funds will support Phase 1 production, including balance-of-plant systems for a commercial-scale direct lithium extraction (DLE) plant. Repayments are interest-free and start in 2029.
Phase 1 targets 150 mt/y of lithium carbonate equivalent (LCE) as lithium chloride from oilfield brine, with the entire volume covered by an offtake agreement with Hydro Lithium. First brine production is expected in Q4 2026, which would make Prairie Lithium Canada's first commercial-scale lithium producer from oilfield brine.
9 hours ago
[SMM Flash] Gotion and Volkswagen's PowerCo cross-invest in European LFP capacity; Morocco cathode plant included
On Sept 28(th), Gotion High-Tech will invest €1.1 billion ($1.25 billion) for a 49% stake in PowerCo's Valencia plant in Spain, which will become a European production hub for lithium iron phosphate (LFP) batteries. PowerCo, which remains the majority shareholder of the plant, will invest €470 million for a 49% stake in each of two Gotion sites: a cell factory in Šurany, Slovakia, and a new cathode material facility in Kenitra, Morocco. The companies said the agreements are part of a broader plan to jointly develop a European battery supply chain.
9 hours ago
[SMM News ] Liontown lifts FY27 capex guidance by nearly 35% after approving lithium mine expansion
On the 30th of September, Liontown Resources on approved an A$389 million (about $271.68 million) expansion of its Kathleen Valley lithium mine in Western Australia. The company raised its FY2027 total capital expenditure guidance to A$435-495 million, up from A$320-370 million, an increase of about 35% at the midpoint. The higher guidance includes A$175-195 million of Kathleen Valley expansion capital scheduled for FY2027.
This expansion is expected to lift average spodumene concentrate output to about 780,000 dmt per year from FY2030. The company kept its FY2027 spodumene concentrate production guidance unchanged at 390,000-440,000 dmt, so the added volumes fall after the current guidance period.
9 hours ago
Vedanta Plans $2.3 Billion Expansion in India and Saudi Arabia, and Advances Tuticorin Smelter Restart
Vedanta has unveiled a major investment plan, under which Vedanta Copper intends to invest $2.3 billion in India and Saudi Arabia over the next three to four years, targeting annual copper production of more than 1 million tonnes by 2030. The company aims to produce 500,000 tonnes annually in both India and Saudi Arabia, alongside existing production of 100,000 tonnes in Fujairah, UAE. Around $2 billion will be invested in Saudi copper mining, smelting and rod projects, with an investment decision on the proposed Saudi copper smelter expected this quarter. Vedanta is also seeking to restart its Tuticorin copper smelter in India, which has been closed since 2018. The company expects a court ruling within three months and, subject to approval, plans to invest $250 million in refurbishing the facility, targeting a restart within eight to nine months and annual copper output of 250,000 tonnes. Meanwhile, its Silvassa facility is operating at around 95% capacity, with annualised copper cathode production exceeding 245,000 tonnes.
11 hours ago
MMi Daily Iron Ore Report (October 5)
11 hours ago
[SMM Coal Flash] Pakistan’s Thar Block II Phase III Raises Coal Capacity to 11.2 Million Tonnes
12 hours ago
[German Green Steel and Power shares reverse listing gains, down 8% from IPO price]
12 hours ago
[SMM PV Flash] ContourGlobal Completes Construction of 324MW Solar PV Complex in Colorado
12 hours ago
[SMM PV Flash] Germany Anticipates Over 600,000 Tonnes of Solar PV Waste by 2030
According to recent research, with the large-scale aging of early solar power plants, Germany is on course to generate over 600,000 tonnes of end-of-life solar PV modules by 2030. By the end of 2023, installed modules contain significant recyclable materials holding billions of euros in recovery potential for metals like aluminum and silver. Advancing large-scale module recycling not only meets environmental mandates and absorption pressures but also supplements the upstream auxiliary supply chain with extracted high-value metals, paving the way for accelerated growth in Europe's local PV recycling industry.
12 hours ago
[SMM PV Flash] First Solar Sues JA Solar and Corning Subsidiary in US Over TOPCon Patent Infringement
On October 1, US solar manufacturer First Solar filed a patent infringement lawsuit in a Delaware federal court against Chinese module manufacturer JA Solar and American Panel Solutions, a subsidiary of Corning. First Solar alleges that these companies engaged in the unauthorized use of its core patents related to the manufacturing of TOPCon crystalline silicon solar cells. As competition within the global PV supply chain intensifies, technical patent scrutiny targeting leading Chinese module makers expanding overseas is becoming stricter, which may bring uncertainties to their capacity expansion and sales in the North American market.
12 hours ago
[SMM PV Flash] Japan Tightens Grid Access Rules as Battery Queue Reaches 172GW
Japanese regulators have recently tightened grid access rules for renewable energy and storage projects. Under the new regulations, power generators, including battery storage developers, must prove their rights to the project sites to maintain their grid connection queue status. This move aims to curb severe capacity hoarding; currently, the battery queue waiting for grid connection in Japan has reached a staggering 172GW, while actual connected utility-scale storage is less than 1GW. This policy is expected to accelerate the clearing of speculative projects and free up grid capacity for viable solar-plus-storage systems.
12 hours ago
[SMM PV Flash] Brazil Grid Unlocks 56GW Connection Headroom for Battery Storage, Supporting Solar-Plus-Storage
According to the latest technical grid assessment released by Brazil's National Electric System Operator (ONS), available grid connection headroom for battery storage projects has reached 56GW. This capacity significantly exceeds local medium-term power demand estimates, paving the way for upcoming capacity reserve auctions while alleviating grid absorption pressures on regional solar PV systems. The official confirmation of available grid capacity is expected to boost investor confidence in utility-scale solar-plus-storage projects across Brazil.
12 hours ago
[SMM Chromium Flash] Global Chrome Ore Departures Fall 2.74% WoW to 642,500 mt, Maputo Rebounds
Global chrome ore departures totaled 642,500 mt in the week ended October 2, down 2.74% week-on-week, according to SMM's latest data. The modest headline decline masks a significant reshuffling beneath the surface, as a sharp rebound at Maputo was offset by pullbacks at Richards Bay and Mersin.
Maputo departures rose to 488,800 mt from 340,200 mt, a 43.68% increase that lifted the port's share of total departures back to roughly 76% from about 51.5% a week earlier, reversing the prior week's shift toward a more distributed export mix. Richards Bay fell to 95,700 mt from 227,800 mt, a 57.99% decline that gave back the bulk of the prior week's rebound, while Mersin eased 31.52% to 58,000 mt from 84,700 mt. Beira again recorded no chrome ore departures, remaining inactive for a fourth consecutive week.
The week's data points to a reversion toward the more Maputo-concentrated flow pattern seen through most of August and September, with the prior week's broader distribution across ports proving short-lived. Whether Richards Bay's pullback reflects a one-off after an unusually strong prior week or a return to its more intermittent loading pattern will be worth monitoring in the coming weeks.
12 hours ago
[South Africa Moves to Ban Cash Scrap Metal Sales to Curb Infrastructure Theft]
South Africa is moving to ban cash sales of scrap metal under amendments to the Second-Hand Goods Act, aiming to curb illicit trade and infrastructure vandalism that costs about 45 billion rand (2.5 billion USD) a year. Dealers must retain sellers' data and switch to electronic payments, logging each acquisition or disposal; recyclers must record waste pickers' names and ID numbers. Foreign nationals without verified permanent residency lose trading licences, and gold and chrome are also covered. Stolen cable on Transnet rail lines rose from 120km to 724km a year between 2017 and 2021, with incidents up from under 2,000 to nearly 4,500. Copper theft costs Eskom 5-7 billion rand (280-390 million USD) yearly, plus 2 billion rand (110 million USD) to replace cable. The cabinet approved the bill for public comment in August, with a November 2 deadline.
12 hours ago
[India's Steel Exchange India hits record monthly rebar output; September at 25,095 tonnes]
India's Steel Exchange India Limited reported record monthly and quarterly rebar output at its rolling mill, with September 2026 production of 25,095.035 tonnes beating the prior monthly high of 24,823.509 tonnes set in August by about 271.5 tonnes. The continuous casting machine contributed 17,677.655 tonnes and the reheating furnace 7,417.380 tonnes. Monthly output climbed from 19,698.880 tonnes in July to 24,823.509 tonnes in August and 25,095.035 tonnes in September, lifting July-September volumes to a record 69,617.424 tonnes and pointing to a firmer operating run at the mill. The company filed the figures as an operational update under Regulation 30 of SEBI's Listing Obligations and Disclosure Requirements Regulations, 2015. Shares traded at about 0.13 USD (11.23 Indian rupees), up 0.09%, on October 5.
12 hours ago
[SMM Announcement] Chinese Market Metal Prices and News Updates Suspended during National Day Holiday (Oct 1-7)
Dear Valued SMM Users, The National Day holiday is approaching. Please note that SMM Chinese market metal price assessments and news updates will be temporarily suspended during the holiday (October 1-7) and resume normal release after the break. However, SMM overseas price assessment will continue to be updated as usual throughout the holiday. We apologise for any inconvenience caused and wish you a pleasant holiday. Shanghai Metals Market (SMM)
Sep 28, 2026 17:06 (GMT+8)
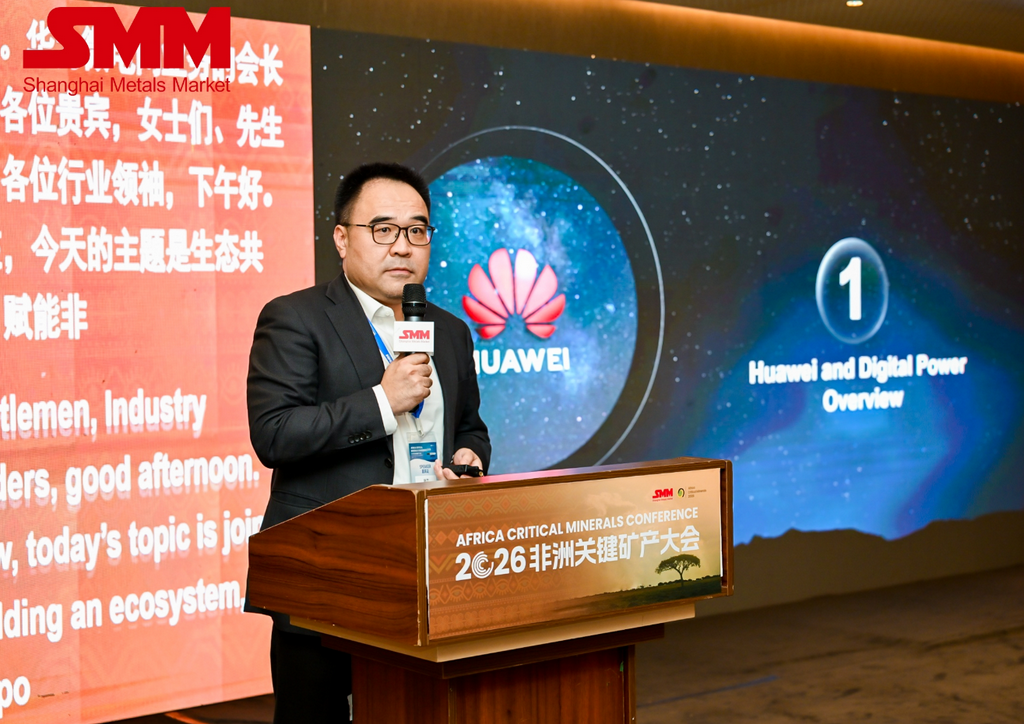
Huawei Pursues Africa Green‑Mining Partnerships and Holds Business Talks with ZESCO at SMM ACM 2026
Sep 23, 2026 16:41 (GMT+8)
[SMM Analysis] The U.S. Copper Tariff Trade Is Fading — but It Isn’t Over Yet
Sep 29, 2026 14:37 (GMT+8)
South Africa Poised to Become Key Player in Global Rare Earth Supply Chain by 2034【SMM Analysis】
Sep 29, 2026 18:54 (GMT+8)
[SMM Analysis] India’s BESS Manufacturing Push Accelerates, but Cell Dependence Remains a Key Bottleneck
Sep 30, 2026 08:50 (GMT+8)
SMM Launches Aluminium CBAM Calculator: What Cost Estimates Mean for EU-Bound Offers【SMM Analysis】
Sep 29, 2026 17:32 (GMT+8)
[SMM Analysis] Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?
Sep 29, 2026 16:03 (GMT+8)
Latest News
What Could a Cobre Panamá Restart Mean for Global Copper Supply? [SMM Analysis]
7 hours ago
[SMM News] Brazil regulator orders partial halt at Sigma Lithium mine over ‘imminent risk’
9 hours ago
[SMM News] Lithium Argentina outlines phased expansion plan for Cauchari-Olaroz
9 hours ago
[SMM News] Patagonia Lithium completes 72-hour pump test at Cilon
9 hours ago
[SMM News ] Eramet plans $504.1 million Argentina lithium expansion
9 hours ago
[SMM News] Prairie Lithium garners C$6.3m federal Canadian funding to reach initial production
9 hours ago
[SMM Flash] Gotion and Volkswagen's PowerCo cross-invest in European LFP capacity; Morocco cathode plant included
9 hours ago
[SMM News ] Liontown lifts FY27 capex guidance by nearly 35% after approving lithium mine expansion
9 hours ago
Vedanta Plans $2.3 Billion Expansion in India and Saudi Arabia, and Advances Tuticorin Smelter Restart
11 hours ago
MMi Daily Iron Ore Report (October 5)
11 hours ago
[SMM Coal Flash] Pakistan’s Thar Block II Phase III Raises Coal Capacity to 11.2 Million Tonnes
12 hours ago
[German Green Steel and Power shares reverse listing gains, down 8% from IPO price]
12 hours ago
[SMM PV Flash] ContourGlobal Completes Construction of 324MW Solar PV Complex in Colorado
12 hours ago
[SMM PV Flash] Germany Anticipates Over 600,000 Tonnes of Solar PV Waste by 2030
12 hours ago
[SMM PV Flash] First Solar Sues JA Solar and Corning Subsidiary in US Over TOPCon Patent Infringement
12 hours ago
[SMM PV Flash] Japan Tightens Grid Access Rules as Battery Queue Reaches 172GW
12 hours ago
[SMM PV Flash] Brazil Grid Unlocks 56GW Connection Headroom for Battery Storage, Supporting Solar-Plus-Storage
12 hours ago
[SMM Chromium Flash] Global Chrome Ore Departures Fall 2.74% WoW to 642,500 mt, Maputo Rebounds
12 hours ago
[South Africa Moves to Ban Cash Scrap Metal Sales to Curb Infrastructure Theft]
12 hours ago
[India's Steel Exchange India hits record monthly rebar output; September at 25,095 tonnes]
12 hours ago