September 24, 2026 news:
This week, the operating rate of leading downstream aluminum processing enterprises in China recorded 62.1%, up slightly by 0.2 percentage points WoW. With the Mid-Autumn Festival and National Day holidays approaching, pre-holiday stockpiling progressed in an orderly manner, and operating rates across all segments remained generally stable. Aluminum extrusion and primary aluminum alloy edged up, while aluminum wire and cable, aluminum plate/sheet and strip, aluminum foil, and secondary aluminum held steady WoW. The operating rate of primary aluminum alloy rose 0.2 percentage points to 60.0%, with industry leaders maintaining normal production and no holiday shutdown plans, but high aluminum prices suppressed downstream procurement, keeping the short-term pattern stable-to-weak. The operating rate of aluminum plate/sheet and strip held steady at 70.0%, as pre-holiday stockpiling demand was released and aluminum prices moved sideways, facilitating smooth shipments, but stricter tax audits tightened aluminum scrap supply, and National Day maintenance may pull the operating rate back slightly. The operating rate of aluminum wire and cable held steady at 64.6%, with production lines running continuously during the double-holiday period, but weak power grid delivery expectations and some post-holiday maintenance may lead to a phased decline in operating rates. The operating rate of aluminum extrusion rebounded 0.9 percentage points to 53.2%, as stable aluminum prices improved order-taking in construction extrusion, and front-loaded energy storage orders in industrial extrusion are expected to keep rates steady through the National Day holiday. The operating rate of aluminum foil held steady at 71.4%, with full orders on hand for battery foil and packaging foil, and stabilizing exports providing support, with a steady trend expected to continue. The operating rate of secondary aluminum held steady at 53.3%, as the peak season underperformed and compliant aluminum scrap supply remained tight, with a slight pullback expected under the impact of the National Day holiday. Overall, pre-holiday stockpiling supported stable industry-wide operating rates, but peak season demand underperformed and cost and raw material pressures persisted, with short-term operations across segments expected to remain stable, and a phased adjustment possible after the holiday.
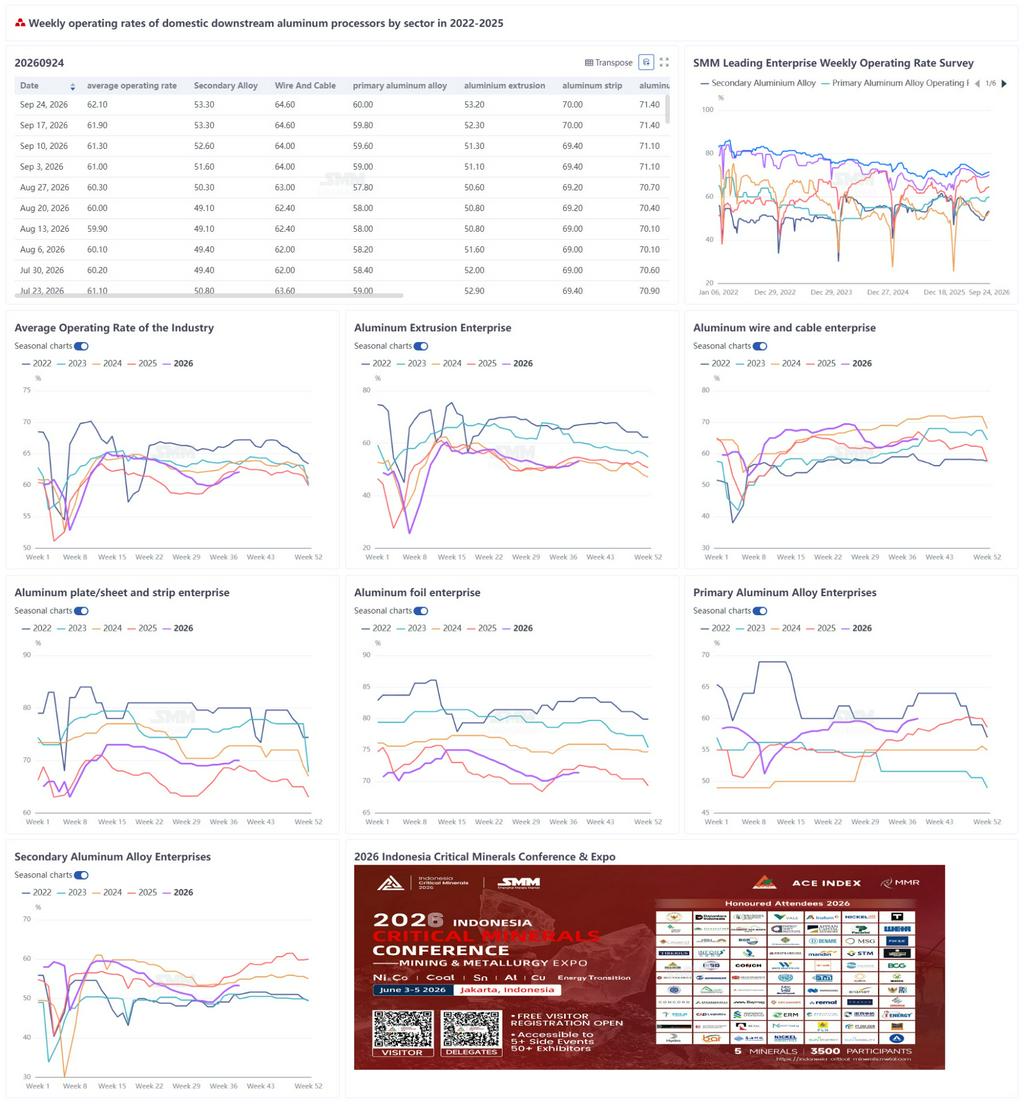
Primary aluminum alloy: This week, the operating rate of leading primary aluminum alloy enterprises in China recorded 60%, up slightly by 0.2 percentage points WoW, continuing a relatively stable operating trend overall. From the enterprise side, industry leaders mostly maintained normal production pace without notable adjustments or fluctuations, and production plans remained generally stable. From the downstream demand side, automobile production recovered somewhat from the prior period, but the recovery fell short of market expectations, and demand growth remained somewhat constrained. Although the traditional September-October peak season has arrived, aluminum prices remained at highs above 24,000 yuan/mt, constraining overall trade activity and downstream procurement demand. High aluminum prices raised procurement costs to some extent and made downstream enterprises more cautious in restocking and purchasing, thereby limiting further demand release. Meanwhile, market feedback indicates that downstream clients currently have no holiday shutdown plans during the Mid-Autumn Festival and National Day holidays, meaning overall production pace will not see significant disruption during the holiday period. Based on this, primary aluminum alloy enterprises generally maintained normal production plans, with production during the holiday expected to see little fluctuation and overall operations to remain stable at current operating rate levels. In summary, the primary aluminum alloy industry currently remains stable on the supply side, while demand has recovered somewhat but fallen short of expectations, and high aluminum prices have suppressed trade and consumption, with the short-term market overall continuing a stable-to-weak operating pattern. After entering the peak season, whether demand can improve further remains to be seen, depending on the actual recovery of end-use industries such as automobiles and changes in aluminum price trends.
Aluminum plate/sheet and strip: This week, the operating rate of leading aluminum plate/sheet and strip enterprises held steady WoW at 70.0%, with pre-holiday production pace stabilizing. At the enterprise level, downstream stocking demand was released before the Mid-Autumn Festival, and aluminum prices consolidated within a narrow range, resulting in smooth shipments and further easing of finished product inventory pressure. On orders, overall peak season characteristics were not pronounced; on the raw material side, stricter tax audits led to tighter aluminum scrap supply, with secondary cast-rolled coil supply in Luoyang, Changge, and other areas tightening. Raw material inventories at large plants were still sufficient to maintain normal production, but the impact on post-holiday operating rates after continued consumption warrants attention. On exports, August aluminum plate/sheet and strip exports were 311,900 mt, down 3.1% MoM and up 17.7% YoY, driven by front-loaded shipments amid expectations of new tariffs on China, with Mexico surging 43% MoM to rank first. Looking ahead to next week, with the National Day holiday approaching, some enterprises are controlling production pace in advance to prepare for holiday maintenance plans, and the operating rate of aluminum plate/sheet and strip is expected to pull back slightly.
Aluminum wire and cable: This week, the operating rate of China's aluminum wire and cable industry held at 64.6%, flat WoW, with overall stable production. According to surveys, with the Mid-Autumn Festival and National Day holidays approaching, mainstream aluminum wire and cable enterprises largely maintained normal production during the holidays, with industry leaders not scheduling shutdowns and production lines running continuously. However, some enterprises reported that they would arrange maintenance for some production lines during the holiday, which may lower loads and exert some downward pressure on post-holiday operating rates. On orders, power grid delivery expectations this year were poor, leading enterprises to mainly produce based on rigid demand and stockpile as needed, with slower delivery pace and relatively insufficient production enthusiasm. On raw materials, pre-holiday stockpiling was largely completed and sufficient to meet holiday production needs, with no reports of raw material supply affecting production. Overall, operating rates during the holiday are expected to remain stable, with a possible phased decline after the holiday due to maintenance and weak orders.
Aluminum extrusion: This week, the operating rate of China's aluminum extrusion industry rose 0.9 percentage points WoW to 53.2%, continuing the marginal recovery pattern from last week. The construction extrusion segment benefited from relatively stable aluminum prices recently, with improved downstream ordering willingness and continued demand recovery in the industry. Some enterprises in Shandong, Hunan, and Fujian reported that the pullback in aluminum prices led to further improvement in order-taking this week, driving a slight recovery in operating rates, but the overall improvement in demand remained limited, and short-term operating rates are expected to remain stable. For industrial extrusion, enterprises generally had ample orders on hand before the holiday, and to ensure post-holiday order delivery, operating rates continued to edge up this week. By segment, energy storage-related extrusion orders continued to grow this week; affected by the lithium battery export tax rebate policy set to be canceled in January, energy storage export demand is expected to be released in a concentrated manner in November, driving notable front-loading of energy storage aluminum extrusion orders. PV frame enterprises faced concentrated delivery pressure after the holiday and early next month, with operating rates maintained at relatively high levels; however, module makers' production schedules in late October are expected to pull back, and frame enterprises remain cautious about the sustainability of subsequent orders. With the National Day holiday approaching, SMM surveys show that aluminum extrusion enterprises' overall holiday duration has shortened compared to last year, with some medium and large enterprises in Hebei, Anhui, Guangdong, and Sichuan indicating that current order delivery pressure is prominent and production lines will maintain normal operations during the National Day holiday. On raw material procurement, enterprises continued the pace of restocking as needed, and the operating rate of aluminum extrusion is expected to remain stable through the National Day holiday next week.
Aluminum foil: This week, the operating rate of leading aluminum foil enterprises held steady WoW at 71.4%. At the enterprise level, leading aluminum foil producers advanced pre-holiday stockpiling and production scheduling in an orderly manner. In terms of order structure, orders on hand for battery foil and packaging foil were both relatively full, providing fundamental support for operating rates. On exports, August aluminum foil exports from China were 120,000 mt, up 0.9% MoM and up 11.9% YoY, with the stabilizing export market effectively providing additional demand support. Looking ahead to next week, pre-holiday stockpiling is progressing in an orderly manner, with strong battery foil support and steady climbing packaging foil as the main drivers, and the aluminum foil operating rate is expected to continue its stable trend.
Secondary aluminum: This week, the operating rate of leading secondary aluminum enterprises held at 53.3%, flat WoW, with overall stable production pace. September consumption peak season performance fell short of expectations, with limited improvement in end-use demand and constrained room for enterprises to ramp up production. Meanwhile, stricter tax invoice policy enforcement led to tight compliant aluminum scrap supply and high procurement costs in multiple regions, increasing production pressure for some enterprises and constraining further production release. On holidays, sample enterprises largely maintained production during the Mid-Autumn Festival, and most enterprises also maintained production during the National Day holiday, with only a few planning to halt production for about 3 days. Overall, this year's production arrangements still mainly featured continuous production or brief shutdowns, but some enterprises extended holidays compared to 2025. Against the backdrop of increasing raw material procurement difficulty and rising operating pressure, some enterprises adjusted production by reducing loads, arranging maintenance, or extending holidays, and flexibly adjusted production schedules based on molten aluminum supply and client orders. Next week, affected by the National Day holiday, the industry operating rate is expected to pull back slightly.
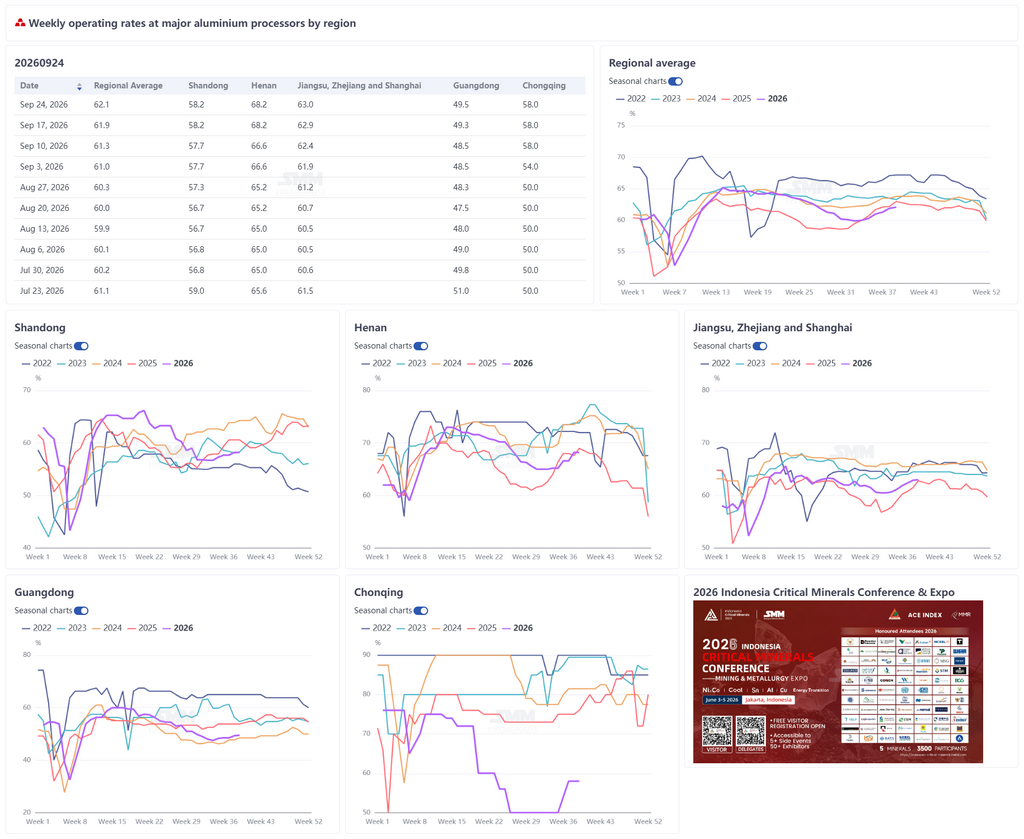
(SMM Aluminum Team)