[SMM Construction Material Inventory] Further Reduction in Crude Steel Production, Decline in Both In-Plant and Social Inventories

게시됨: Mar 13, 2025 18:21 (GMT+8)
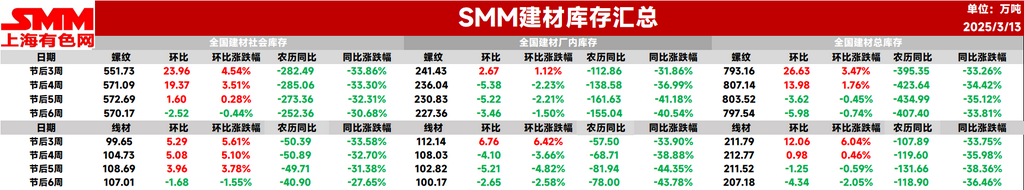
[SMM Construction Material Inventory: Further Reduction in Crude Steel Production, Decline in Both In-Plant and Social Inventory] This week, the total rebar inventory was 7.9754 million mt, down 59,800 mt WoW, a decrease of 0.74% (previous value: -0.45%). On a YoY basis, it decreased by 4.074 million mt compared to the same period last year on the lunar calendar, a drop of 33.81% (previous value: -35.12%).

This week, the total rebar inventory nationwide continued to decrease slightly, with social inventory shifting from an increase to a decrease. The total rebar inventory declined by 0.74% WoW, while the total wire rod inventory fell by 2.05% WoW. During the week, construction steel market prices fluctuated downward, with low market trading activity. However, news of production cuts led to a slight rebound, driving speculative demand in the market. Meanwhile, end-use demand continued to recover, resulting in a slight decline in total construction steel inventory this week.

This week, the total rebar inventory stood at 7.9754 million mt, down by 59,800 mt WoW, a decline of 0.74% (previous value: -0.45%). Compared to the same period last year on the lunar calendar, it decreased by 4.074 million mt, a YoY decline of 33.81% (previous value: -35.12%).

Table 1: Overview of Rebar Inventory
Source: SMM

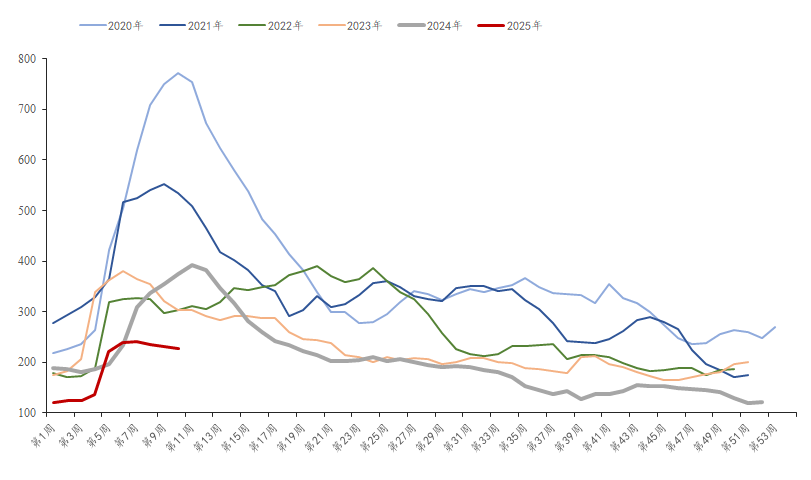
 This week, in-plant rebar inventory was 2.2736 million mt, down by 34,600 mt WoW, a decline of 1.5% WoW (previous value: -2.21%). Compared to the same period last year on the lunar calendar, it decreased by 1.5504 million mt, a YoY decline of 40.54% (previous value: -41.18%). Direct supply from steel mills remained relatively stable. However, spot prices weakened during the week, leading to reduced restocking by agents, while production increased slightly. As a result, the decline in in-plant inventory narrowed compared to last week.

Chart-1: Rebar In-Plant Inventory Trends, 2019-2024
Source: SMM

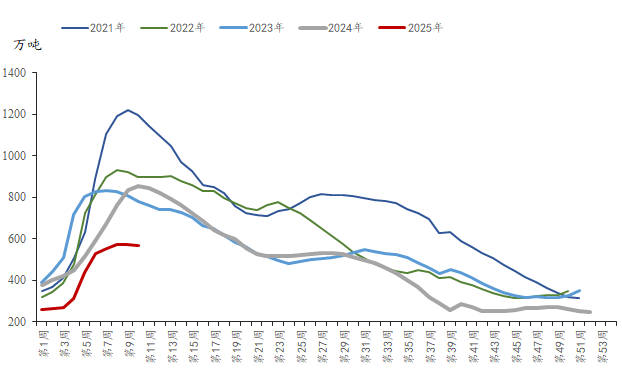
 This week, social rebar inventory was 5.7017 million mt, down by 25,200 mt WoW, a decline of 0.44% WoW (previous value: +0.28%). Compared to the same period last year, it decreased by 2.5236 million mt, a YoY decline of 30.68% (previous value: -32.31%). With the accelerated recovery of demand in northern regions, market spot inventory shifted from an increase to a decrease, marking a turning point in social inventory this week.

Chart-2: Rebar Social Inventory Trends, 2019-2024
Source: SMM

Looking ahead, blast furnace steel mills currently maintain certain profitability, and some blast furnaces in north-west China are scheduled to resume production mid-month after maintenance. The capacity utilisation rate of EAF steel mills has recovered to 40.6%, but their operating rate remains constrained by profitability, making further increases difficult. Construction steel production is expected to increase slightly. On the demand side, with the accelerated recovery in northern regions, demand intensity continues to improve. Although the Two Sessions did not bring substantial benefits, coal mine production cuts and steel production controls are boosting market sentiment. Meanwhile, supply growth remains limited. Construction steel inventory is expected to continue destocking next week, with a larger destocking margin.

데이터 출처 설명: 공개 정보를 제외한 모든 데이터는 SMM이 공개 정보, 시장 커뮤니케이션 및 SMM 내부 데이터베이스 모델을 기반으로 가공한 것입니다. 본 자료는 참고용이며 의사결정 권고를 구성하지 않습니다.

문의 사항이 있거나 자세한 정보를 원하시면 아래로 연락해 주시기 바랍니다: lemonzhao@smm.cn
리서치 보고서 열람 방법에 대한 자세한 내용은 아래로 문의하시기 바랍니다:service.en@smm.cn
관련 뉴스
[2035-36년까지 인도를 지탱할 석탄 화력 — 철강 및 유도로 부문에 활력]
45분 전
[2035-36년까지 인도를 지탱할 석탄 화력 — 철강 및 유도로 부문에 활력]
더 보기
[2035-36년까지 인도를 지탱할 석탄 화력 — 철강 및 유도로 부문에 활력]
[2035-36년까지 인도를 지탱할 석탄 화력 — 철강 및 유도로 부문에 활력]
인도 전력부는 2035~36년까지 석탄이 국가 전력의 거의 절반을 계속 공급할 것이라고 확인했다. 전력 수요 증가와 24시간 재생에너지 공급의 한계로 화력발전이 여전히 필수적이기 때문이다. 이를 위해 인도는 석탄 화력발전 용량을 현재 약 224GW에서 2035~36년까지 약 315GW로 늘릴 계획이다. 이는 철강 및 유도로 업계에 호재다. 향후 10년간 연속적인 용광로 가동과 생산 증가를 뒷받침할 더 안정적이고 신뢰할 수 있는 전력 공급을 의미하기 때문이다.
45분 전
[SMM 철강] 유럽 열연코일: 공급 부족에도 가격 상승 실패
1시간 전
[SMM 철강] 유럽 열연코일: 공급 부족에도 가격 상승 실패
더 보기
[SMM 철강] 유럽 열연코일: 공급 부족에도 가격 상승 실패
[SMM 철강] 유럽 열연코일: 공급 부족에도 가격 상승 실패
[유럽] 제철소 가동이 반복적인 차질을 겪으면서 유럽연합 내 공급이 주기적으로 부족해지고 있다. 이번 주 네덜란드, 독일, 이탈리아에서 세 건의 생산 차질이 보고되었으며, 특히 아르셀로미탈 아이젠휘텐슈타트가 5A 고로의 일시적 부분 가동 중단을 발표했다. 이러한 공급 측면의 강세 요인에도 불구하고 구매 관심은 여전히 부진하여 열연코일 가격은 소폭 상승에 그치며 전반적으로 좁은 범위에서 거래되고 있다. 북유럽에서는 높은 재고 부담으로 제철소들이 760유로/톤 DDP(약 866달러/톤)의 운송비 포함 가격을 제시했으나, 현재 대량 구매를 주저하는 구매자들로 인해 5,000톤 주문의 경우 운송비 포함 가격이 730유로/톤 DDP(약 832달러/톤)까지 협상될 여지가 있는 것으로 나타났다. 트레이더들에 따르면 현재 체결되는 대부분의 거래는 740~760유로/톤 EXW(약 844~866달러/톤) 수준이다. 이탈리아 내수 시장은 여전히 침체되어 있으며, 핵심 과제는 제철소들이 충분한 판매량을 확보하면서도 하류 부문으로 비용을 전가하는 데 어려움을 겪고 있다는 점이다.
1시간 전
[SMM 철강] 해상 병목이 육로를 부추기다: 이란 빌릿·열연코일 국경 프리미엄 장악, 슬래브는 내수로 전환
1시간 전
[SMM 철강] 해상 병목이 육로를 부추기다: 이란 빌릿·열연코일 국경 프리미엄 장악, 슬래브는 내수로 전환
더 보기
[SMM 철강] 해상 병목이 육로를 부추기다: 이란 빌릿·열연코일 국경 프리미엄 장악, 슬래브는 내수로 전환
[SMM 철강] 해상 병목이 육로를 부추기다: 이란 빌릿·열연코일 국경 프리미엄 장악, 슬래브는 내수로 전환
[이란] 이란 철강 수출은 '해상 물류 제약 vs 육로 국경 무역 활황'이라는 뚜렷한 구조적 양극화를 보였다. 러시아와 우크라이나의 흑해 공급 차질로 서아시아 구매 수요가 이란산으로 몰렸다. 이란 공급업체들은 최근 각형 빌렛 최소 1만 5천 톤을 이란 국경 통과 지점 인도 조건(FCA) 톤당 420~430달러에 계약했으며, 주로 이라크를 경유해 시리아와 요르단으로 향하는 물량이다. 국경 혼잡으로 운송비가 상승했음에도 구매자들은 즉시 선적을 확보하기 위해 기꺼이 프리미엄을 지불했다. 반면 해상 수출은 미국 해군의 단속, 선박 부족, 보험료 급등으로 심각한 제약을 받으며 벌크 선적 유동성이 마비되었다(오만 소하르행 운임은 톤당 18~25달러). 주요 제철소들의 11월 말까지 생산 일정이 완전히 찬 상태에서 현물 해상 유동성은 여전히 부족했으며, 인근 걸프 시장에 톤당 410~415달러 FOB 조건으로 판매된 소량의 빌렛에 국한되었다. 특히 슬래브 수출은 제철소들이 전적으로 내수에 집중하면서 완전히 중단되었다. 판재류 부문에서는 열연코일(HRC)이 샬람체 국경 통과 지점을 통해 이라크로 톤당 540~560달러 FCA 조건으로 꾸준히 거래되었다. 한편 카스피해 항로에서는 가용 선복 부족으로 러시아산 물량의 계약이 성사되지 못하며 수입 활동이 사실상 동결 상태를 유지했다.
1시간 전