SHANGHAI, May 6 (SMM) - This is a roundup of China's metals weekly inventory as of May 6.
Domestic Aluminium Inventory Increased After The Labour Day Holiday, But Fell YoY
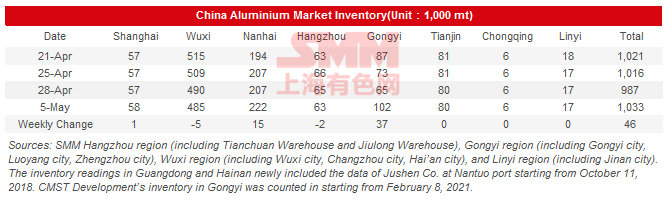
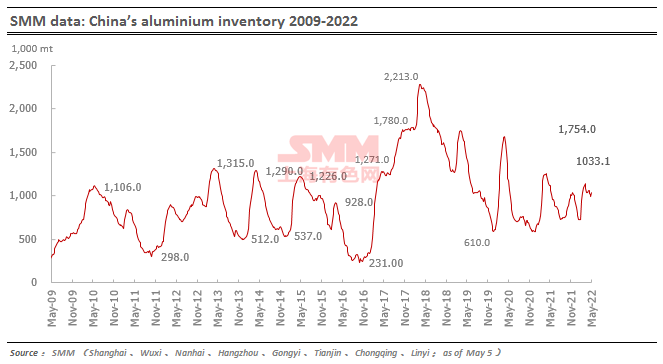
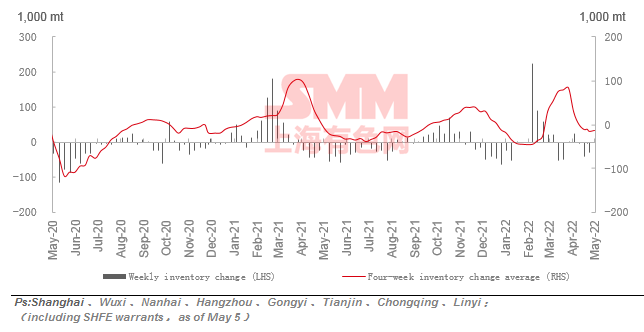
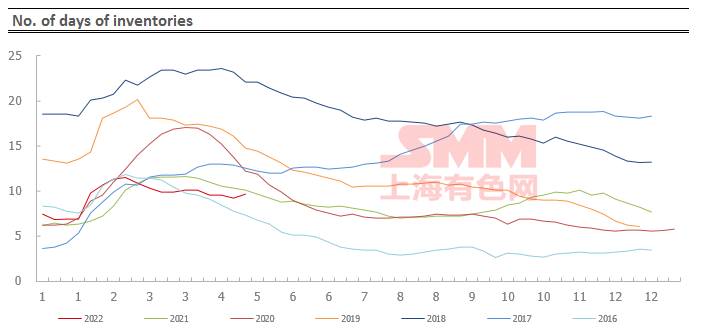
The aluminium ingot social inventories across China’s eight major markets totalled 1.03 million mt as of May 5, up 46,000 mt from a week ago, but 82,000 mt lower than a year ago. Concentrated arrivals during the holiday pushed inventory in Gongyi up by 37,000 mt from pre-holiday level to 100,000 mt. Henan stepped up restrictions on truck transportation due to recurrence of the pandemic, but arrivals were little affected as cargoes were shipped mainly by railway. Due to complicated transportation procedures, cargo pick-up from warehouses in Henan was mainly done by local buyers. Inventory in Nanhai increased by 15,000 mt mainly due to the increase in arrivals during the holiday. Inventory in Wuxi fell 5,000 mt thanks to gradual recovery of logistics. Inventories in Tianjin, Chongqing, Linyi and other regions were basically stable. Aluminium suppliers are under pressure to sell following concentrated arrivals. Downstream operating rates picked up slightly after the pandemic situation improved a little, but downstream buyers remain cautious about buying in light of the pandemic. The US dollar index fell back after the US Fed’s interest rate hike decision. Aluminium prices may face downward pressure in the near term.
Inventory of Aluminium Billets in China Rose 22,700 mt to 128,600 mt after the Labour Day Holiday
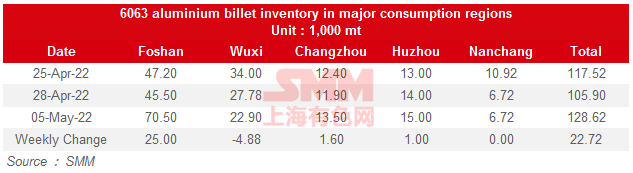
The domestic aluminium billet inventory stood at 128,600 mt as of May 5, an increase 22,700 mt or 21.45% from a week ago. The regional inventory changes were as follows: Nanchang (unchanged); Changzhou (+1,600 mt or 13.45%); Wuxi (-4,900 mt or 17.58%); Huzhou (+1,000 mt or 7.14%); Foshan (+25,000 mt or 54.95%). Large arrivals from Yunnan during the holiday and stagnant trades caused inventory in Foshan to surge. There were rumours that local enterprises in Wuxi’s Jiangyin may be ordered to shut down or lower output due to recurrence of pandemic, which would hurt local consumption. Given the continued disruption of consumption due to the pandemic,downstream buyers turned more cautious. However, as aluminium prices are heading down towards 20,000 yuan/mt, demand may get some boost. Buyers will restock after inventories are digested, which will ease inventory pressure.
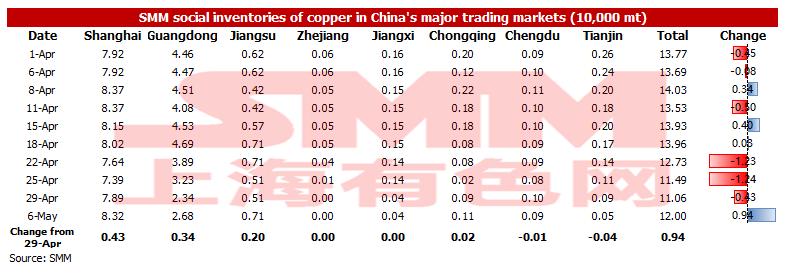
Copper Inventories across Major Chinese Markets up 9,400 mt from April 29
SMM data showed that copper inventories across mainstream areas in China increased 9,400 mt from last Friday April 29 to 120,000 mt as of Friday May 6. Compared with the data last Friday, the inventory in most regions of China this week increased, while the inventories in Chengdu and Tianjin dropped slightly. The total inventory fell 221,900 mt from the same period last year when the inventory was recorded 341,900 mt. According to SMM research, the operating rates of most downstream enterprises in various regions of the country during the Labour Day holiday this year were not as high as that of the same period last year as many manufacturers had a longer holiday. SMM believes that there are two reasons which contributed to the increase in inventory after the holiday that was less than expected. First, many smelters directly shipped goods to downstream. Second, many copper cathode stagnated at plants due to the transportation problem.
In detail, the inventories in Shanghai increased 4,300 mt to 83,200 mt, the inventories in Guangdong rose 3,400 mt to 26,800 mt, the inventory in Jiangsu added 2,000 mt to 7,100 mt, the inventory in Chongqing rose 200 mt to 1,100 mt, and the inventory in Tianjin dipped 400 mt to 500 mt. Stimulated by the maintenance of smelters in the north and the downstream consumption, the inventory in Tianjin has been decreasing recently.
Looking forward, with the sharp drop in copper prices after the holiday, downstream consumption is gradually improving. In addition, most downstream copper enterprises did not purchase any goods before the Labour Day holiday, so SMM expects that these companies will increase their purchasing volume next week, and the weekly inventory will drop again.
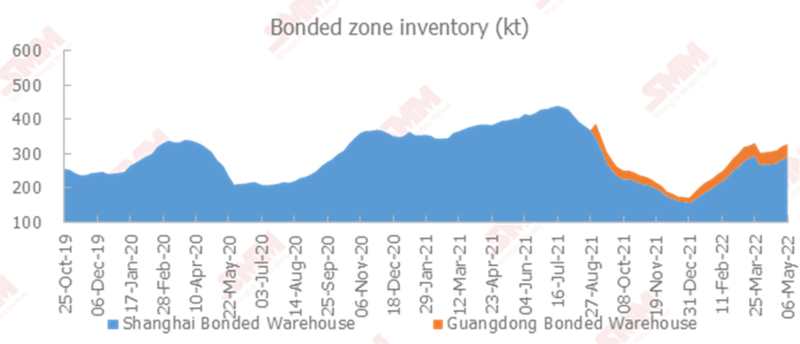
Copper Inventories in Domestic Bonded Zone up 400 mt during the Labour Day Holiday
Copper inventories in the domestic bonded zone increased by 400 mt from April 29 to 329,100 mt on May 6, according to the SMM survey. Inventory in the Shanghai bonded zone increased by 3,500 mt to 292,800 mt, while inventory in the Guangdong bonded zone dipped by 3,100 mt to 36,300 mt. The SHFE/LME price ratio continued to improve this week. The enthusiasm for imported copper trading was heated by the opening of the import window on Thursday and Friday. Importers in Guangdong shipped their sources of warrants to China, which led to the decline in domestic inventory. However, due to the pandemic control measures in Shanghai, the operation of the Shanghai bonded zone was still abnormal. Besides, goods piled up at ports early were waiting to be moved into the warehouses one after another, hence the inventory increased a little.
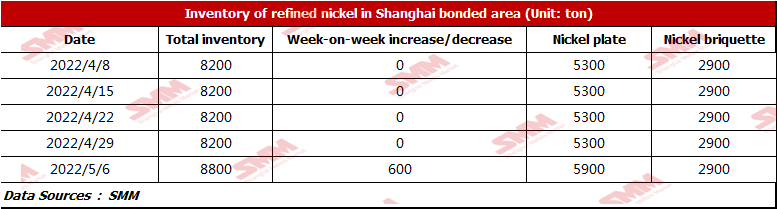
Nickel Inventory in Shanghai Bonded Zone Slightly Increased
LME nickel was pulled back continuously this week. Due to the macro factors, SHFE nickel prices remained rangebound at high levels, and the price ratio was improved. Nickel inventory in Shanghai bonded zone was 8,800 mt this week, up 600 mt from last week. The inventory of nickel briquettes and nickel plates was 2,900 mt and 5,600 mt respectively. The increase in nickel plate inventory in the domestic bonded zone was contributed by the long-term orders signed by domestic enterprises that waiting for customs clearance.
Nickel Ore Inventories at Chinese Ports Fell 235,000 wmt
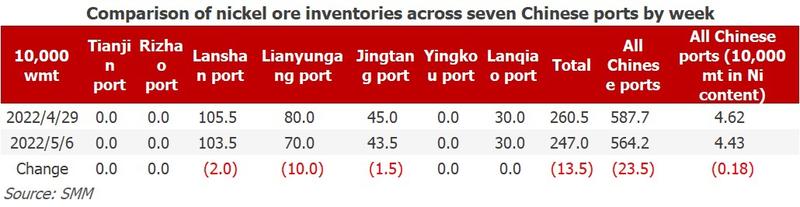
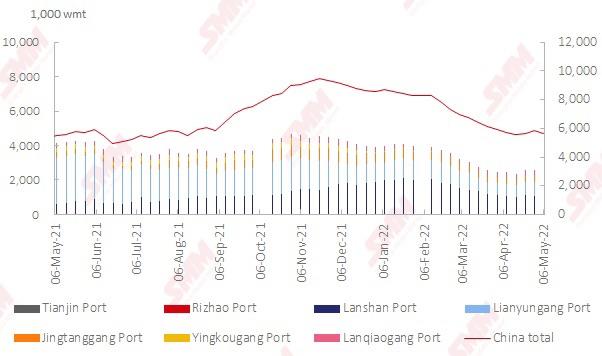
As of May 6, the nickel ore inventory at Chinese ports decreased by 235,000 wmt from last week to 5.642 million wmt. Total Ni content stood at 44,300 mt. The total inventory at seven major ports across China stood at 2.47 million wmt, down 135,000 wmt from the previous week. Port inventory of nickel ore dropped a little. For now, the increase in inventory is not stable, and the inventory will be maintained at the current level. On the demand side, the transportation problem was solved to some extent as the pandemic got eased, and the NPI plants began to restock. Besides, NPI plants gradually recovered from the pandemic, and their profits were considerable, which demanded more nickel ore. On the supply side, shipment from the Philippines increased as the rainy season was over. However, it still takes some time for the shipments to return to the normal level. In addition, the pandemic slowed down the efficiency of loading and unloading at ports. Therefore, the increase in nickel ore supply was limited. In the short term, it is expected that the port inventory of nickel ore will be maintained at the current level, and the inventory will gradually increase.