SHANGHAI, Jul 9 (SMM) – This is a roundup of China's metals weekly inventory as of July 16.
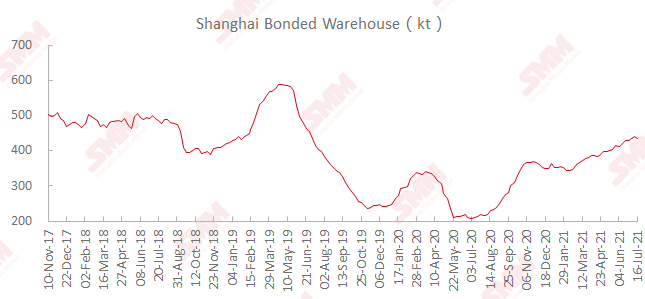
Shanghai bonded copper stocks fell 4,300 mt on week
Stocks of copper in Shanghai bonded areas decreased on smaller arrivals after the increase for five consecutive weeks.
SMM data showed that the stocks fell 4,300 mt from the prior week to 435,500 mt as of Friday July 16.
Domestic stocks continued to decline due to the maintenance of domestic smelters in the early stage with the effect of low import inflow and refined copper replacing scrap copper. The import profit window opened this week, and foreign trade demand jumped. The premium of Yangshan copper warehouse receipts has risen sharply since mid-week, and the increase of import demand for customs declaration in the market lifted up the outbound quantity, which led to a decline in stocks in the bonded area.
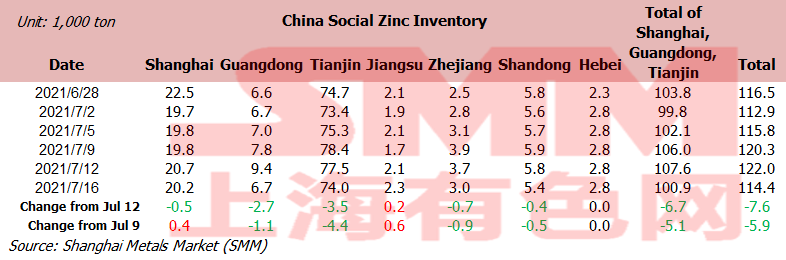
Zinc social inventories shrank 5,900 mt on week
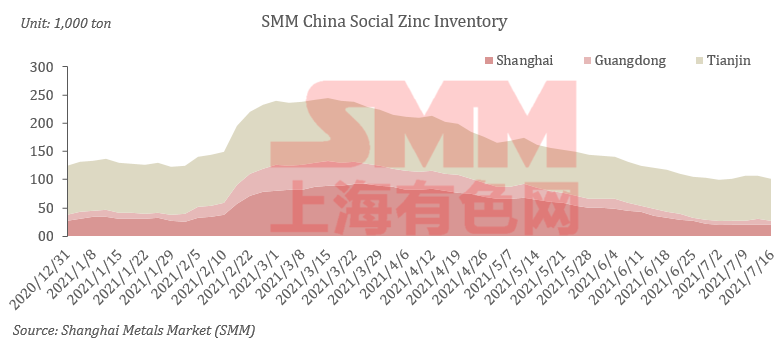
SMM data showed that social inventories of refined zinc ingots across Shanghai, Tianjin, Guangdong, Jiangsu, Zhejiang, Shandong and Hebei decreased 5,900 mt in the week ended July 16 to 114,400 mt. The stocks fell 7,600 mt from Monday June 12.
Stocks in Shanghai decreased on week but was slightly higher than last Friday as market arrivals improved. In south China's Guangdong, market arrivals fell slightly and downstream purchase increased when zinc prices declined, leading to a decrease in stocks. Stocks in Tianjin fell as rebounded steel prices led to the improvement of downstream orders and market demand improved when zinc prices fell.
Stocks across the three major trading hubs (Shanghai, Tianjin and Guangdong) fell 5,100 mt this week, after a 6,200 mt increase last week.
Nickel ore inventories at Chinese ports fell 172,000 wmt to 5.34 million wmt
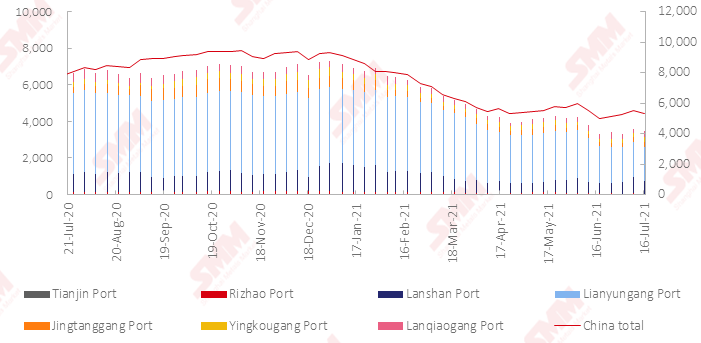
Nickel ore inventories across all Chinese ports decreased 172,000 wmt from July 9 to 5.34 million wmt as of July 16, showed SMM data.
In Ni content, the stocks stood at 42,100 mt.
SMM data also showed that nickel ore stocks across seven major Chinese ports decreased 164,000 wmt during the same period to 3.41 million wmt.
Stocks in Lanshan Port declined sharply this week, the port concentrated on picking up goods, and the ferronickel production remained high. It is difficult for nickel ore stocks to increase significantly in the near future.
Shanghai bonded refined nickel stocks fell 500 mt on week
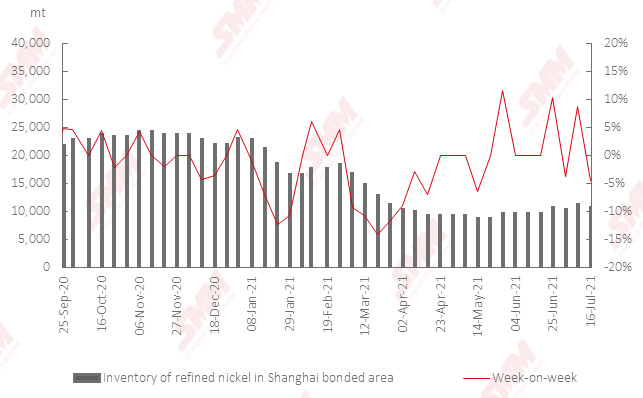
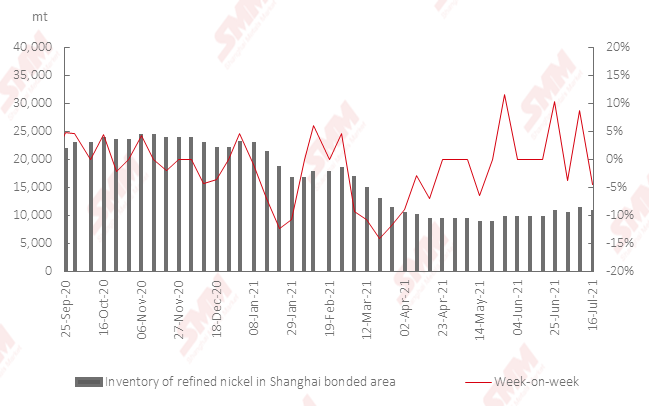
Inventories of refined nickel in the Shanghai bonded areas decreased 500 mt from a week ago and stood at 10,700 mt as of July 16, showed SMM data.
The ratio of SHFE nickel to LME nickel improved this week, and there were constantly import profit opportunities in the middle of the week, so all the goods at port were declared directly. Few nickel plates were moved into the bonded area, and nearly 500 mt of nickel plates were cleared after leaving the warehouse, so the stocks dropped to 10,700 mt.
Silicon social inventories up 4,000 mt on week
Social inventories of silicon metal across Huangpu port, Kunming city and Tianjin port expanded 4,000 mt from the previous week to 36,000 mt as of Friday July 16.
The inventories in Kunming stood flat amid the stagnated transportation in the pandemic, and the foreign trade orders will be delivered next week. Traders gradually turned to purchase goods at ports. The inventories mainly increased in the southern and northern ports this week. Silicon metal inventories are expected to further increase next week based on recent market trade and supply.
Lead ingot social inventories up 14,200 mt on week
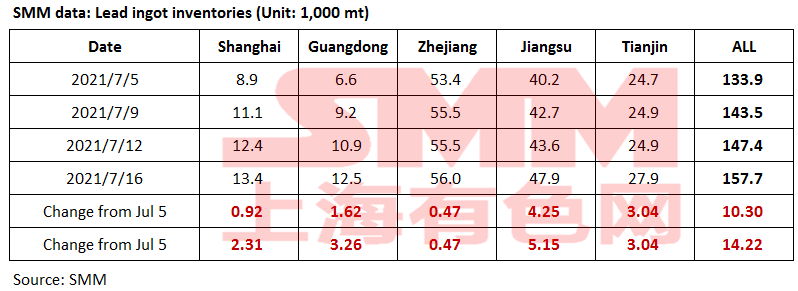
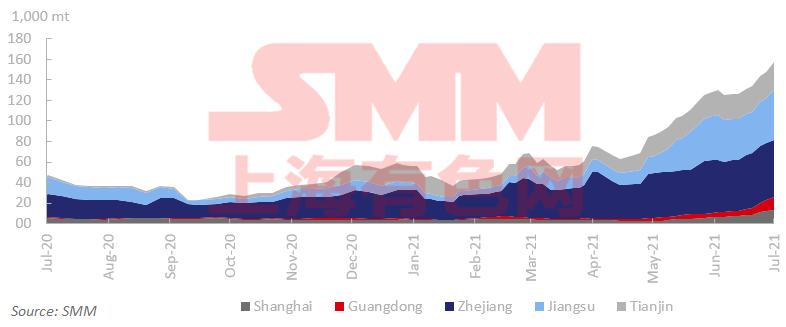
Social inventories of lead ingots across Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin rose 14,200 mt from last Friday and increased 10,300 mt from July 12 to 157,700 mt as of July 16, hitting a new high since December 2014, an SMM survey showed.
SHFE 2107 lead contract was settled this week, and more goods were transferred to delivery warehouses, leading to the increase in social inventories. The storage capacity of CMST’s delivery warehouse was expanded from 20,000 mt to 40,000 mt in No.1 Lugang Sijing Branch Road, Lulugang Logistics Industrial Park, Beichen District, Tianjin, China. The production of primary and secondary lead will stay stable next week, while the consumption recovery will be limited. However, the holders’ deliveries of goods may slow down as the next settlement day is still far away. The increase in the lead ingot social inventories is expected to be slower, and the stocks may rise in some smelters.
Operating rates of primary lead smelters up 0.24 percentage point on week
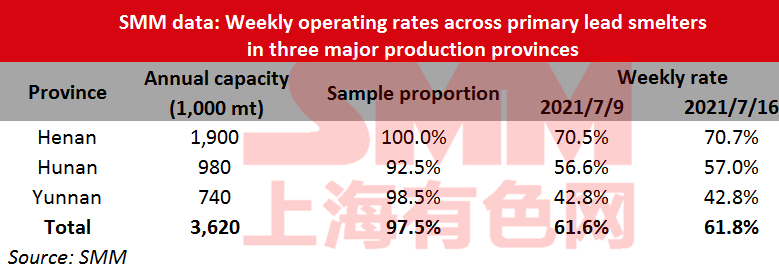
Operating rates across primary lead smelters in Henan, Hunan and Yunnan provinces gained 0.24 percentage point from the previous week to 61.8% in the week ended July 16, showed an SMM survey.
In Henan, Shibin slightly increased production than normal in July, while Minshan reduced production slightly. Yunnan Mengzi started the maintenance on lead smelter system for 20 days this week, and is expected to resume production in August. Refined lead production stood normal this week, but the output is expected to drop slightly next week. Chifeng Shanjin resumed production after maintenance, but not in full capacity, and is expected to return to normal next week. Smelters in Yunnan has received the notice of power curtailment, but the actual production cut is still in assessment, and there's not significant impact on the current output.
Operating rates of secondary lead smelters up 2.92 percentage points on week
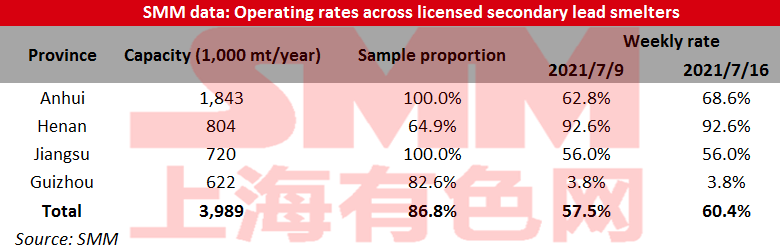
Operating rates across licensed smelters of secondary lead in Jiangsu, Anhui, Henan and Guizhou averaged 60.41% in the week ended July 16, up 2.92 percentage points from the previous week, showed an SMM survey.
In Anhui, Tianchang gradually resumed normal production after maintenance, and Dadao further recovered production this week. The production in other regions basically remained stable. Besides the sample companies, Hubei Jinyang resumed production as planned this week, contributing to the overall output increase. Some plants in Guangdong and Jiangxi reduced production due to low profits and environmental protection, which had little impact on the overall production resumption. Anhui Tianchang will have normal production next week, likely to bring output increase. Operating rates are expected to further rise.
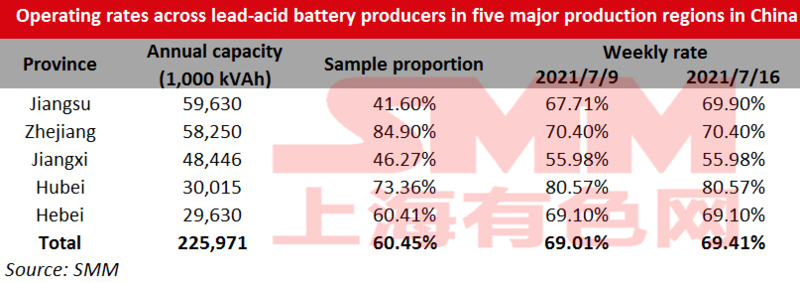
Operating rates of lead-acid battery plants up 0.4 percentage point on week
Operating rates across lead-acid battery producers in Jiangsu, Zhejiang, Jiangxi, Hubei and Hebei provinces gained 0.4 percentage point from July 9 to 69.41% as of Friday July 16.
Battery consumption changed after mid-July. The replacement demand in the electric bicycle battery market rebounded, and rising battery prices boosted expectations, bringing more orders to some companies. The companies planned to increase production. However, it is harder for workers to operate in the plants due to the frequent high temperatures in July, so the production remain largely unchanged in most companies. Car battery consumption was still flat, and the production was basically stable with the schedule based on the sales.
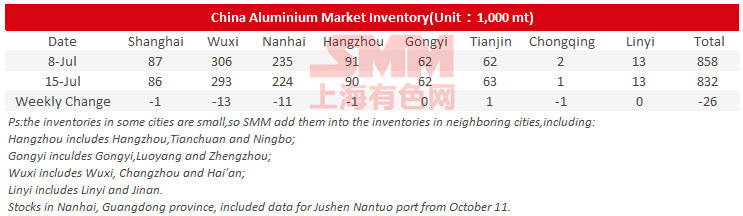
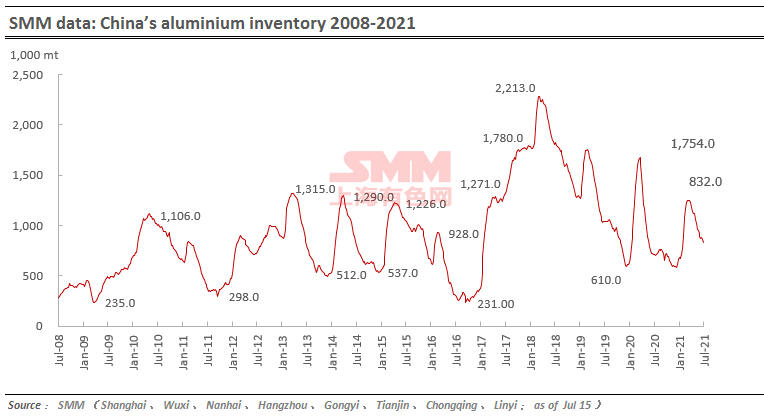
Primary aluminium inventories fell 26,000 mt on week
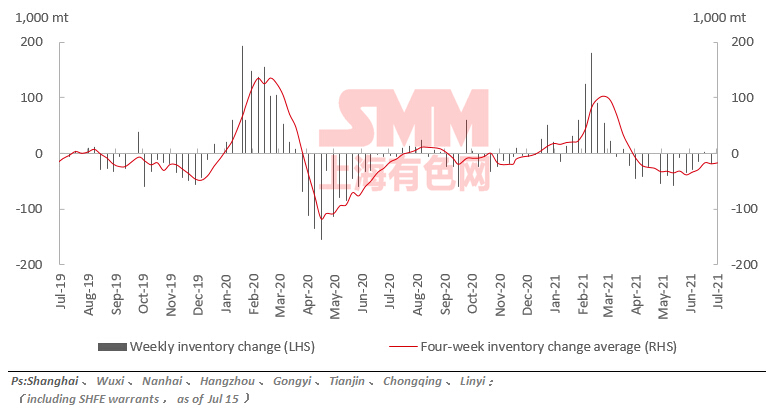
SMM data showed that China’s social inventories of aluminium across eight consumption areas fell 26,000 mt on the week to 832,000 mt as of June 24, mainly due to the decline in Wuxi and Hainan.
Aluminium billet inventories fell to 120,800 mt on week
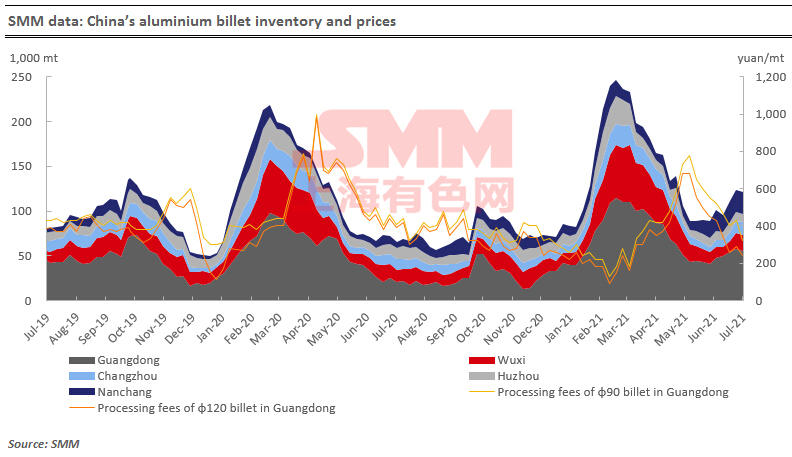
The outbound volume of the aluminium billet rose by 800 mt to 48,300 mt last week, an increase of 1.6%. Aluminium prices fluctuated at high levels, and downstream users were less willing to purchase.
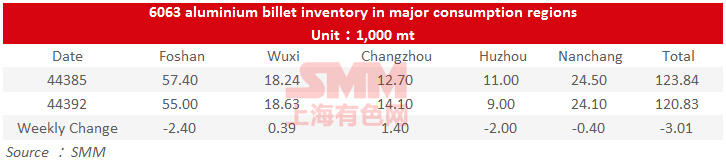
The stocks of aluminium billet in five major consumption areas fell by 3,000 mt to 120,800 mt from the previous week, a slight decrease of 2%. Stocks in Wuxi and Changzhou rose this week, and Changzhou saw an increase of 1,400 mt or 11% on the week. The inventories fell in Foshan, Huzhou, and Nanchang, and the decrease was significant in Foshan and Huzhou.
The overall market trading was flat this week, as aluminium prices stood high amid the bullish factors such as PBOC’s lower required reserve ratios and power rationing in Yunnan. Downstream wait-and-see sentiment increased.
According to SMM survey, aluminium downstream orders is likely to further decline, and the consumption momentum is weak in the off-peak season. The outbound volume of aluminium billet is expected to drop next week, and the inventories may further increase.
China HRC inventory rose 47,100 mt on week
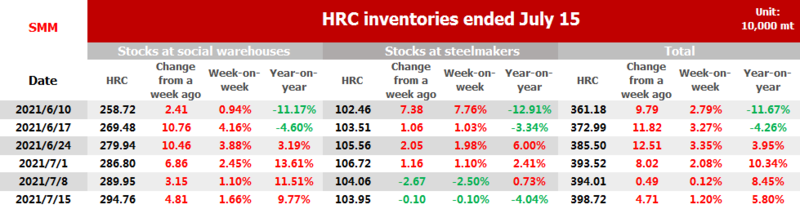
SMM data showed that HRC stocks across social warehouses and steel makers rose 47,100 mt or 1.2% on the week, an increase of 5.8% than a year ago, to 3.99 million mt in the week ended July 15.
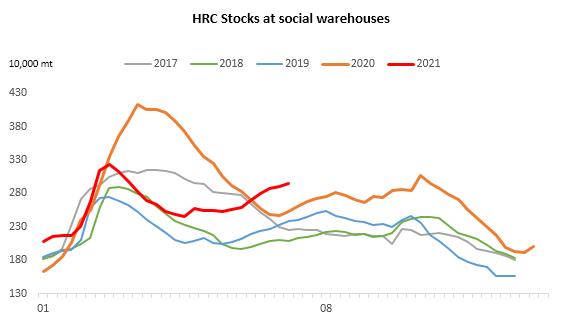
Inventories across social warehouses increased 48,100 mt or 1.66% week on week to 2.95 million mt. This was 9.77% higher than the same period last year.
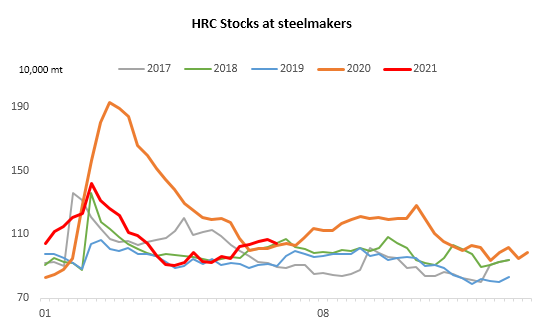
Stocks at Chinese steel makers came in at 1.04 million mt, down 1,000 mt or 0.1% week on week and 4.4% year on year.
China steel rebar inventory down 0.4% on week
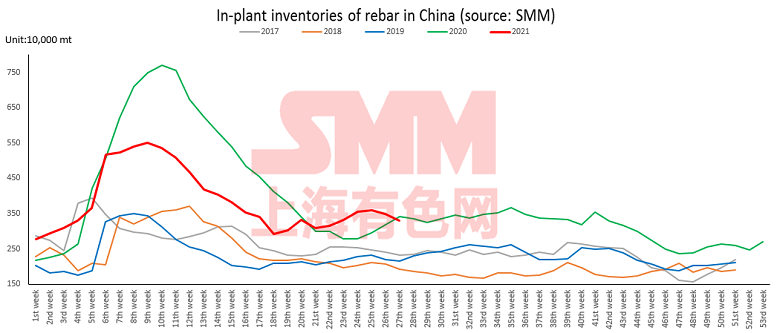
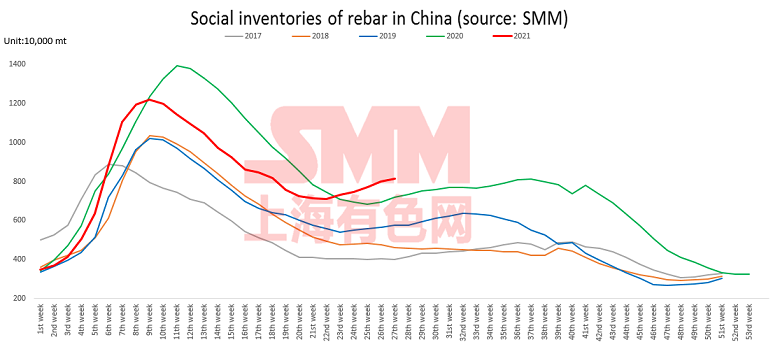
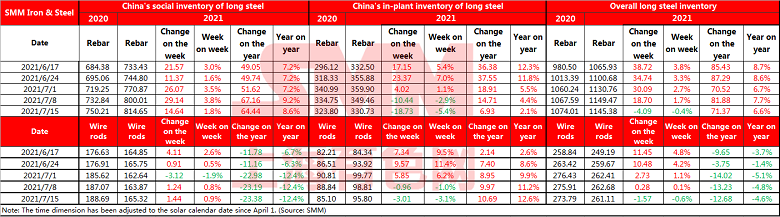
Inventories of rebar across Chinese steelmakers and social warehouses stood at 11.45 million mt as of July 15, down 0.4% from a week ago. Stocks are up 6.6% from a year earlier. The continuous growth of steel production has been initially curbed.
Inventories at Chinese steelmakers fell 187,300 mt on the week and stood at 3.31 million mt. Stocks are down 5.4% from a week ago and up 2.1% from a year earlier.
Inventories at social warehouses rose 146,400 mt on the week and stood at 8.15 million mt, up 1.8% from a week ago and 8.6% higher from a year ago.
Operating rates of blast furnaces across Chinese steelmakers fell 0.6 percentage point on week
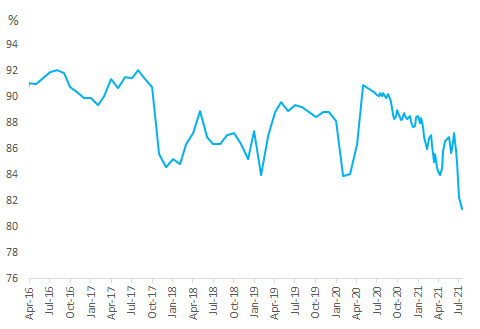
Operating rates of blast furnaces at steel mills fell 0.6 percentage point from a week ago and decreased 4.4 percentage points from a month ago to 81.4% as of July 15, SMM survey showed. Production reductions have been strictly implemented in many places across the country, and the scope of reductions has continued to expand. Operating rates of blast furnaces continued to decline, which strengthened the expectation of production reductions in the second half of the year. The output data for July also reflected the effect of the reduction.
Operating rates of blast furnaces at Chinese steelmakers