Impact from high copper prices and secondary copper slowed recovery in copper rods produced with copper cathode

Telah Terbit: Mar 23, 2021 10:27 (GMT+8)
Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues.

SHANGHAI, Mar 23 (SMM)—Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues. Cash flow issues are expected to intensify due to high tax payment in April. As such, factories and suppliers should liquidate stocks.
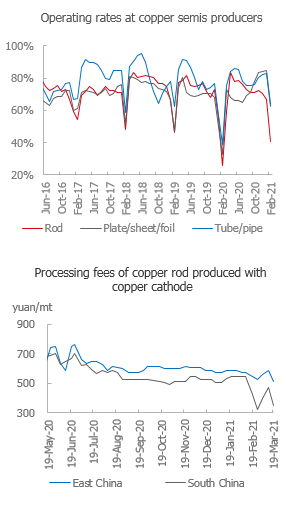
Operating rates at copper rod producers using secondary copper as raw material should return to a high level in March against accumulated orders, boosting secondary copper demand. However, decreased new orders at the end of last week and increased cash flow issues have limited the interest in purchasing. That combined with the demand for stock liquidation at suppliers, will keep normal supply and demand.

The average weekly price of #1 bare bright copper without invoice stood at 59,930 yuan/mt, an increase of 200 yuan/mt compared with the previous week, and the weekly average price difference between copper cathode and copper scrap stood at 2,217 yuan/mt, an increase of 385 yuan/mt. The average weekly discount of copper rod produced with secondary copper stood at 1,464 yuan/mt against the SHFE front-month copper contract, growing the advantage compared to copper rod produced with copper cathode.

For imported copper scrap, cif quotes for #1 copper scrap were Comex July copper less $0.21/lb, and offers for birch/cliff were Comex July copper less $0.36/lb. US brass was quoted at $5,650-5,850/mt. The coefficient for copper granules (98%) against LME copper stood at 93%, and the coefficient for bare bright copper against LME copper at 96-96.5%, on a cif basis.

Improved consumption of copper rod produced with secondary copper had significant impact on consumption of copper rod produced with copper cathode

Many producers of copper rod using secondary copper as feedstock have seen high orders, reporting strong supply and demand. The price spread between copper cathode and copper scrap has returned to above 2,000 yuan/mt, and discounts of copper rod produced with secondary copper reached a high of 1,550 yuan/mt against the SHFE front-month copper contract. Low-priced copper rods produced with secondary copper have been more desirable for downstream companies amid high copper prices, and this depressed consumption of copper rod produced with copper cathode which has been already weak. 

The impact of poor wire and cable demand and secondary copper rods has slowed recovery in the market of copper rod produced with copper cathode. Most of the producers are unlikely to return to normal production levels in March. As consumption picks up amid warmer weather, the market sentiment of the wire and cable industry should rise. Consumption of copper rods produced with copper cathode is expected to improve in April. However, the overly high copper price will depressed consumption. The current inventory of finished products at copper rod producers using copper cathode as feedstock stands at high levels. Producers will prioritise stock depletion and new orders at end users are unlikely to pass to copper rod plants using copper cathode as raw material any time soon. We believe that consumption of copper rods produced with copper cathode in April would hardly return to the peak season level of previous years.
Pernyataan Sumber Data: Kecuali informasi yang tersedia untuk publik, semua data lainnya diproses oleh SMM berdasarkan informasi publik, komunikasi pasar, dan mengandalkan model database internal SMM. Hanya untuk referensi dan tidak menjadi rekomendasi pengambilan keputusan.

Untuk pertanyaan atau informasi lebih lanjut, silakan hubungi: lemonzhao@smm.cn
Untuk informasi lebih lanjut tentang cara mengakses laporan penelitian kami, hubungi:service.en@smm.cn
Berita Terkait
Studi Kelayakan Awal Proyek Iberian Belt West Emerita Menunjukkan NPV $776 Juta, Umur Tambang 21 Tahun
30 Oct 2026 22:39 (GMT+8)
Studi Kelayakan Awal Proyek Iberian Belt West Emerita Menunjukkan NPV $776 Juta, Umur Tambang 21 Tahun
Baca Selengkapnya
Studi Kelayakan Awal Proyek Iberian Belt West Emerita Menunjukkan NPV $776 Juta, Umur Tambang 21 Tahun
Emerita merilis PFS untuk proyek seng-timbal-tembaga Iberian Belt West: NPV US$776 juta, umur tambang 21 tahun Emerita Resources (TSXV: EMO) merilis Studi Kelayakan Awal (PFS) yang positif pada 29 Oktober untuk proyek polimetalik Iberian Belt West (IBW) yang 100% dimilikinya di Sabuk Pirit Iberia, Spanyol. Studi tersebut menunjukkan NPV setelah pajak sebesar US$776 juta pada tingkat diskonto 8%, IRR 23,51%, umur tambang 21 tahun, dan periode pengembalian modal setelah pajak 1,9 tahun. Belanja modal awal sebesar US$567 juta termasuk kontinjensi. Cadangan terkira awal berjumlah 23,4 juta ton dengan kadar 2,30% seng, 1,13% timbal, 0,45% tembaga, 53 g/t perak, dan 1,07 g/t emas.
30 Oct 2026 22:39 (GMT+8)
Pasar Tembaga Tertekan Perubahan Pajak dan Kelangkaan Pasokan pada Oktober 2026
30 Oct 2026 19:47 (GMT+8)
Pasar Tembaga Tertekan Perubahan Pajak dan Kelangkaan Pasokan pada Oktober 2026
Baca Selengkapnya
Pasar Tembaga Tertekan Perubahan Pajak dan Kelangkaan Pasokan pada Oktober 2026
Pada Oktober 2026, selisih harga termasuk pajak antara logam primer dan skrap menyempit dari 3.979 yuan/mt pada awal pekan menjadi 1.896 yuan/mt, kemudian pulih ke kisaran 2.826-2.976 yuan/mt. Selisih harga antara batang tembaga katoda dan batang tembaga sekunder juga tertekan dari 1.250 yuan/mt ke titik terendah ekstrem di bawah 430 yuan/mt sebelum memantul ke 1.450 yuan/mt. Meskipun keunggulan substitusi secara pembukuan berfluktuasi, sebagian besar waktu hal itu tergerus oleh faktor biaya.
30 Oct 2026 19:47 (GMT+8)
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
30 Oct 2026 18:41 (GMT+8)
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
Baca Selengkapnya
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
30 Oct 2026 18:41 (GMT+8)