SHANGHAI, Apr 1 (SMM) - This is a roundup of China's metals weekly inventory as of April 1.
Aluminium Ingot Inventory in China Began to Grow after Consecutive Weeks of Decline
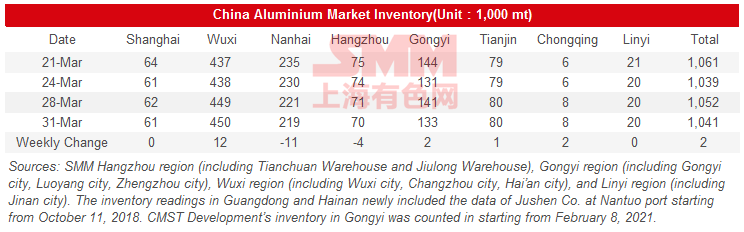
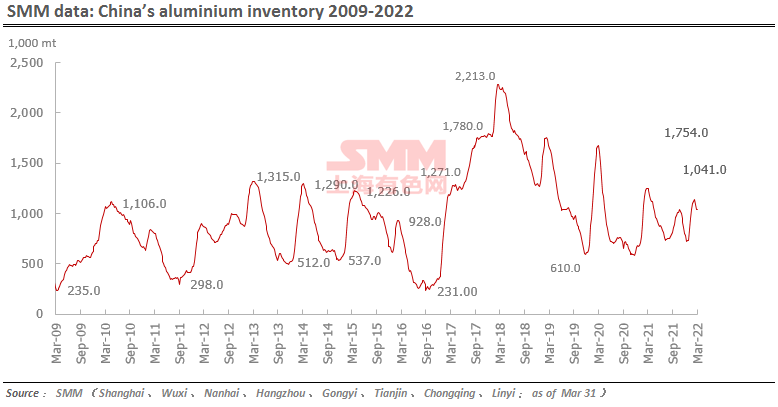
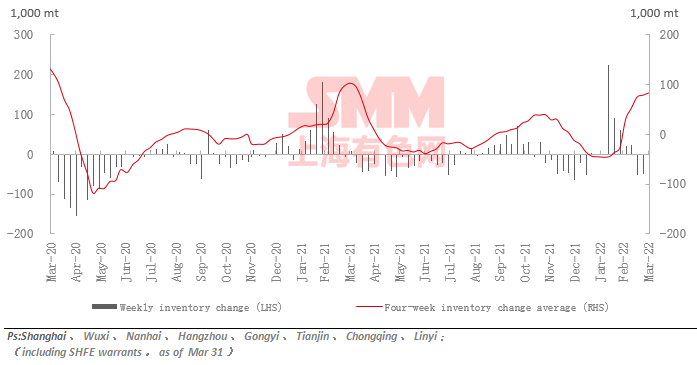
The domestic aluminium ingot social inventory totalled 1.04 million mt as of March 31, up 2,000 mt from last Thursday, but down 11,000 mt from this Monday. The pandemic disrupted inflows and outflows of cargoes in many regions. The inventory in Gongyi and Nanhai fell 8,000 mt and 2,000 mt respectively when compared to this Monday, and was flat in Tianjin, Chongqing and Linyi, but rose 1,000 mt in Wuxi.
With no easing of the pandemic in sight any time soon, it is expected that the total inventory will drop slightly next week. Market will be focused on how the pandemic will affect the arrivals and consumption.
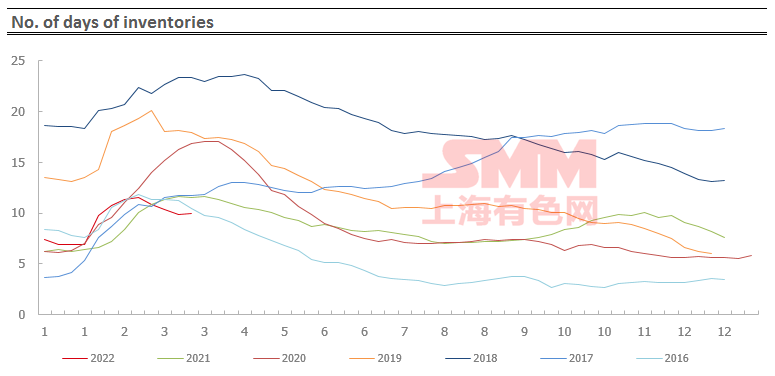
Inventory of Aluminium Billets in China Declined to 157,500 mt
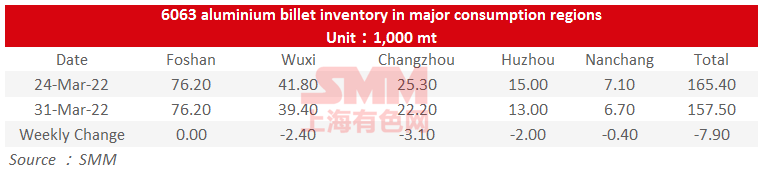
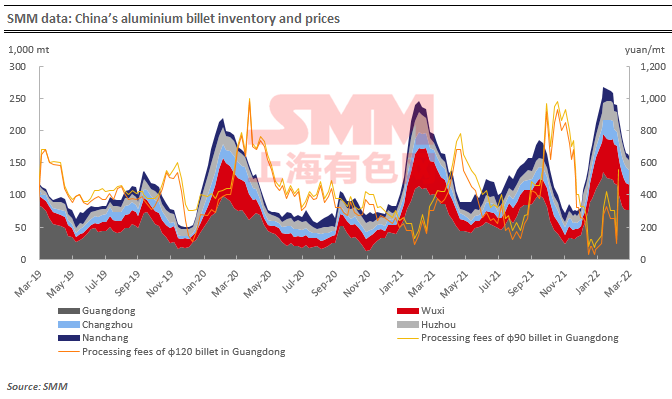
The domestic aluminium billet inventory stood at 157,500 mt as of March 31, a drop of 7,900 mt or 4.76% from a week ago. The inventory declined across each of the five major regions: Nanchang (-400 mt or 5.37%); Changzhou (-3,100 mt or 12.25%); Wuxi (-2,400 mt or 5.73%); Huzhou (-2,000 mt or 13.33%), except in Foshan, where the inventory was unchanged.
The pandemic-induced transportation problems in Wuxi prompted buyers to pick up cargoes from Changzhou, where the pandemic was less severe, leading to a sharp decline in local inventory. Due to the impact of the pandemic on downstream consumption and transportation, the inventory decline slowed down significantly.
Trades in the spot aluminium billet market were sluggish under the influence of the pandemic. Given the intensity and sustainability of pandemic control measures, the aluminium billet inventory may stop falling next week.
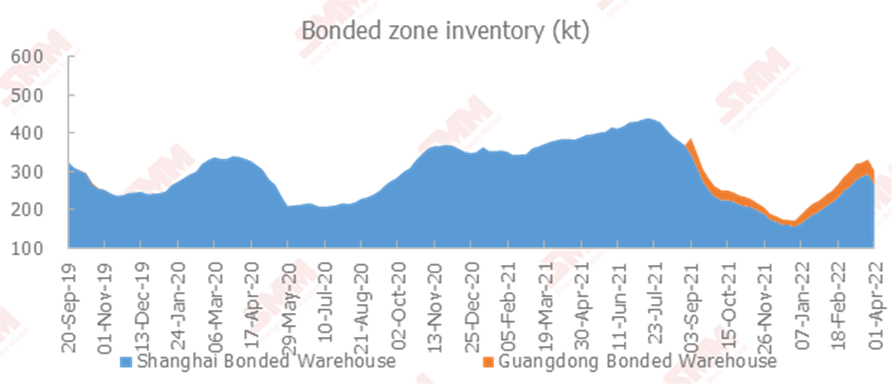
Copper Inventories in Domestic Bonded Zone up 1,800 mt from Monday
Copper inventories in the domestic bonded zone increased by 1,800 mt from March 25 to 304,400 mt on April 1, according to an SMM survey. Inventory in the Shanghai bonded zone increased 3,500 mt to 269,800 mt, and inventory in the Guangdong bonded zone dropped 1,700 mt to 34,600 mt. The import window remained closed this week, and the inventory only increased slightly when the demand for customs declaration was low. Affected by the COVID-19 outbreak, operations in the Shanghai Bonded zone stagnated, and the transactions in the imported market stood still.
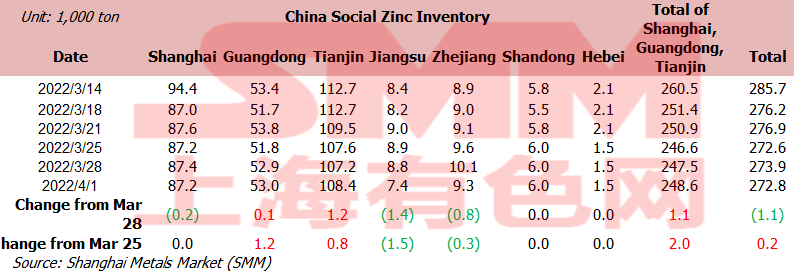
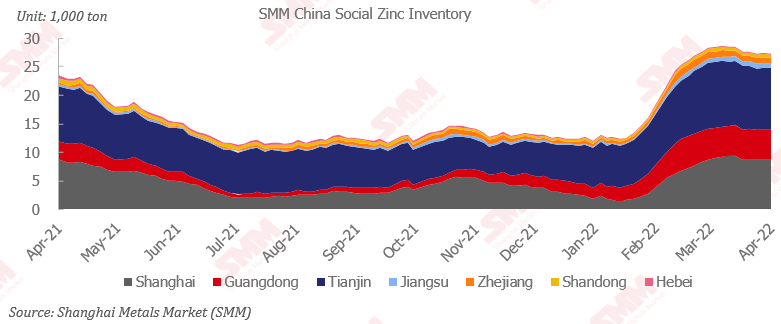
Zinc Inventories across Seven Markets up 200 mt from Mar 25
Total zinc ingots inventories across seven markets stood at 272,900 mt as of Friday April 1, up 200 mt from March 25, down 1,100 mt from March 28. Domestic inventories increased slightly. Overall, the delivery of the inventory was affected by the pandemic. In the Shanghai market, only a small amount of goods arrived through the rail transport. Due to poor shipments, the overall inventory of the market remained unchanged. In the Guangdong market, the arrivals were relatively stable with slight decrease, but downstream procurement reduced due to the high prices. Therefore, the shipments were weak with small increase of inventory. In the Tianjin market, there were a small number of arrivals, while the inventory rose slightly caused by the average demand. Inventories in Shanghai, Guangdong and Tianjin rose 2,000 mt, and inventories across seven Chinese markets increased 200 mt.
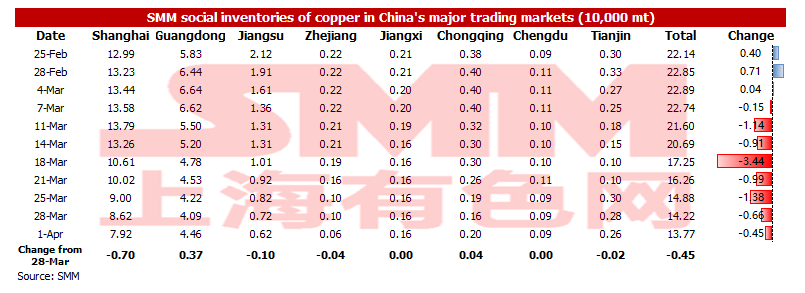
Copper Inventory in Major Chinese Markets Fell 4,500 mt
As of April 1, SMM copper inventory across major Chinese markets dropped 4,500 mt from Monday to 137,700 mt, a decrease of 11,100 mt from last Friday. Destocking this week is slower than that in last week. Weak consumption aroused by the COVID-19 outbreak resulted in the decline of inventory this week. Compared with the data on Monday, except for the inventory in Guangdong and Chongqing, the inventory in other parts of China slightly decrease. In detail, the inventories in Shanghai decreased 7,000 mt to 79,200 mt, the inventories in Jiangsu dropped 1,000 mt to 6,200 mt, the inventory in Zhejiang fell 400 mt to 600 mt, and the inventory in Tianjin dipped 200 mt to 2,600 mt. The inventory in Guangdong increased 3,700 mt to 44,600 mt, and the inventory in Chongqing increased 400 mt to 2,000 mt.
In east China, especially in Shanghai and Jiangsu, the logistics efficiency has been seriously reduced due to the pandemic this week. SMM believes that this situation will last at least until April 5, so it is expected that the local inventory will rise during the Tomb-sweeping holiday The increase of inventory in Guangdong is mainly contributed by the overhaul of some copper rod enterprises with poor consumption this week and the concentrated arrival of imported copper. In addition, the poor inter-provincial logistics in the early stage have improved this week, and the arrival of domestic copper has also increased. Oversupply leads to an increase in inventory.
Looking forward, due to the poor consumption caused by the pandemic, SMM expects that there will be an accumulation of inventory during the Tomb-sweeping holiday. Whether the inventory can decline or not after the holiday depends on the degree of pandemic control in east China.
Downstream Manufacturers have Strong Demand for Goods Delivery
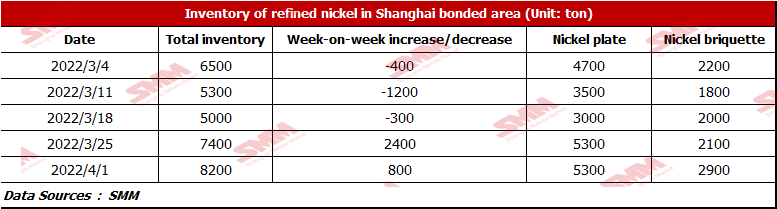
LME nickel has experienced two big fluctuations and has little liquidity this week. Affected by LME nickel, SHFE nickel is weak this week, and the import losses still exist and stabilise. The inventory of nickel briquette in the bonded zone is 8,200 mt, up 800 mt from last week. The inventory of nickel plates is 5,300 mt, which is the same as last week. Due to the COVID-19 outbreak, the inventory in Shanghai bonded zone changes little this week, and the imports and exports in the Shanghai bonded zone have stagnated. The increase in nickel briquette stocks is mainly due to the low in-plant inventory of nickel sulphate in Chinese smelters, and the high demand for goods delivery by the manufacturers who have signed the long-term purchase agreement for raw materials. At present, LME nickel has not got rid of the capital game, and SHFE nickel is greatly affected by the price trend of LME nickel. The customs clearance in the following days depends on the LME nickel prices.
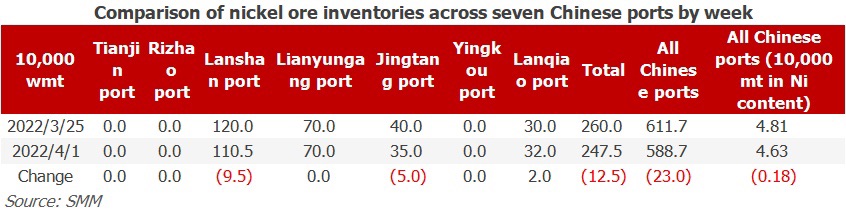
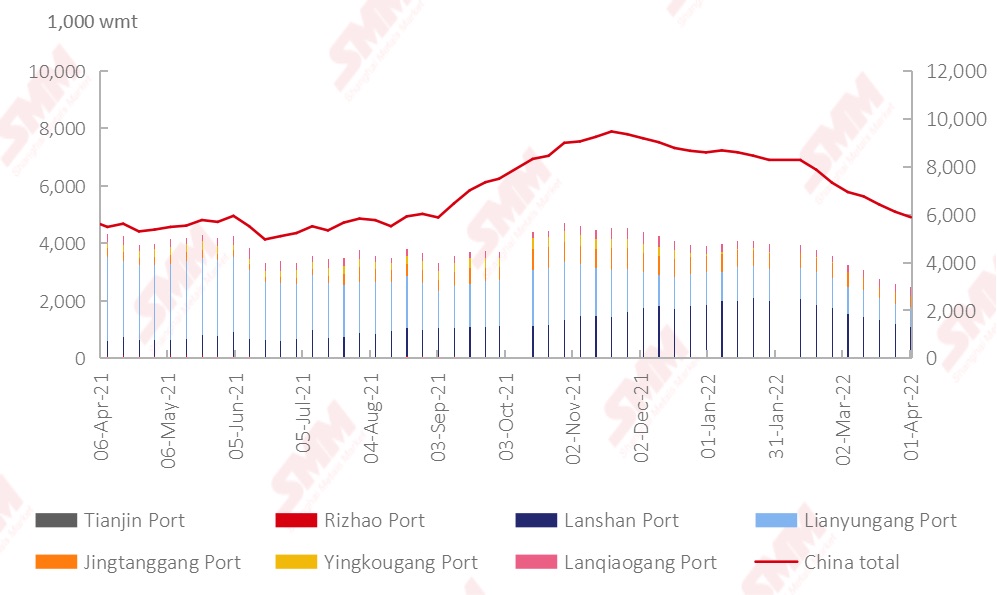
Nickel Ore Inventories at Chinese Ports down 230,000 wmt
As of April 1, the nickel ore inventory at Chinese ports dipped 230,000 wmt from a week earlier to 5.887 million wmt. Total Ni content stood at 1,800 mt. The total inventory at seven major ports stood at 2.475 million wmt, 125,000 wmt lower than last week. Port inventory continues to decline, and it is at a relatively low level in history now. According to SMM research, the rainy season in the Philippines is coming to an end, but the shipment volume cannot rise rapidly. Therefore, it is expected that the growth rate of domestic imported nickel ore will be slow, and the port inventory will be hard to accumulate. The demand for nickel ore is not reduced due to the good profits in NPI plants. In general, it is expected that the destocking speed of nickel ore will slow down in the following days.
Disclaimer:
The above representation and data is based on market information SMM believes to be reliable at the time of acquiring as well as the comprehensive assessment by SMM research team, and any and all information provided in this article is for reference only. This article does not constitute a direct recommendation for investment or any decisions in any form and clients shall act on their own discreet and any decisions made by clients are not within the responsibility of SMM.