The fourth Central people's Bank of China accelerated the issuance of RMB and rose sharply in response.

Publié: Jun 11, 2019 14:44

SMM6 11: at 08:30 this morning, the central bank issued an announcement saying that in order to improve the RMB bond yield curve, the central bank will issue RMB central bank bills in Hong Kong in late June.
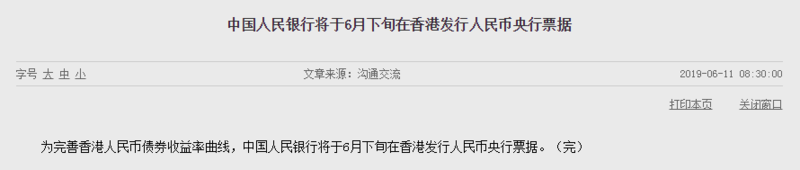
 

One stone stirred up thousands of waves, the renminbi offshore rose, the biggest increase of more than 200 points. This is the fourth time that the central bank has landed in Hong Kong since it was issued on November 7, 2018, February 13, 2019 and May 15, 2019. The scale of the issuance of RMB central bank bills has not yet been disclosed.

It can be seen that the first three central bank tickets were basically issued at intervals of three months, while the fourth time was less than one and a half months from the third one and a half months. In fact, since the third issue of the central bank note on May 15, the US dollar against the renminbi has basically been in a horizontal state, and the central bank's foreign exchange reserves increased by $6 billion in May, so why should the central bank issue the fourth batch of central bank notes in such a hurry?

This should be an arrangement and preparation for the central bank to prepare ahead of time, which will intimidate short positions in the renminbi. We know that central bank bills are one of the means of central bank financing. By issuing bills, the central bank draws money from the offshore market, thereby reducing the liquidity of RMB in the offshore market and cracking down on short positions. The stronghold of international bears is mainly in Hong Kong, and there have been constant voices of bad RMB. The signal released by the central bank to the bears this time is that more frequent central bank ticket operations are coming. Short sellers will pay a heavy price if they continue to short the renminbi.

Since 19 May, we have seen that the four central bank leaders have repeatedly shouted to the market, emphasizing that China has the foundation, confidence, and ability to maintain the basic stability of the RMB exchange rate at a balanced and reasonable level. Regulators have accumulated a wealth of experience in dealing with exchange rate fluctuations, there are sufficient reserves of policy tools, there will be no "accident" in the foreign exchange market and "accidents" will not be allowed, and speculation against the renminbi will inevitably suffer huge losses. This is actually the declaration of Bao 7 revealed by the central bank. On the one hand, the central bank boosted market confidence by shouting, on the other hand, it accelerated the issuance of central bank bills to cut off the idea of short positions in the renminbi, which can be described as a two-pronged approach. Therefore, we have every reason to believe that the RMB exchange rate will not break 7.

Déclaration sur la source des données : À l'exception des informations publiques, toutes les autres données sont traitées par SMM sur la base d'informations publiques, d'échanges avec le marché et en s'appuyant sur le modèle de base de données interne de SMM. Ils sont fournis à titre indicatif uniquement et ne constituent pas des recommandations décisionnelles.

Pour toute demande d'information ou pour en savoir plus, veuillez contacter : lemonzhao@smm.cn
Pour plus d'informations sur l'accès à nos rapports de recherche, veuillez contacter :service.en@smm.cn
Actualités Connexes
[Le renouvellement des contrats et l'offre restreinte propulsent les primes du cuivre au comptant à Shanghai vers un nouveau sommet annuel après un repli initial]
il y a 10 heures
[Le renouvellement des contrats et l'offre restreinte propulsent les primes du cuivre au comptant à Shanghai vers un nouveau sommet annuel après un repli initial]
Lire la suite
[Le renouvellement des contrats et l'offre restreinte propulsent les primes du cuivre au comptant à Shanghai vers un nouveau sommet annuel après un repli initial]
[Le renouvellement des contrats et l'offre restreinte propulsent les primes du cuivre au comptant à Shanghai vers un nouveau sommet annuel après un repli initial]
il y a 10 heures
Taux d'exploitation hebdomadaire SMM des entreprises chinoises de plaques d'anode en cuivre secondaire à 52,43 %
il y a 12 heures
Taux d'exploitation hebdomadaire SMM des entreprises chinoises de plaques d'anode en cuivre secondaire à 52,43 %
Lire la suite
Taux d'exploitation hebdomadaire SMM des entreprises chinoises de plaques d'anode en cuivre secondaire à 52,43 %
[SMM Marché des anodes en cuivre] Du 11 au 17 septembre, le taux d'exploitation hebdomadaire SMM des entreprises chinoises de plaques d'anode en cuivre secondaire a rebondi de 1,03 point de pourcentage en glissement hebdomadaire pour atteindre 52,43 %. Il devrait reculer de 0,62 point de pourcentage en glissement hebdomadaire la semaine prochaine pour s'établir à 51,81 %.
il y a 12 heures
[SMM Analysis] La révision du Règlement sur les transferts de déchets de l’UE fait face à une nouvelle incertitude concernant sa première liste de destinations autorisées
il y a 12 heures
[SMM Analysis] La révision du Règlement sur les transferts de déchets de l’UE fait face à une nouvelle incertitude concernant sa première liste de destinations autorisées
Lire la suite
[SMM Analysis] La révision du Règlement sur les transferts de déchets de l’UE fait face à une nouvelle incertitude concernant sa première liste de destinations autorisées
[SMM Analysis] La révision du Règlement sur les transferts de déchets de l’UE fait face à une nouvelle incertitude concernant sa première liste de destinations autorisées
Analyse SMM : Le règlement révisé de l’UE sur les transferts de déchets fait face à de nouvelles incertitudes concernant sa première liste de destinations autorisées. Le projet de liste du règlement européen sur les transferts de déchets accroît le risque que l’Inde, la Thaïlande, la Malaisie et la Chine perdent l’accès direct à certains flux européens de déchets métalliques à partir de mai 2027. Les déchets de cuivre pourraient être redirigés vers des marchés agréés ou de l’OCDE, augmentant les coûts de traitement et de conformité. SMM s’attend à une offre négociable plus restreinte et à une concurrence accrue, ce qui soutiendrait les taux de reprise des déchets de cuivre de haute qualité.
il y a 12 heures

