Changes in Sodium Battery Cell and Sodium Material Prices in September 2024Q3 Prices Continued to Decline [SMM Sodium Battery Analysis]

Publicado: Oct 15, 2024 16:20 (GMT+8)
Fuente: SMM
In September 2024, the last month of 2024Q3, the overall shipment and price of sodium batteries were relatively mediocre, falling short of previous market expectations. Financing for some enterprises stagnated, affecting the progress of sodium battery projects. Cathode and sodium battery cell enterprises were active, while the anode sector still showed no significant movement.

SMM, October 15th:

In September 2024, the last month of Q3 2024, the overall shipment and prices of sodium batteries were relatively mediocre, falling short of previous market expectations. Financing for some enterprises stagnated, affecting the progress of sodium battery projects. Cathode and sodium battery cell enterprises were active, while the anode sector still showed no significant movement.

There were nearly twenty key projects in September, involving an investment amount of over 13 billion, including cathode, anode, and electrolyte of the three major materials, with sodium battery cell and sodium cathode projects accounting for the majority. The projects were distributed across multiple provinces nationwide.

The prices of various materials continued to decline in September.

I. In terms of battery cells: LFP prices remained at a low level, and sodium battery cell prices decreased significantly.
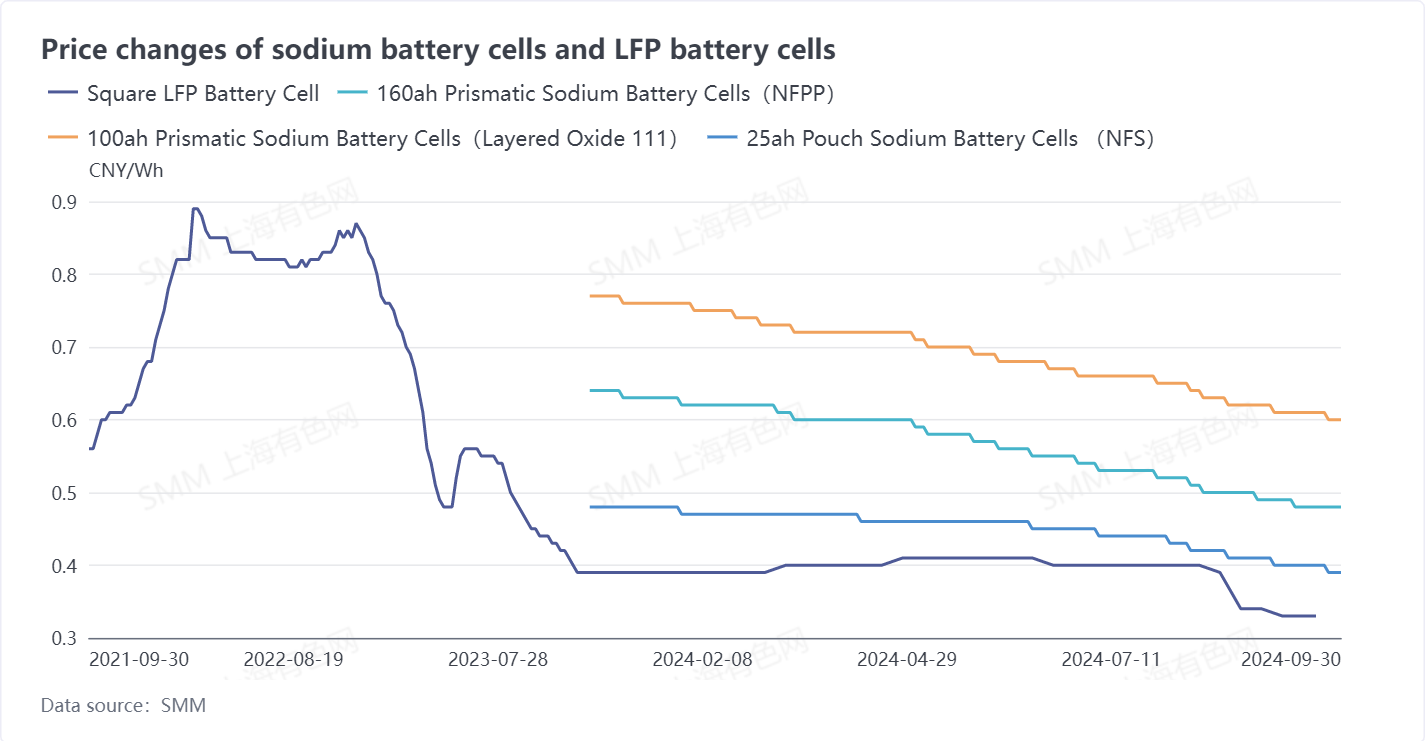


The prices of LFP battery cells have significantly decreased due to the intense price war in the market. LFP battery cell prices have dropped to around 0.3 yuan/Wh. In some markets, transaction prices have even fallen below 0.3 yuan/Wh.

Since the sodium battery cell market has not yet expanded on a large scale, the costs of the four main materials, including cathode and anode, remain high. Currently, the prices of sodium battery cells of different specifications are as follows: 50Ah sodium battery cells are 0.57 yuan/Wh, 100Ah sodium battery cells are 0.6 yuan/Wh, and 55Ah prismatic sodium battery cells (NFPP) are 0.44 yuan/Wh. Compared to LFP battery cells, sodium battery cell prices are still over 50% higher, making it difficult to achieve a good market outlook through price competition.

Therefore, sodium batteries need to take a different path, avoiding price wars, and instead should focus on improving their energy density, cycle life, and safety. They should fully leverage their high safety and wide temperature range characteristics, focusing on differentiated markets with profit potential.

II. Sodium Battery Raw Material Market Situation: Raw material prices remain high, and the pressure to reduce costs in the short term is still significant, leading to delays in the advancement of companies' raw material projects.

1. Basic Raw Materials: The cost proportion of the core functional raw material, battery-grade sodium carbonate, is low, generally accounting for 5% to 10% of cathode active materials. However, prices are high, with a cost reduction potential of around 50%. Current prices range from 5,000 to 7,000 yuan, with the main price around 5,000 yuan. Prices vary due to different processes used by companies.
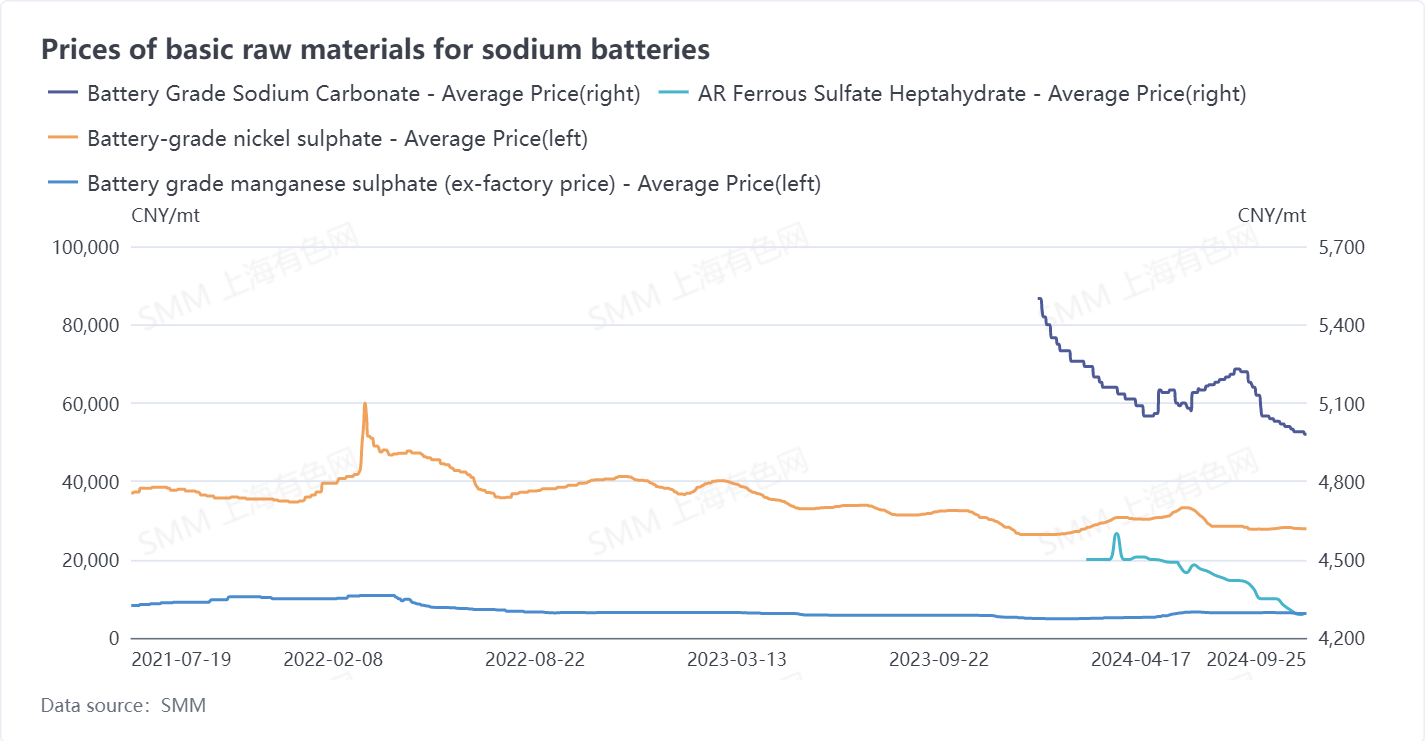
The important raw materials for sodium-ion batteries—battery-grade nickel sulphate and battery-grade manganese sulphate—hold a position equivalent to the main raw materials of ternary lithium batteries, accounting for a significant proportion of the cost in the sodium-ion layered oxide route. In the short term, their prices are unlikely to see a substantial decrease. The price of the precursor iron phosphate in the polyanion NFPP route remains relatively stable; although battery-grade sodium carbonate and battery-grade ferrous sulphate account for a relatively small proportion of the total cost of sodium-ion batteries, their prices remain high, necessitating a rapid reduction in costs.

2. Sodium battery cathode price: slowly declining.
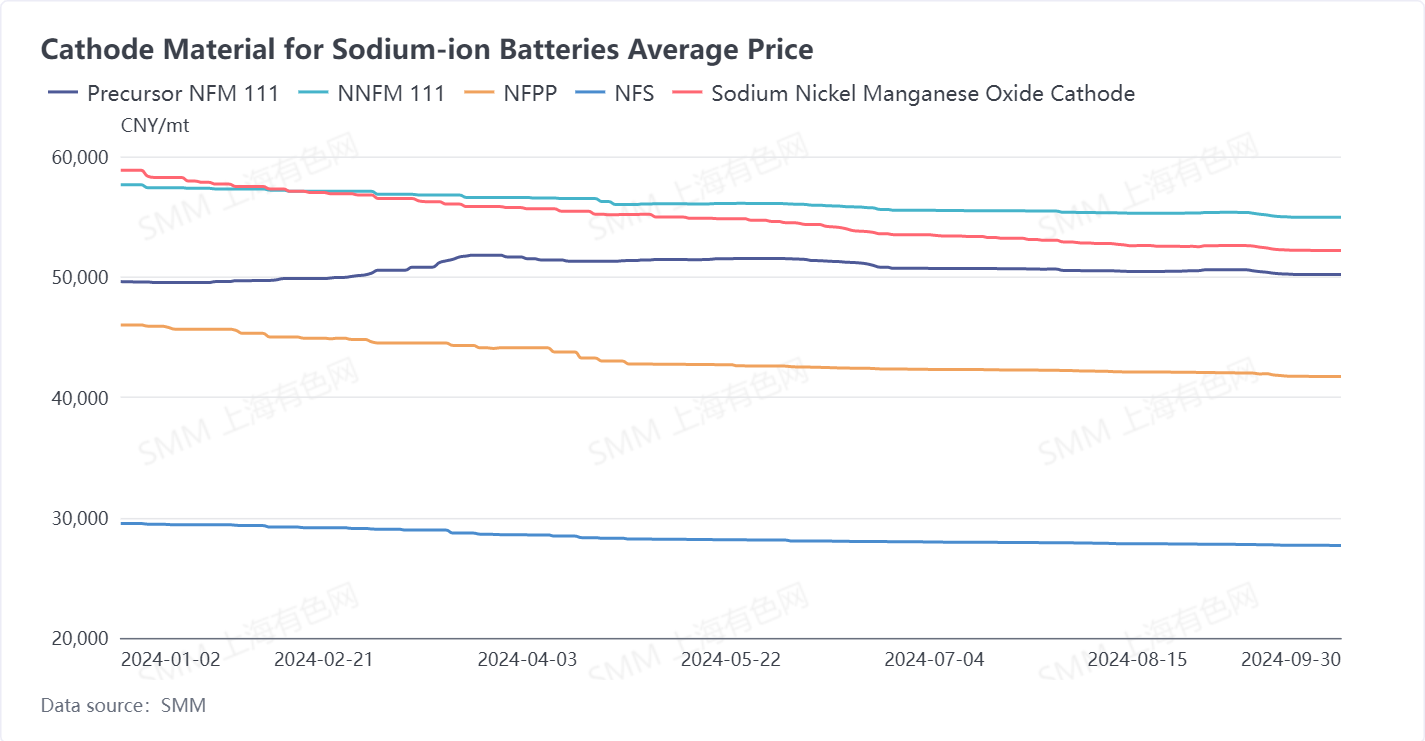
The price of NNFM 111 cathode active materials is 55,104 yuan/mt, and the price of sodium nickel manganese oxide is 523.54 million yuan/mt. The price of NFPP cathode active materials is 41,847 yuan/mt. The price of NFS cathode active materials is 277.23 million yuan/mt.

2. Sodium-ion anode: The most commonly used in the market are energy storage and small power hard carbon anodes. Except for the imported product Kureha, which has a higher anode price of 120,000 yuan/mt, other domestic anodes range between 30,000 and 50,000 yuan.
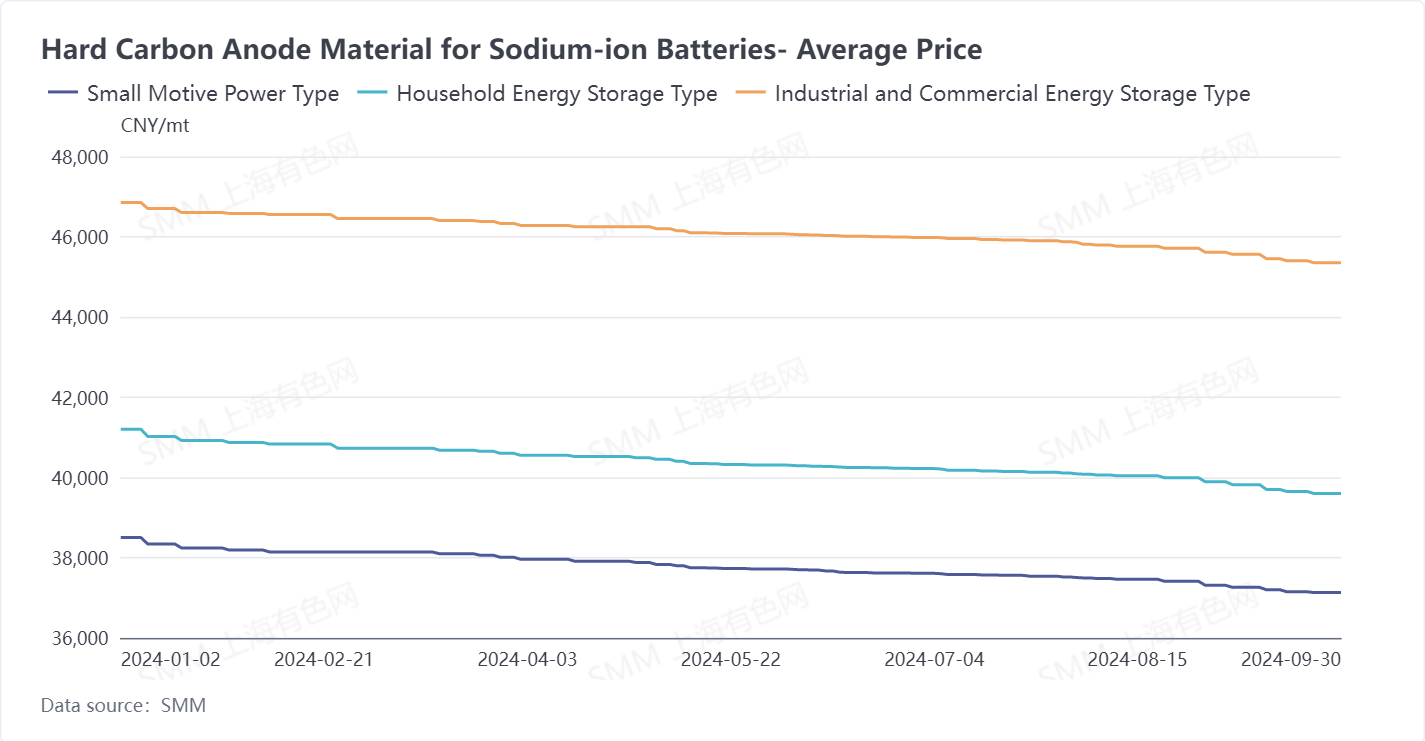


In the September market, the shipments were mostly of hard carbon anodes (small power type) priced at 37,198 yuan/mt, hard carbon anodes (household energy storage type) priced at 39,714 yuan/mt, and sodium-ion battery hard carbon anodes (industrial and commercial energy storage type) priced at 45,459 yuan/mt.

Additionally, the price of imported Kuraray hard carbon anodes remained firm at 120,000 yuan/mt.

3. Sodium battery cell price changes: market trends, prices are declining.
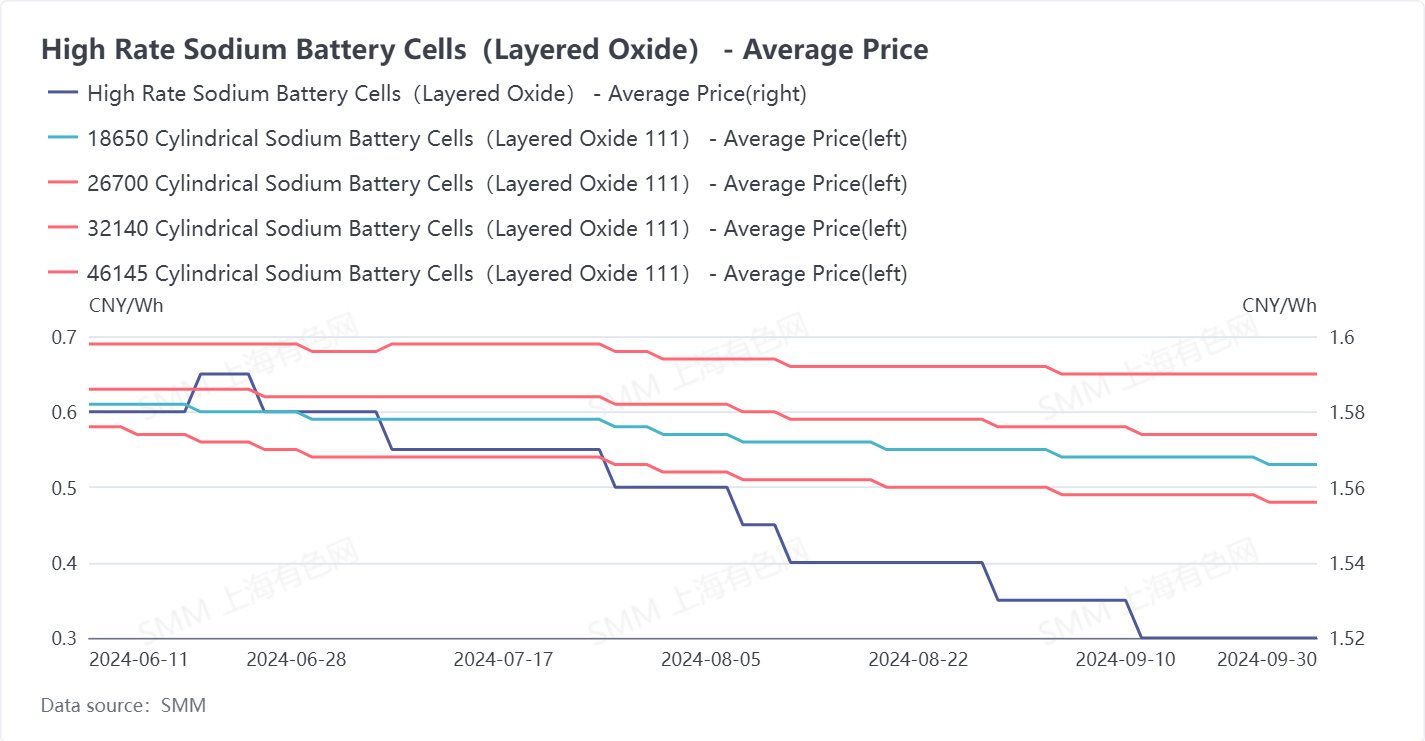
Overall, in Q4 2024, the market is expected to see an increase, technological breakthroughs, and project implementations. Based on the current market progress, this increase is below expectations, and many companies may initiate sodium battery projects in Q4, bringing some demand.

Market demand growth: Energy storage demonstration projects drive the sodium battery market's activity in H2, mainly due to the promotion of energy storage demonstration projects. Many MWh projects in industrial parks are being promoted in H2. The annual demand for energy storage battery cells is expected to be about 1 GWh, indicating growing interest and acceptance of sodium battery technology. New opportunities in the NEV market: Sodium battery technology is seeking breakthroughs in small power two- and three-wheelers. This is a potential market due to the widespread use of two- and three-wheelers globally.

Cathode active materials development trend: Preferred process routes, among the three major process routes and six branches for cathode active materials, the market favors the NFPP and NFS routes. This is mainly due to their advantages of low cost, good low-temperature performance, and high safety. Despite the many advantages of the NFPP and NFS routes, their relatively low energy density may limit the application of sodium batteries in some high energy density demand scenarios.

Development of anode and electrolyte: The anode still faces pressure in terms of energy density improvement and cost reduction. This is one of the key areas where sodium battery technology needs breakthroughs to achieve wider application. The electrolyte is still mainly customized, with the main raw material sodium hexafluorophosphate remaining expensive. This may affect the overall cost and production scale of sodium batteries.

Commercialization process and market situation: Continuous market validation, various materials and battery cell products in the sodium battery industry are undergoing market sampling and validation. This is a necessary process to ensure that the products' performance and reliability meet market requirements. Commercialization still requires time: Although market activity has increased, the commercialization of sodium battery technology still requires time. Currently, materials and battery cell products are slowly being introduced to the market at a loss, with overall prices showing a stable downward trend. This indicates that the market is still in a nurturing phase, requiring more time and effort to achieve large-scale application.


Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
[Resumen de la reunión matutina sobre cobalto de SMM] Recuperación limitada de la demanda tras las vacaciones, debilitamiento del soporte de costes, precios de los materiales bajo presión
09 Oct 2026 10:31 (GMT+8)
[Resumen de la reunión matutina sobre cobalto de SMM] Recuperación limitada de la demanda tras las vacaciones, debilitamiento del soporte de costes, precios de los materiales bajo presión
Leer más
[Resumen de la reunión matutina sobre cobalto de SMM] Recuperación limitada de la demanda tras las vacaciones, debilitamiento del soporte de costes, precios de los materiales bajo presión
[Resumen de la reunión matutina sobre cobalto de SMM] Recuperación limitada de la demanda tras las vacaciones, debilitamiento del soporte de costes, precios de los materiales bajo presión
La cadena industrial del cobalto se mantuvo débil tras el feriado, con una demanda lenta y menores costos presionando los precios a la baja. El cobalto refinado se consolidó en mínimos, los operadores ampliaron los diferenciales entre precios spot y futuros, y las compras downstream siguieron siendo principalmente reposición según necesidad. Las negociaciones de productos intermedios se estancaron, con una clara brecha entre el precio mínimo de compra de 14,5 USD/lb y los precios de aceptación downstream por debajo de 13 USD/lb. Las ofertas de sulfato de cobalto se mantuvieron cerca de 60.000 yuanes/t, pero las transacciones fueron difíciles, y un menor coeficiente de materia prima debilitó aún más el soporte de costos. El cloruro de cobalto y el Co3O4 continuaron bajando gradualmente, las empresas ampliaron los recortes y suspensiones de producción, y las nuevas adquisiciones fueron insuficientes. Las ofertas líderes de polvo de cobalto cayeron a alrededor de 360.000 yuanes/t, mientras que las pequeñas y medianas empresas bajaron a 330.000–340.000 yuanes/t, con el inventario de alto precio downstream frenando las compras. Los precios de los precursores de cátodos ternarios se debilitaron, los pedidos de exportación fueron relativamente fuertes, la recuperación del programa de producción nacional fue limitada y se esperaba que los coeficientes de pedidos spot tendieran a la baja. Los materiales de cátodos ternarios se consolidaron en mínimos, los fabricantes de celdas de batería mantuvieron un inventario amplio y repusieron con cautela; el LCO estuvo presionado tanto por la caída de costos como por la débil demanda. En adelante, se debe prestar especial atención a la recuperación de los pedidos de usuarios finales, la reducción de inventarios y la sostenibilidad de la reposición.
09 Oct 2026 10:31 (GMT+8)
[SMM Resumen de la reunión matinal de cobalto y litio] Tendencias divergentes de los productos químicos de litio tras el festivo; mejora la demanda de LFP, mercado de materiales bajo presión
09 Oct 2026 10:21 (GMT+8)
[SMM Resumen de la reunión matinal de cobalto y litio] Tendencias divergentes de los productos químicos de litio tras el festivo; mejora la demanda de LFP, mercado de materiales bajo presión
Leer más
[SMM Resumen de la reunión matinal de cobalto y litio] Tendencias divergentes de los productos químicos de litio tras el festivo; mejora la demanda de LFP, mercado de materiales bajo presión
[SMM Resumen de la reunión matinal de cobalto y litio] Tendencias divergentes de los productos químicos de litio tras el festivo; mejora la demanda de LFP, mercado de materiales bajo presión
Las tendencias del mercado de materiales para baterías tras las vacaciones divergieron. Las cotizaciones del mineral de litio repuntaron ligeramente, los inventarios comerciales se redujeron y se espera que los precios del mineral se consoliden en línea con el carbonato de litio a corto plazo. Los futuros del carbonato de litio retrocedieron tras una subida rápida, cerrando en 117.300 yuanes/t, un 1,28 % menos; la producción nacional disminuyó, los inventarios intermedios se redujeron significativamente y las plantas de sal continuaron enviando principalmente bajo contratos a largo plazo. Las cotizaciones de pedidos al contado de hidróxido de litio subieron a 130.000–140.000 yuanes/t, pero las compras fueron cautelosas y las transacciones, escasas. Los productos de cobalto y el sulfato de níquel siguieron bajo presión, el soporte de costos se debilitó y la recuperación de la demanda de materiales ternarios para cátodos fue limitada. Los pedidos de LFP fueron relativamente fuertes, las líneas de producción líderes estuvieron casi a plena capacidad, los inventarios de productos terminados disminuyeron y el precio medio subió a 50.400 yuanes/t; la resistencia al aumento de precios del fosfato de hierro creció. El grafito artificial tuvo un fuerte soporte de costos, los separadores fueron impulsados por la demanda de vehículos de nueva energía, almacenamiento de energía y el adelanto de exportaciones, con un equilibrio oferta-demanda ajustado; los electrolitos subieron debido al traslado previo de costos. En el mercado de reciclaje, las consultas se recuperaron, pero las transacciones aún no repuntaron en volumen. De cara al futuro, se debe prestar atención a la sostenibilidad del reabastecimiento, la materialización de los programas de producción y los cambios en los precios de las materias primas.
09 Oct 2026 10:21 (GMT+8)
Temporada alta de septiembre-octubre para las baterías de iones de sodio en curso: la pausa por festivos no altera el equilibrio ajustado [Análisis de SMM]
08 Oct 2026 09:32 (GMT+8)
Temporada alta de septiembre-octubre para las baterías de iones de sodio en curso: la pausa por festivos no altera el equilibrio ajustado [Análisis de SMM]
Leer más
Temporada alta de septiembre-octubre para las baterías de iones de sodio en curso: la pausa por festivos no altera el equilibrio ajustado [Análisis de SMM]
[Análisis de SMM: La "temporada alta de septiembre-octubre" de las baterías de iones de sodio está en marcha: la pausa festiva no altera el equilibrio ajustado] SMM, 8 de octubre: Durante el feriado del Día Nacional, la cadena industrial de baterías de iones de sodio continuó en gran medida con el patrón previo al feriado, sin cambios significativos...
08 Oct 2026 09:32 (GMT+8)