On February 23, the Euler brand of Great Wall Automobile announced through official channels that Euler black and white cats had encountered development difficulties in the context of recent sharp increases in raw material prices and temporarily suspended orders. It is also mentioned that Euler Black Cat and White Cat have been loved by consumers after their listing, with cumulative sales reaching 173000 vehicles. At present, there are more than 20, 000 orders waiting to be delivered to users. If they continue to take orders, new orders will not be delivered until the second half of 2022.
Under the pull of hot sales, Euler black cat and white cat could have diluted the supply chain costs by virtue of their volume advantage, but the price of raw materials rose sharply at the beginning of this year, resulting in a loss of more than 10,000 yuan per Euler black cat. This is also one of the driving factors for its suspension of orders and consideration of new countermeasures at this stage.
The time has come to test the anti-risk ability of mini electric vehicles.
Recently, in the context of the widespread lack of core and less TV in the industry, mini electric vehicles such as Euler black cat and white cat, which have to temporarily stop taking orders, are not the case. As early as November last year, Changan New Energy announced that the national version of the Changan Mercedes-Benz E-Star, its mini electric car, would stop accepting orders. The owners of the cars already booked would have to wait 3-4 months to pick up their cars, while other versions of the models were scheduled to wait 2 months. The main reason behind this phenomenon is also due to insufficient supply of automotive chips, as well as insufficient factory capacity caused by power constraints and other factors in some areas, and a serious backlog of orders.
In addition to the lack of production capacity caused by lack of core and electricity, the mini electric vehicle market is also facing unprecedented cost pressure, which is also the main reason why the Euler Black Cat has lost ten thousand yuan at the present stage. Since last year, the price of lithium ore in the raw materials of power battery has soared, among which the price of lithium concentrate, battery-grade lithium carbonate and lithium hexafluorophosphate all increased more than twice last year, which will undoubtedly greatly increase the manufacturing cost of power battery. while battery suppliers have to increase battery supply prices in order to transfer cost pressure, which directly leads to a further rise in electric vehicle manufacturing costs.
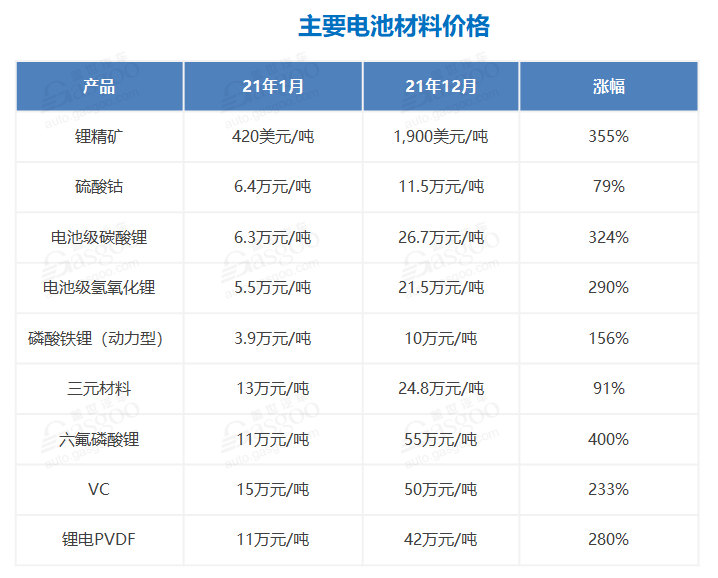
Data source: public information, analysis and collation of Gaishi Automotive Research Institute
With the soaring price of raw materials for power batteries, many car companies have announced increases in the official guidance prices of their electric vehicle products, such as Tesla, BYD, SAIC GM Wuling and so on. Among them, in the field of mini electric vehicles, Wuling Nano EV previously announced that it would raise the official guidance price by 3000 yuan. In addition, it has been reported that the national version of Changan Mercedes-Benz E-Star will raise the official guidance price by releasing new models.
Mini electric vehicles become popular with the advantage of low cost.
In terms of the current development situation of the domestic new energy vehicle market, it still presents a "dumbbell" development structure, that is, the penetration rate of new energy products in the A00 and D class vehicle market is very high, while the penetration rate of the A to C class market is relatively low. According to statistics from the China Automobile Association, last year, the domestic A00 market sold 1.253 million vehicles, of which 889000 were new energy products, with a market penetration rate of 71 per cent.
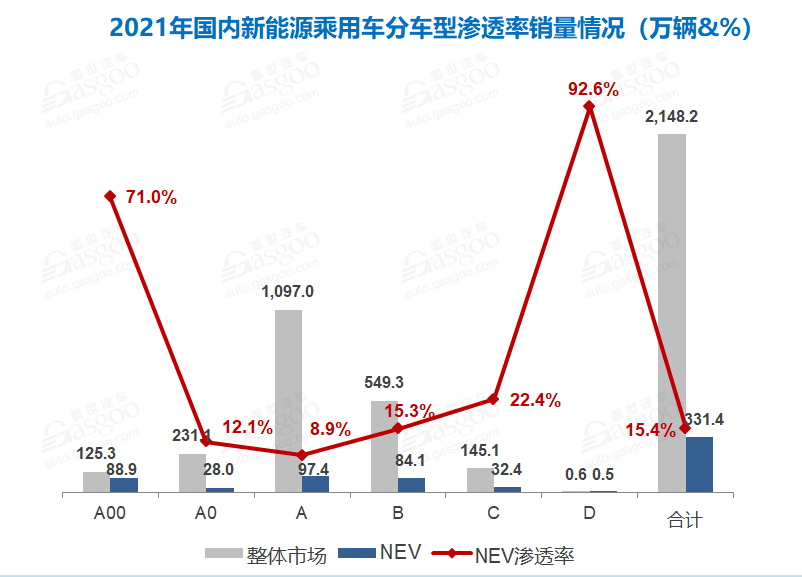
Data source: analysis and collation of China Automobile Association and Geshi Automotive Research Institute
In the A00 market, Wuling Hongguang MINIEV is the absolute main force in this field. Last year, cumulative sales of the car reached 426000, accounting for nearly half of the market share in the field of mini-electric vehicles. The hot sale of Wuling Hongguang MINIEV has led to the popularity of the mini electric vehicle market, such as Benz E-Star, Sihao E10X, Chery QQ ice cream and so on. Many "latecomers" all entered the game because they saw the hot sales of Hongguang MINIEV.
Based on this, Wuling Hongguang MINIEV is the most meaningful model to study the reasons for the popularity of the mini electric vehicle market. The car is regarded by a number of car companies as a benchmark model in the field of mini-electric vehicles, in large part because of its cost control. According to the Nikkei Chinese website, Professor Meiyi Yamamoto of Nagoya University in Japan dismantled the Hongguang MINIEV last year and found that the car was able to achieve a low price of 28800 yuan because it simplified brakes and water cooling devices, while semiconductors borrowed products for home appliances, and the main parts were provided by local suppliers in China. It can be said that Wuling Hongguang MINIEV has controlled its cost to the extreme under the condition of meeting the needs of consumers for short-distance transportation, which is the fundamental reason why it can make a profit only with a price of about 30, 000 yuan without any subsidy.
However, at this stage, with the soaring prices of raw materials for power batteries and semiconductor chips, it is more and more difficult for micro electric vehicles with low prices to make a profit. As a senior analyst in the industry said: "low cost is the fundamental reason why mini electric vehicles quickly replace low-speed electric vehicles and become popular in the vast rural areas, but in the context of the general increase in the price of raw materials, these products have to face the pressure of rising costs after consuming the original inventory of spare parts."
As the cost rises, the mini-electric vehicle may lose its price advantage.
In the face of the cost pressure, some of the mini electric vehicles in the spiral of rising cost choose to increase the price, and some choose to stop taking orders as a delaying tactic.
The industry holds two views on the impact of the increase in the price of raw materials for power batteries and chips on mini electric vehicles. One is that the increase in the price of raw materials will directly destroy the advantages of low cost and low price of mini electric vehicles. Car companies have to adjust their terminal prices in the face of cost pressure. However, mini electric vehicles are aimed at the 30,000 yuan electric vehicle market, and their potential users are more sensitive to prices. Once the price increases, To a large extent, this will prompt such users to switch to A0 or A-class products with more space, which will lead to a further decline in the market share of pure electric subcompact cars.
Another view is that the increase in the price of raw materials will have an impact on the whole electric vehicle market, and the most direct effect is that the terminal price of the product has fluctuated and the intensity of discount has been reduced. however, a small increase in the price should have little impact on consumers' intention to buy. In addition, in the long run, with the improvement of the electric vehicle industry chain and the application of all kinds of new technologies, the cost of new energy vehicles is gradually decreasing, and the future trend is that pure electric vehicles will become more and more "affordable." for mini electric vehicles, because they have replaced low-speed electric vehicles, they have become the first choice for users in third-and fourth-tier cities and rural areas, and the market volume in these areas is very large. Therefore, there is still some room for increment in the future of low-cost, low-price mini electric vehicles.
From the current sales structure of pure electric vehicles, the proportion of A00 products in the pure electric vehicle market is still high, but the proportion of A0, An and B are all increasing. According to statistics from the Federation of passengers, in January this year, the wholesale sales of Class A00 pure electric vehicles were 105000, accounting for 32% of the pure electric vehicle market. At the same time, the proportion of Class A0 was 15%, and the proportion of Class A rose to 22% of Class B, while the proportion of Class B reached 30%. From this point of view, the "dumbbell" structure of the pure electric vehicle market is improving, but at present, with the lack of cores and the continuous rise in the price of raw materials, as well as the impact of the conflict between Ukraine and Russia on the automobile industry, therefore, there are many variables in the development of miniature electric vehicles or the whole new energy vehicle market in a short period of time.