

SMM10, 10 Jun: on Oct. 9, the Nobel Prize in Chemistry was awarded to three inventors of lithium batteries, American scientist John Gudinaf (John Goodenough), American scientist Stanley Whitingham (Stanley Whittingham), and Japanese scientist Akira Yoshino. (Akira Yoshino) shared the award.
Gudinaf, 97, is recognized as the "father of lithium batteries". His invention makes lithium batteries smaller, larger and more stable, making them commercially available and starting the process of portable electronic devices.
Gudinaf is a famous solid physicist. The 97-year-old Gudinaf also set a new age record for winning the Nobel Prize. At present, Gudinaf is still a professor in the Department of Mechanical Engineering at the University of Texas at Austin. He is also the inventor of lithium cobalt, lithium manganate and lithium iron phosphate cathode materials. By studying the relationship between chemistry, structure and the properties of solid electrons and ions, new materials are designed to solve material science problems.
British-American chemist Whitingham is currently a professor of chemistry and director of the Institute of Materials and Materials Science and Engineering at the State University of New York at Binghamton University.
Professor Akira Yoshino, a Japanese chemist who invented the modern lithium-ion battery (LIB), is also a researcher at Asahi.
With the progress of science and technology, the safety of liquid lithium battery has been unable to meet the basic requirements of safe use of lithium battery, and great scientists have invented safety and more efficient solid-state lithium battery in their continuous efforts and breakthroughs. Although lithium battery technology has been very mature, it is still a relatively new field for people to use solid-state lithium battery technology. Therefore, there are many problems in the research and future application of solid-state lithium battery, although there are many problems, but solid-state lithium battery will still be the main direction of scientists in the exploration of lithium battery.
Reasons for choosing solid State Lithium Battery and bottleneck of Technical Development
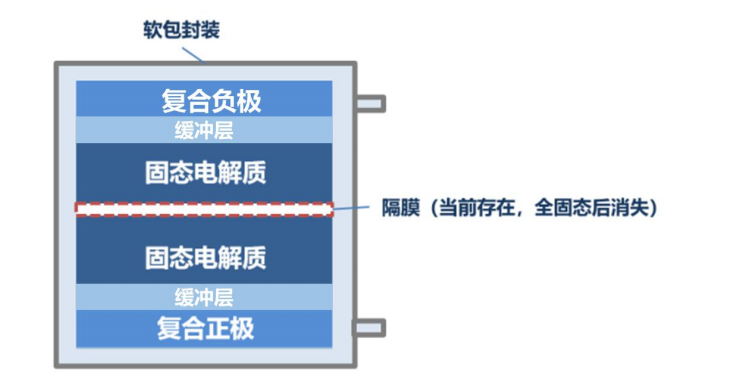
The characteristics of solid-state lithium battery determine that its use is better than the liquid lithium battery which is widely used at present.
First of all, the solid lithium battery does not burn, which can eliminate the hidden danger of safety. The solid lithium battery is a lithium ion battery with solid electrolyte, which is non-flammable and greatly improves the safety of the battery. Solid-state lithium battery has the characteristics of non-flammability, high temperature resistance, non-corrosion and non-volatilization, which avoids the phenomena of electrolyte leakage and electrode short circuit in traditional lithium-ion battery, reduces the sensitivity of battery pack to temperature and eliminates the hidden danger of safety.
Secondly, solid-state lithium batteries are compatible with high-capacity positive and negative electrodes, promoting a great leap in energy density. Solid-state lithium batteries have a wider electrochemical window and are easier to carry high-voltage cathode materials. The electrochemical window of solid electrolyte is wider and can reach 5 V, which is more suitable for high voltage electrode materials. At the same time, it is compatible with the metal lithium negative electrode, raising the upper limit of energy density, the gram capacity of lithium metal is 3860mAh, about 10 times that of graphite (372mAh/g). Lithium metal is the lowest electrochemical potential material in nature, which is-3.04V. Let lithium metal become the "final negative electrode" after graphite and silicon negative electrode.
Finally, the solid-state lithium battery has a lightweight battery system, and the solid-state lithium battery core does not contain liquid, which can be assembled first in series and parallel and then assembled, which reduces the material used for assembling the shell, and the design of PACK is greatly simplified. After the solid-state lithium battery reduces the weight of the system, the energy density will also be further increased.
At the same time, there are many technical bottlenecks in solid-state lithium battery, which is the key to its large-scale application. The main reason is that many electrolyte performance indexes can not meet the requirements of commercial application.
The low ionic conductivity of solid electrolytes is one of the main bottlenecks hindering its commercial application. The ionic conductivity directly affects the overall impedance and rate performance of the battery, and the conductivity of polymer solid electrolyte is generally low.
Secondly, similar to organic electrolytes, polymer electrolytes also have the problem of simultaneous conduction of double ions (anions and cations in lithium salt). Ionic conductivity is not entirely contributed by the migration of lithium ions. The key to the cycle and rate performance of the battery is the amount of lithium ion migration.
Thirdly, the poor contact between solid electrode and solid electrolyte and high interface impedance is one of the main bottlenecks restricting the cycle performance of solid lithium battery. At present, the contact impedance of the solid / solid interface between the solid electrolyte and the solid electrode is more than 10 times of the bulk impedance of the hydrolysate, which seriously affects the ion transmission and leads to the poor cycle life and rate performance of the battery.
Finally, the mechanical properties of inorganic solid electrolytes are mainly aimed at inorganic solid electrolytes, most of which belong to ceramic electrolytes, the mechanical properties are relatively poor, brittle and fragile.
Present situation and Development of solid State Lithium Battery
At present, the mass production of solid-state lithium battery is very few, and the industrialization process is still in the early stage. The only product that has achieved mass production in the field of power batteries has an energy density of only 100WH / g, which does not have a competitive advantage over traditional lithium power.
From the overseas enterprise experiments and pilot products, the energy density advantage of solid-state lithium battery has begun to highlight, significantly exceeding the existing lithium power level. In China, the basic research of solid lithium electricity started earlier. During the "sixth five-year Plan" and "Seventh five-year Plan", the Chinese Academy of Sciences listed solid lithium electricity and fast ion conductors as key topics. In addition, Peking University, China Electronic Science and Technology Group Tianjin 18 and other institutes have also established projects to study solid lithium electrolytes, and have made good progress in this field. In the future, with the gradual increase of industrial investment, the pace of product performance improvement is also expected to accelerate.
A large enterprise that preempts the tuyere of a solid-state battery
Ganfeng Lithium Industry: in 2017, Ganfeng Lithium Industry formally cut into the solid-state lithium battery plate through the introduction of Xu Xiaoxiong team of Ningbo Institute of Materials, Chinese Academy of Sciences. In December 2017, Ganfeng Lithium Industry announced that it plans to invest no more than 250 million yuan to build the first generation of pilot production line for solid-state lithium battery research and development, with a scale of more than 100 gigawatt hours and 600 million watt-hour power battery production line will focus on matching with solid-state lithium battery in the future. On July 30, 2018, Zhejiang Feng Lithium, a wholly owned subsidiary of the company, completed the first phase of the performance evaluation index of the first generation of solid lithium battery research and development test line project.
Ningde era: the Ningde era has mainly carried out related research and development work in the direction of polymer and sulfide-based solid-state lithium batteries, and has made preliminary progress. Ningde era, based on the improvement of the conductivity and processing performance of the battery, designed and manufactured a polymer cell with a capacity of 325 Ma, with a cycle of more than 300 laps and a capacity retention rate of 82%. In the aspect of sulfide solid lithium battery, in Ningde era, the interface compatibility between cathode and solid electrolyte was improved by surface modification and coating modification, and the mixing process was developed to improve the stability of sulfide in the air. it is possible to reduce the manufacturing cost of the battery.
Jiawei shares: the company accelerated the production of solid-state fast rechargeable battery products. In November 2016, Jiawei held the world's first solid-state lithium battery and fast lithium battery product launch in Shanghai to demonstrate the performance of the new product. In April 2018, Jiawei Longneng solid State Energy Storage Technology Company, a holding subsidiary of Jiawei, was officially put into production for trial operation. The company's products have high safety performance, in the exhibition was deeply pierced by three nails, can still work normally.
Tianqi Lithium: the company's wholly owned subsidiary in Hong Kong used its own capital of US $12.5 million to participate in the financing of "round C preferred shares" for SolidEnergy System, a solid-state lithium battery company, with a stake of 11.72 per cent.
"for more information, please click on the SMM Cobalt Lithium New Energy column.
Shanghai colored net cobalt lithium new energy industry research team, combined with SMM independent research first-hand data, provide analysis and views on hot events at home and abroad, analyze and judge the market trend, covering nickel, cobalt, lithium, ternary materials and other plates in the cobalt lithium industry chain. Introduction of SMM Cobalt Lithium New Energy Industry chain monthly report
Introduce: in the form of monthly report, the SMM cobalt lithium new energy research group industry chain information intuitively presents, the information is accurate, the professional degree is high, the data chart is detailed, has the forward-looking and the exclusive point of view. Cobalt lithium and related categories of price, output, import and export, upstream and downstream enterprises, new energy vehicle data and other important data are investigated and analyzed by SMM Cobalt Lithium Research team. Rich in instant information, in addition to monthly reports, analysts and reporting customers timely exchange the latest industry developments, seize the latest hot spots in the market.
"Click to sign up for the Lithium Power Industry chain Summit

Scan QR code and apply to join SMM metal exchange group, please indicate company + name + main business



