

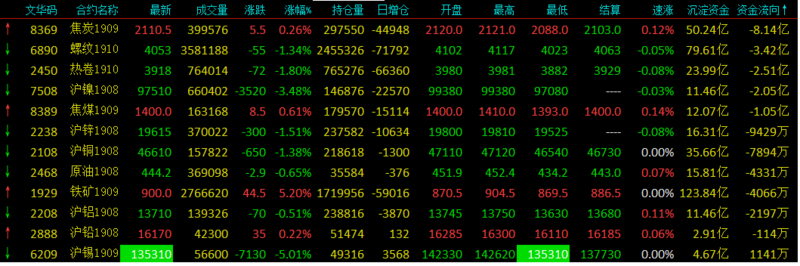
SMM7, 2 July: during the day of trading on July 2, most of the non-ferrous metals fell, and by the end of the day, Shanghai Tin closed down 5.01% (by the limit), closing at 135310 yuan / ton, Shanghai nickel closing down 3.48% at 97510 yuan / ton, Shanghai zinc closing down 1.51% at 19615 yuan / ton, Shanghai copper closing down 1.38% at 46610 yuan / ton, Shanghai aluminum closing down 0.51%, closing 13710 yuan / ton, Shanghai lead only fluttering red, closing up 0.22%. The charge is 16170 yuan per ton. The black system is polar today, with hot rolls down nearly 1.8%, threads down nearly 1.3%, coke up nearly 0.3%, coking coal up nearly 0.6%, and iron ore up nearly 5.2%.
Among them, Shanghai tin opened low, dived rapidly in the afternoon, and hit the limit for the first time at about 13:50. Although there were several attempts to recover, it was still struggling at the limit line. Shanghai nickel opened the same low opening and recovered slightly in the afternoon, but it was still difficult to recover the lost ground, with the lowest point in intraday trading reaching 97080 yuan per ton, the lowest since June 13.
Capital flow:
Brief comments on SMM:
Copper: copper prices in the G20 macro positive after the start of the decline pattern, but today's decline seems to stop, Shanghai copper center of gravity hovering around 46600 yuan / ton. SMM believes that after the current macro trade is good digestion, there is no short signal release, copper prices hovered above the 46600 yuan / ton gap formed in the first two weeks, waiting for macro guidance. At present, the basic copper market is still not optimistic, the trend of domestic consumption off-season pre-purchase is becoming more and more obvious, superimposed in June smelter centralized maintenance basically ended and smelter new expansion capacity put in, last week SHFE copper inventory increased by 11272 tons compared with the previous month, the domestic cumulative warehouse is prominent; SMM downstream research also shows that consumption weakens ahead of schedule. The situation of the raw material side, which has attracted much attention from the market, has not yet had an impact on the production of the smelter, although frequent foreign mining accidents have led to a continuous decline in copper concentrate TC and crude copper processing fees, and the supply of scrap copper has also been reduced due to weak prices. The market is nervous about the rapid contraction of the raw material supply side, but the refinery side has not been greatly affected. Therefore, SMM believes that the current macro, fundamentals to promote the upward motivation of copper prices have become weaker, the market every high short in line with the current operational logic, the near future is expected to Shanghai copper downward compensation 46600 yuan / ton gap position.
Aluminum: the recent electrolytic aluminum consumption into the seasonal off-season, as of Monday SMM statistics domestic electrolytic aluminum social inventory of 1.041 million tons, down 10000 tons from last Thursday, weekly storage from 60-70, 000 tons in April gradually narrowed to the current 10, 000 tons, electrolytic aluminum storage speed significantly slowed down. At the same time, alumina prices continue to fall, causing costs to move down. As of today, the weighted average price of alumina in SMM five places is 2758 yuan / ton, down 320 yuan / ton from 3078 yuan / ton in mid-June, and the unilateral weakness of aluminum is also expected. However, it is worth noting that, first, the decline of alumina is mostly expected, falling to about 2600 of the marginal production capacity will have to cut production; second, in the absence of profit stimulation, the rise of electrolytic aluminum supply is very slow, at the same time, there are new production cuts (Liaoning region); Third, based on our judgment of the obvious increase in orders for construction aluminum profiles this year, there is a high probability that electrolytic aluminum will accelerate to storage again in September, and we can try 09 contracts around 13500 yuan / ton.
Nickel: nickel prices gradually return to the supply side, supply looks at the pure nickel inventory has increased significantly for several weeks in a row, and although the spot has improved due to the sharp decline in the disk, the boost to the removal of pure nickel is limited; nickel pig iron continues to be released as expected, and a large amount of new capacity is still under construction at a later stage, and supply is still under pressure in the future. On the demand side: although stainless steel has a decline in storage in the near future, but the overall inventory is still high, stainless steel is in the off-season consumption, the demand is weak; the domestic recession policy of new energy has a significant impact on ternary precursors and nickel sulfate plants, and the demand for pure nickel has decreased significantly. Therefore, from the supply side to continue to look at the weak nickel price, the lower boundary temporarily look at 9-94000, this range is the domestic high-cost EF and RKEF cost line, after the nickel price falls near this position, the change of nickel pig iron supply may support the nickel price to a certain extent. "[SMM News] Shanghai nickel fell more than 3 per cent in early trading and largely fled the build-up of nickel stocks in recent days.
< updating! Please look forward to it! >
Click to sign up for this summit
"Click to sign up for this summit
Scan QR code and apply to join SMM metal exchange group, please indicate company + name + main business



