

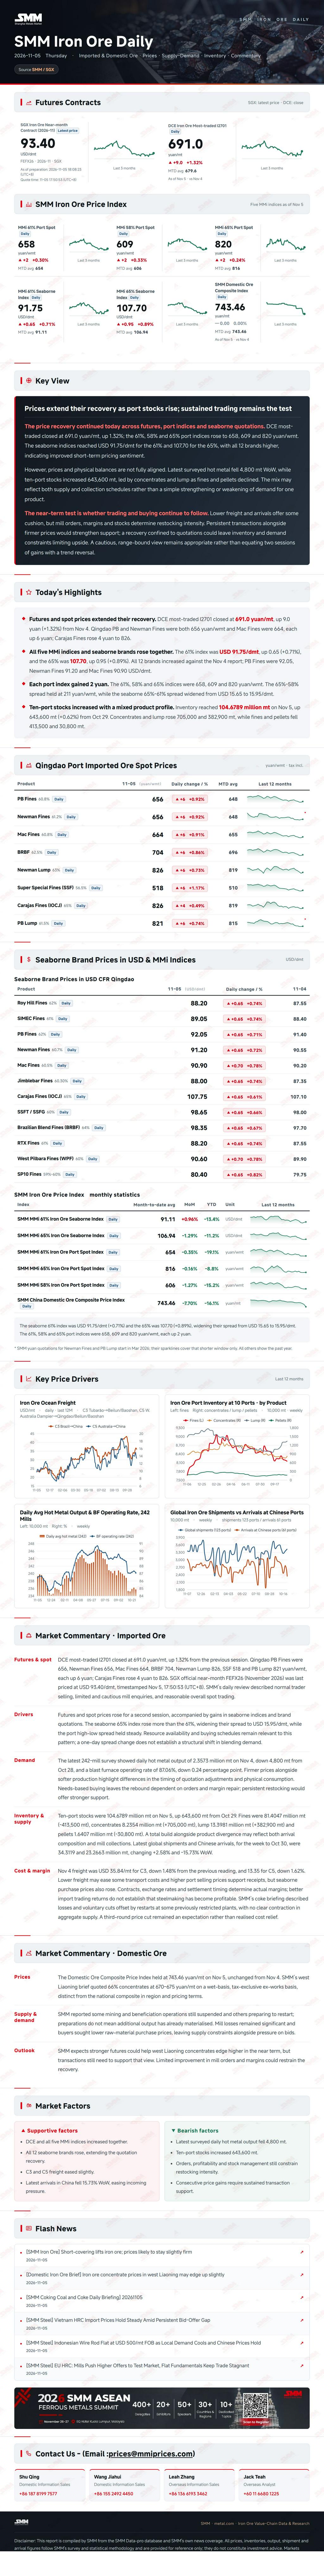
MMi Daily Iron Ore Report (november 5)
Iron ore futures were weaker today. The DCE most-traded contract settled at 669 yuan/mt, down 1.83% from the previous session. Qingdao port spot prices fell by around 9–15 yuan/mt on average. Traders were reluctant to offer, while mill inquiries were reasonable.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.
For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
1 hour ago
[SMM Iron Ore] Short-covering lifts iron ore; prices likely to stay slightly firm
Read More
[SMM Iron Ore] Short-covering lifts iron ore; prices likely to stay slightly firm
1 hour ago
6 hours ago
[Nippon Steel Successfully Produces DRI Using 100% Hydrogen]
Read More
[Nippon Steel Successfully Produces DRI Using 100% Hydrogen]
Nippon Steel has successfully produced over 100 million tonnes of Direct Reduced Iron (DRI) using 100% hydrogen as the reducing agent in a pilot-scale shaft furnace. The test involved more than 300 hours of continuous operation using lower-grade iron ore, marking progress towards commercialising hydrogen-based ironmaking technology. The company plans to continue testing and develop scale-up technologies from FY2027 with the aim of establishing the technology by around 2040. The development is relevant for India's steel sector as hydrogen-based DRI technology could help reduce carbon emissions from ironmaking and improve the use of lower-grade iron ore, supporting the industry's long-term green steel transition.
6 hours ago

8 hours ago
[Warrior Met Coal FY2026 Q3 net income up 32% YoY to $49 million]
Read More
[Warrior Met Coal FY2026 Q3 net income up 32% YoY to $49 million]
US metallurgical coal producer Warrior Met Coal reported third-quarter fiscal 2026 net income of $49 million, up 32% YoY from $37 million a year earlier. Total revenue rose 54% YoY to $508 million, mainly driven by a 48% YoY increase in sales volumes to 3.5 million short tons as the Blue Creek mine ramped up ahead of schedule. Adjusted EBITDA rose 76% YoY to $124 million, with margin expanding to 24% from 22%. Average net selling price was $144 per short ton, up 6% YoY, while cash costs rose 4% YoY to $105 per short ton. High Vol A coal accounted for 68% of sales volumes, up 25 percentage points YoY. Mine 7 output fell 22% QoQ due to difficult geological conditions and a longwall move, adding about $11 per ton to overall cash costs. The PLV FOB Australia index averaged $225 per short ton in the quarter, up $9 QoQ. Gross price realization fell to 66% from 83% a year earlier, attributed to freight and demurrage rates that were 22% and 44% higher YoY respectively, and to a one-time monetization of surplus inventories at fixed prices, which generated $49 million in cash but reduced adjusted EBITDA by about $27 million versus index-linked pricing. The board declared a $2 per share special dividend. Liquidity rose to $578 million, and free cash flow after capital expenditure was $139 million. The company reaffirmed its full-year guidance; a decision on expanding Blue Creek's second longwall depends on market absorption capacity. Demurrage and freight costs are expected to remain elevated through year-end. [SMM Iron Ore]
8 hours ago
Related News
[SMM Iron Ore] Short-covering lifts iron ore; prices likely to stay slightly firm
Nov 05, 2026 17:12 (GMT+8)
[Nippon Steel Successfully Produces DRI Using 100% Hydrogen]
Nov 05, 2026 12:26 (GMT+8)
[Warrior Met Coal FY2026 Q3 net income up 32% YoY to $49 million]
Nov 05, 2026 10:26 (GMT+8)

[India's coking coal import dependence on Australia falls to 54%]
Nov 05, 2026 10:26 (GMT+8)