Nov 5 news:
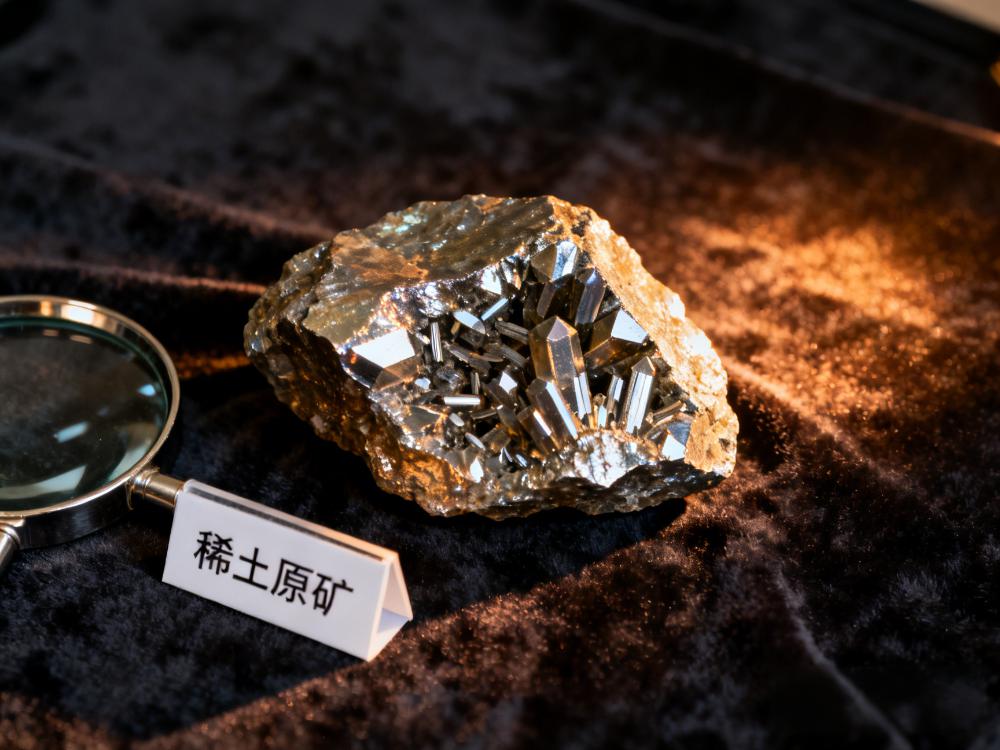
Rare earth ore:
This week, the mainstream reference price for rare earth carbonate initially followed the oxide side lower, then rebounded today to 57,500-57,800 yuan/mt. During the price decline phase, separation plants generally slowed raw material purchases and prioritized consuming existing inventory. Although miners' willingness to sell increased, the extent of price concessions was limited, and the gap between bid and ask quotes remained unresolved, with few actual deals concluded. Rare earth chloride flakes held steady all week at 63,000-64,000 yuan/mt, not following adjustments in related products, as separation plants made small restocking purchases according to production schedules, with bulk negotiations absent throughout. Medium-yttrium, europium-rich ore similarly rebounded to 240,000-241,000 yuan/mt after dipping, with mine-side quotes easing mid-week in line with oxide prices, buyers pushing for lower prices while sellers held prices firm, and transactions released sporadically. Monazite held steady at 41,000-45,000 yuan/mt, with no new changes on either the supply or demand side, inquiries remaining low, and prices lacking direction.
Rare earth oxides:
This week, lanthanum oxide prices held steady at 5,500-6,000 yuan/mt and cerium oxide prices held steady at 13,800-14,200 yuan/mt. Quotes for both products were unchanged all week, downstream buying interest was sluggish, and shipments were mostly long-term contract deliveries and scattered small orders, lacking independent momentum. As of today, Pr-Nd oxide prices moved lower before rebounding: early in the week, prices consolidated in a narrow range, then accelerated downward mid-week to a weekly low of 697,000-700,000 yuan/mt, dragged by continued weakness in futures. Suppliers briefly suspended quotes in large numbers, and metal plants, uncertain about the raw material outlook, shifted to negotiating purchases order by order and only restocking based on current orders. Today, quotes were quickly revised upward, rebounding sharply to 710,000-714,000 yuan/mt, reclaiming the 710,000 yuan/mt level. Given that inquiries were sluggish for most of the week and actual transactions were sparse, the sustainability of this rebound still lacks confirmation from the trading side.
On the medium-heavy rare earth side, dysprosium oxide prices saw the lower end of the range move up to 1.43-1.44 million yuan/mt. Dysprosium products remained relatively firm within the medium-heavy rare earth segment, briefly becoming the only rising product during the week. After prices stabilized, some metal plants resumed routine inquiries, but bid prices still fell short of suppliers' expectations, limiting actual deal progress. Terbium oxide prices continued to decline to 6.25-6.3 million yuan/mt, edging down after a prolonged consolidation early in the week as weakness spread, with low market attention and sparse inquiries and transactions. Gadolinium oxide prices continued to decline to 168,000-172,000 yuan/mt, shifting from stable to weakening in tandem with the Pr-Nd chain, as buyer wait-and-see sentiment deepened and trading was sluggish. Holmium oxide prices held steady at 656,000-660,000 yuan/mt, with no adjustment all week and actual transactions still insufficient. Erbium oxide prices declined to 700,000-720,000 yuan/mt, as profit-taking at high levels early in the week pushed the quote center lower, and with no new drivers thereafter, buyers became more cautious in purchasing. Yttrium oxide (5N) prices held steady at 61,000-63,000 yuan/mt, and yttrium oxide (3N) prices held steady at 35,000-37,000 yuan/mt, consolidating after last week's rise, with limited demand support and price gains lacking transaction backing.
Rare earth metals:
On the light rare earth side, cerium metal market prices held steady this week, with supplier quotes stable at 28,000-28,500 yuan/mt. Pr-Nd alloy prices overall fell first and then rose this week, with the center edging slightly lower. Early in the week, quotes stabilized and were basically flat with the previous period, as suppliers narrowed their room for price concessions. Mid-week, dragged by a sharp decline in raw material prices, cost support weakened significantly, and metal producers cut quotes sharply, with single-day declines hitting recent highs. Some suppliers suspended quotes and waited to gauge market inquiries. The decline then continued, with quotes edging slightly lower. Near the weekend, driven by rising raw material costs and downstream magnetic material restocking, metal prices rebounded sharply, recovering part of the week's losses. As of today, supplier quotes were adjusted to 858,000-865,000 yuan/mt. Downstream inquiries remained sluggish overall, with strong wait-and-see sentiment, limited actual transactions, and trading volume not yet expanding alongside the price rebound.
On the medium-heavy rare earth side, dysprosium-iron alloy closed at 1.38-1.4 million yuan/mt. Prices rose this week and then held steady, mainly driven by the lagged pass-through of earlier raw material cost increases. Metal producers raised quotes independently, moving against the overall sector direction, and quotes remained unchanged for the rest of the week. However, downstream inquiries were stable, with transactions dominated by small rigid-demand orders. Terbium metal prices declined continuously this week, closing at 7.7-7.75 million yuan/mt, mainly due to persistent difficulty in closing high-priced deals, compounded by weakening cost support. Metal producers cut quotes repeatedly, with declines larger than those in raw materials, and actual market transactions remained scarce. Gadolinium-iron alloy prices weakened slightly this week, with supplier quotes adjusted to 163,000-165,000 yuan/mt, mainly affected by weak market transactions and the spillover from Pr-Nd weakness. Late in the week, the decline slowed and quotes tended to stabilize, with fewer market inquiries and sluggish actual transactions. Holmium-iron alloy prices held steady this week, closing at 655,000-660,000 yuan/mt, with no significant quote adjustments all week. Downstream inquiry and purchasing attitudes remained wait-and-see, and actual transaction follow-through was limited.
NdFeB blanks:
Currently, NdFeB blank N38 (Ce) closed at 193-203 yuan/kg; NdFeB blank 38M closed at 228-248 yuan/kg; NdFeB blank 40H closed at 243-253 yuan/kg; NdFeB blank 45SH (Ce) closed at 293-313 yuan/kg.
This week, NdFeB prices fell first and then rose, with the core reason being that raw material prices fell first and then rose, driving NdFeB spot order quotes to fall first and then rise. However, constrained by motor plant inquiry prices and limited end-use demand support, the increase was notably smaller than the decline. As a result, on a weekly average price basis, NdFeB prices showed a downward trend. In terms of trading, NdFeB market trading volume was average this week, due to the impact of the macroeconomic environment, limited end-use demand, and limited demand transmitted upstream. On the other hand, raw material prices fluctuated significantly in the short term, prompting downstream players to generally adopt a low-inventory model, making it difficult to generate substantial restocking demand, ultimately resulting in average market trading volume.
NdFeB scrap:
This week, Pr-Nd recycled from NdFeB scrap closed at 705-710 yuan/kg; dysprosium recycled from NdFeB scrap closed at 1,230-1,250 yuan/kg; terbium recycled from NdFeB scrap closed at 5,600-5,800 yuan/kg.
This week, scrap market prices overall showed a decline-then-rise trend, mainly driven by the initial decline and subsequent rebound in Pr-Nd oxide prices. Early in the week, Pr-Nd oxide prices continued to fall, and recycling enterprises lowered their purchase quotes accordingly. Scrap suppliers showed strong wait-and-see sentiment and limited willingness to sell at low prices, resulting in weak actual transactions. Mid-week, the decline in Pr-Nd oxide prices narrowed somewhat, and recycling enterprises continued to lower purchase quotes slightly, with Pr-Nd scrap prices following lower. Subsequently, the single-day decline in Pr-Nd oxide prices widened significantly, and recycling enterprises cut purchase quotes repeatedly, pushing Pr-Nd scrap prices further down to a weekly low. Suppliers remained largely on the sidelines, and market trading sentiment was sluggish. Near the weekend, driven by macro factors, Pr-Nd oxide prices rebounded sharply, and recycling enterprises raised purchase quotes accordingly, leading to a recovery in Pr-Nd scrap prices. However, trading volume in this round of gains was limited, as downstream magnetic material plants and motor plants generally maintained a wait-and-see attitude, and actual transactions in the scrap segment remained weak.