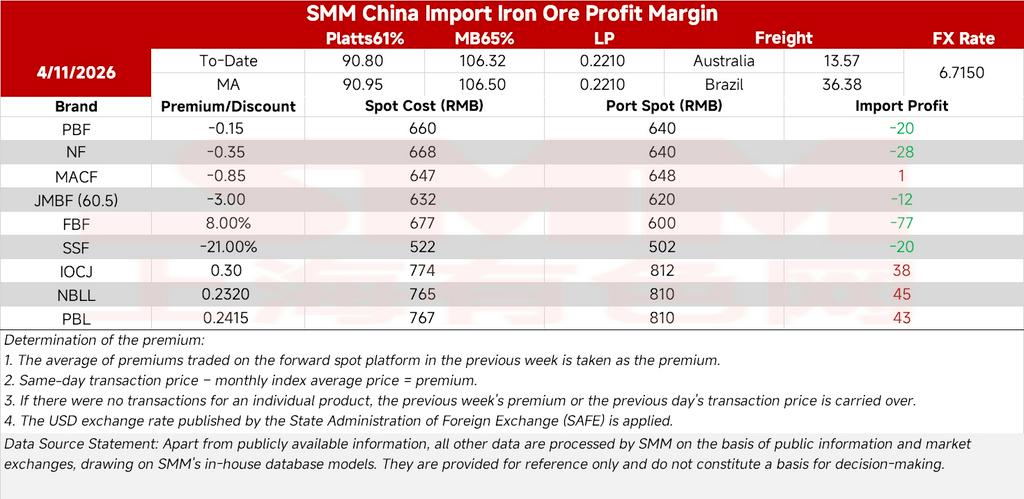
The average imported iron ore margin turned negative in the latest period, falling from 2.19 yuan/mt to -3.09 yuan/mt, weighed down mainly by lower port spot prices.
On the supply side, SMM data showed total iron ore output from the big four miners at 292.5 million mt in the third quarter of 2026, down 1% quarter-on-quarter and 2% year-on-year. Their combined shipments totalled 292.72 million mt, broadly flat quarter-on-quarter and up 1% year-on-year. None of the big four revised its full-year production guidance, and their shipments may stay high in the fourth quarter, keeping supply pressure heavy.
On the demand side, SMM data showed hot metal output lost to blast furnace maintenance at 1.6983 million mt this week (October 31-November 6), down 57,900 mt week-on-week. Next week (November 7-13), the figure is expected to fall a further 13,300 mt to 1.685 million mt. Although maintenance losses are shrinking, the decline is modest. With steel mills still loss-making and environmental curbs in place in northern China, room for a hot metal recovery is limited. Shipments remain high while demand lacks clear growth, and futures and spot prices both weakened. Iron ore prices are likely to remain range-bound with a weaker bias in the short term. News on long-term contract negotiations and the progress of environmental curbs in northern China are worth watching. With freight rates easing gradually, the import margin is likely to hover between small profits and small losses in the short term.