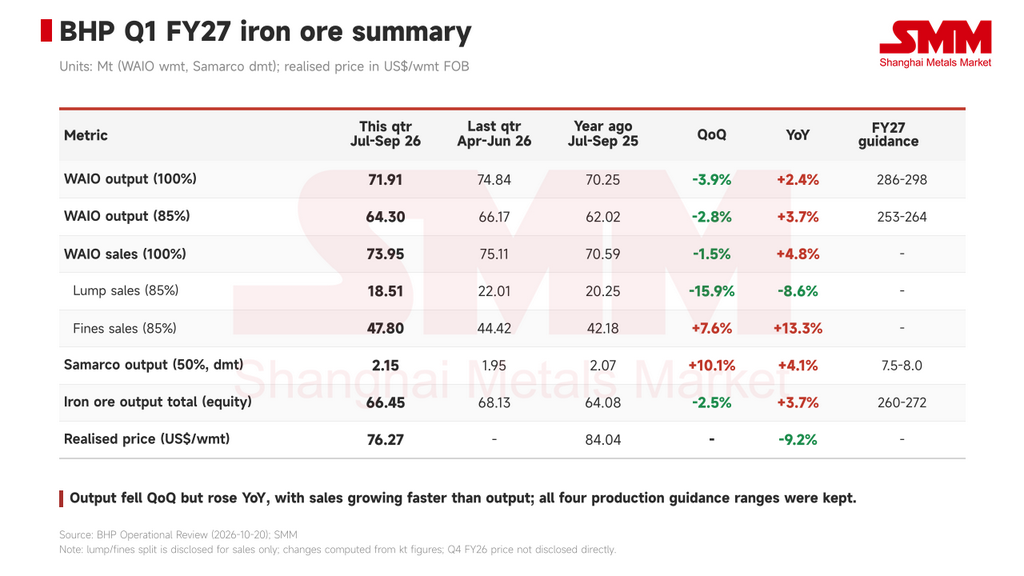
On 20 October, BHP released its operational review for the quarter ended 30 September 2026, the first quarter of its 2027 financial year (July-September 2026). On a 100% basis, Western Australia Iron Ore (WAIO) produced 71.91 Mt, up 2.4% year on year, and full-year production guidance was kept at 286-298 Mt. Lump accounted for 27.9% of WAIO sales, 4.5 percentage points lower than a year earlier, while fines sales rose 13.3%.
01 Production and sales overview
Output: WAIO produced 71.91 Mt on a 100% basis, down 3.9% quarter on quarter and up 2.4% year on year. On BHP's 85% equity basis output was 64.30 Mt, up 4%. BHP said the quarter carried significant planned maintenance, yet mine, rail and port performance was strong, with Q1 records at both the mine and the port. BHP attributed the sequential decline to planned maintenance, including the rebuild of Car Dumper 4 at Port Hedland.
Sales: WAIO sales were 73.95 Mt on a 100% basis, down 1.5% quarter on quarter and up 4.8% year on year.
Guidance: WAIO production guidance remains 286-298 Mt (100% basis; 253-264 Mt on an equity basis). Group iron ore output including Samarco was 66.45 Mt on an equity basis, up 4%, with full-year guidance unchanged at 260-272 Mt.
02 Joint ventures and product mix
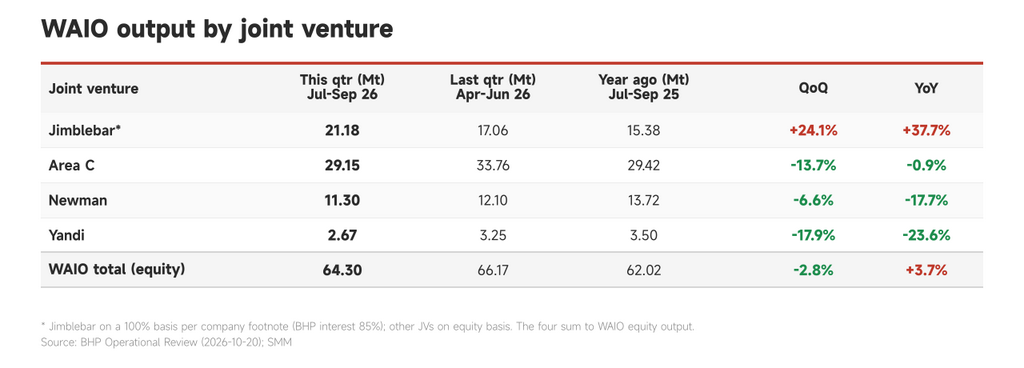
By joint venture: Growth came mainly from Jimblebar, while the four joint ventures diverged.
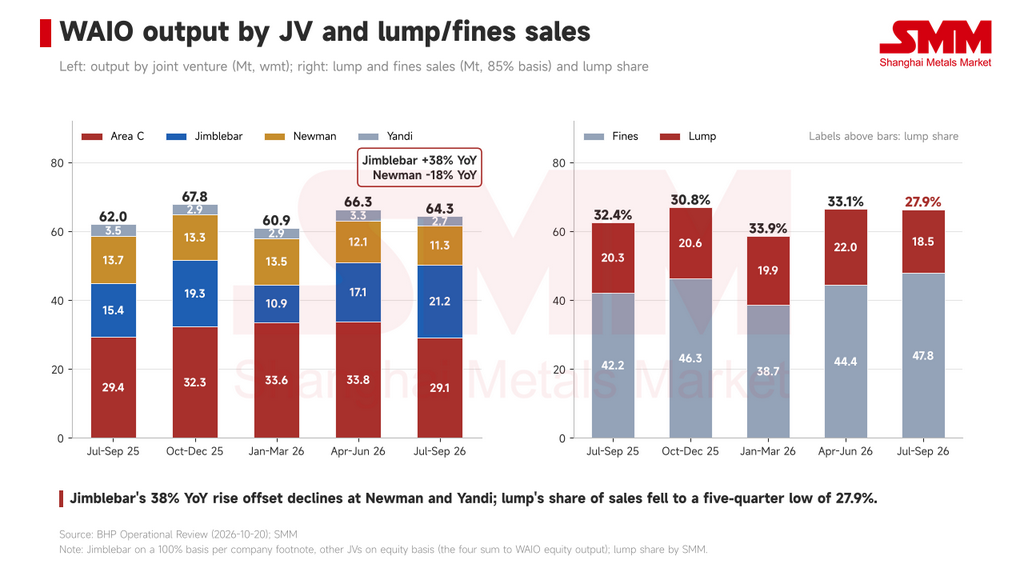
Product mix: WAIO lump sales were 18.51 Mt on an equity basis, down 8.6% year on year and 15.9% quarter on quarter, while fines sales rose 13.3% to 47.80 Mt. Lump made up 27.9% of WAIO sales, the lowest in five quarters, against 33.1% in the previous quarter (SMM calculation from company sales data).
Samarco: Equity output was 2.15 Mt (dmt; 4.3 Mt on a 100% basis), up 4.1% year on year, which BHP attributed to strong concentrator performance. Sales were 1.94 Mt, down 4.9%. Full-year guidance stays at 7.5-8.0 Mt.
Realised price: The average realised iron ore price was US$76.27/wmt FOB, down 9% both quarter on quarter and year on year, compared with US$84.04/wmt a year earlier. BHP noted the figure is a provisional, unaudited estimate including provisional pricing and finalisation adjustments.
03 Port and capacity projects
BHP has no new mine in ramp-up this quarter; its capacity milestones sit in the port and crushing chain.
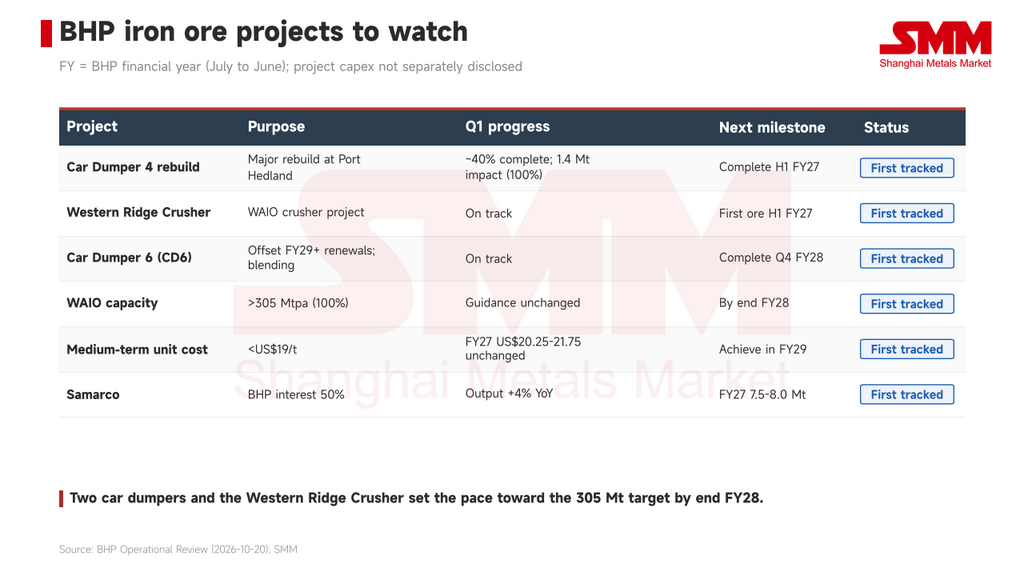
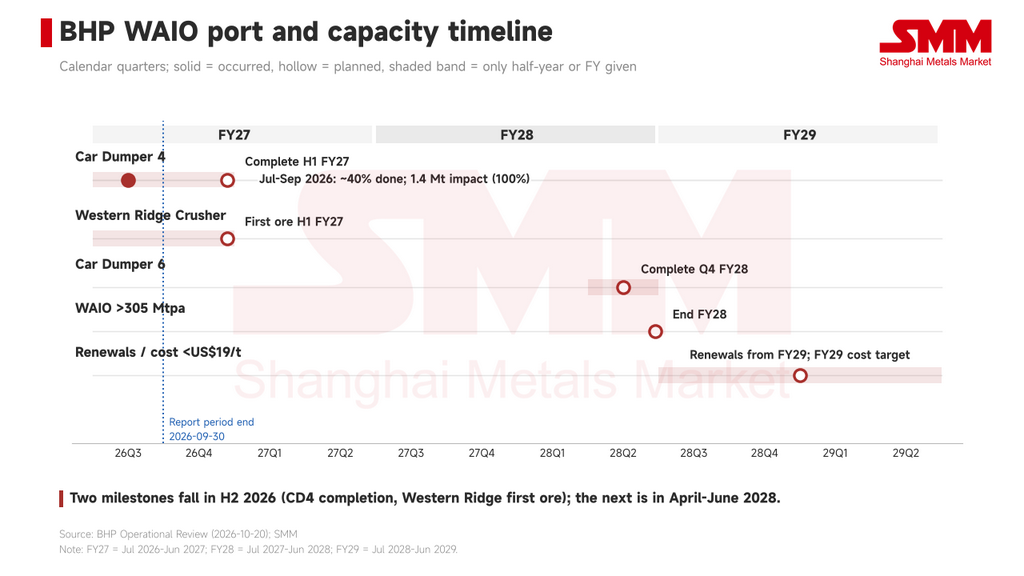
Car Dumper 4: The major rebuild of Car Dumper 4 at Port Hedland cut Q1 volumes by 1.4 Mt (100% basis). The work is about 40% complete and BHP said it remains on track for completion in H1 FY27 (July-December 2026).
Car Dumper 6: CD6 is on track for completion in Q4 FY28 (April-June 2028). BHP expects it to offset the production impact of major car dumper renewals from FY29 and to improve ore blending and screening at the port.
Western Ridge Crusher: The project remains on track, with first ore scheduled for H1 FY27.
Capacity target: BHP said these investments support WAIO production above 305 Mt (100% basis) by the end of FY28.
04 Costs and market
Unit cost: FY27 WAIO unit cost guidance was kept at US$20.25-21.75/t, based on an AUD/USD rate of 0.70 and subject to movements in the diesel benchmark. Medium-term guidance is above 305 Mtpa at a unit cost below US$19/t, expected to be achieved in FY29.
BHP's market view: Chief Executive Brandon Craig said global markets remain volatile, with geopolitical tension, trade uncertainty and elevated energy and freight costs creating headwinds for the industry. He added that demand for commodities remains resilient, supported by continued industrialisation and urbanisation in China and India.
05 Full-year guidance progress
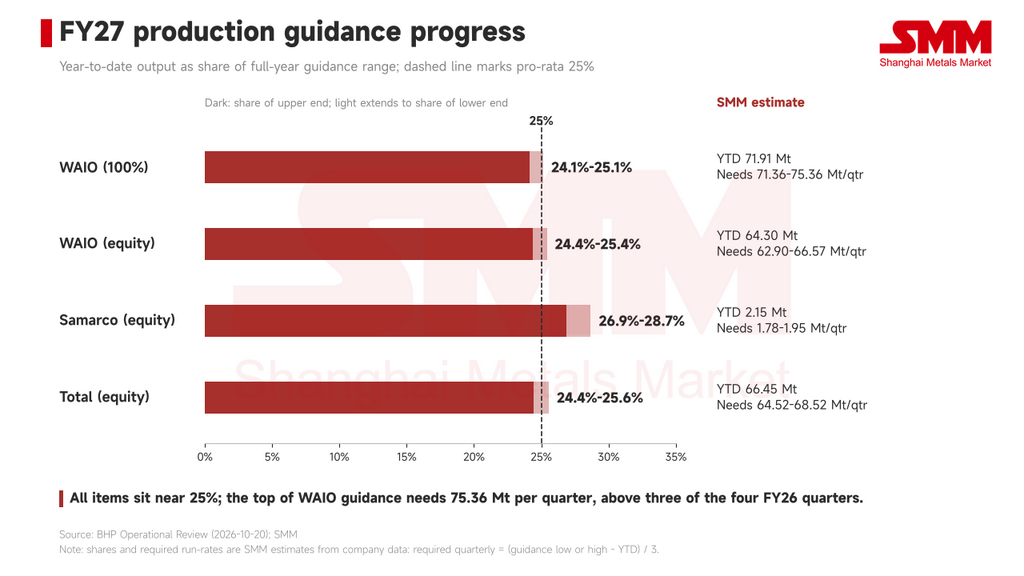
Progress: Q1 WAIO output equals 24.1-25.1% of full-year guidance (100% basis), broadly in line with a pro-rata 25% (SMM estimate from company data; same below).
What is left: To reach the low and high ends of guidance, WAIO needs average output of 71.36 Mt and 75.36 Mt per quarter over the remaining three quarters. For reference, FY26 quarterly output was 70.25 Mt, 76.33 Mt, 69.75 Mt and 74.84 Mt; only October-December 2025 exceeded the run-rate implied by the top of the range.
Risks: The Car Dumper 4 rebuild continues through Q2 and BHP has not disclosed the Q2 volume impact. WAIO unit cost guidance is explicitly subject to the diesel benchmark. Samarco is at 26.9-28.7% of guidance, slightly ahead of pro-rata.
06 Next-quarter watch
The first thing to watch next quarter is whether the two projects at Port Hedland close out on schedule before the end of 2026. The Car Dumper 4 rebuild was about 40% complete this quarter, and BHP has set completion for H1 FY27, which means by December 2026. It has already cost WAIO 1.4 Mt (100% basis) this quarter, and the company has not disclosed the Q2 impact, so whether Q2 output reaches the 71.36 Mt quarterly average needed for the low end of guidance is the first signal of whether the rebuild is weighing on the full-year target. First ore from the Western Ridge Crusher is also scheduled for H1 FY27. As the replacement project on the mine side of WAIO, its timing will decide mine-side supply capacity in 2027.
The second is product mix. Lump fell to 27.9% of WAIO sales this quarter, the lowest in five quarters, and the report offered no explanation. If the share returns to above 30% next quarter, this quarter’s decline is most likely a matter of sales timing; if it stays near 28%, it should be treated as a structural shift, and views on lump availability in China and on lump premiums will need to be adjusted accordingly.
The third is costs. WAIO unit cost guidance of US$20.25-21.75/t is explicitly subject to the diesel benchmark, and the company’s commentary this quarter also pointed to elevated energy and freight costs. Whether guidance is adjusted for diesel prices next quarter, and by how much, will directly affect BHP’s position on the cost curve.
07 Our view
BHP’s supply change this quarter lies in product mix rather than volume. WAIO output still rose 2.4% year on year despite the 1.4 Mt hit from the Car Dumper 4 rebuild, with Jimblebar’s growth offsetting declines at Newman and Yandi, so there was no surprise at the headline level. The change sits between lump and fines: lump sales fell by about 1.75 Mt year on year while fines sales rose by about 5.62 Mt, taking lump’s share down to 27.9% (equity basis). If this mix persists in the coming quarters, the market will see relatively less BHP lump and relatively more BHP fines.
The pressure to meet full-year production guidance falls on the remaining three quarters. By SMM’s estimate, the top of the range requires average quarterly output above three of the four FY26 quarters, while Q2 is still affected by the Car Dumper 4 rebuild. Whether Car Dumper 4 and the Western Ridge Crusher are delivered on schedule by the end of 2026 is the main condition for judging BHP’s shipment pace in the first half of 2027. With guidance unchanged, BHP’s total supply to China is expected to remain stable, and the shift in the lump/fines mix deserves closer attention.