SMM, October 17:
In the metals market:
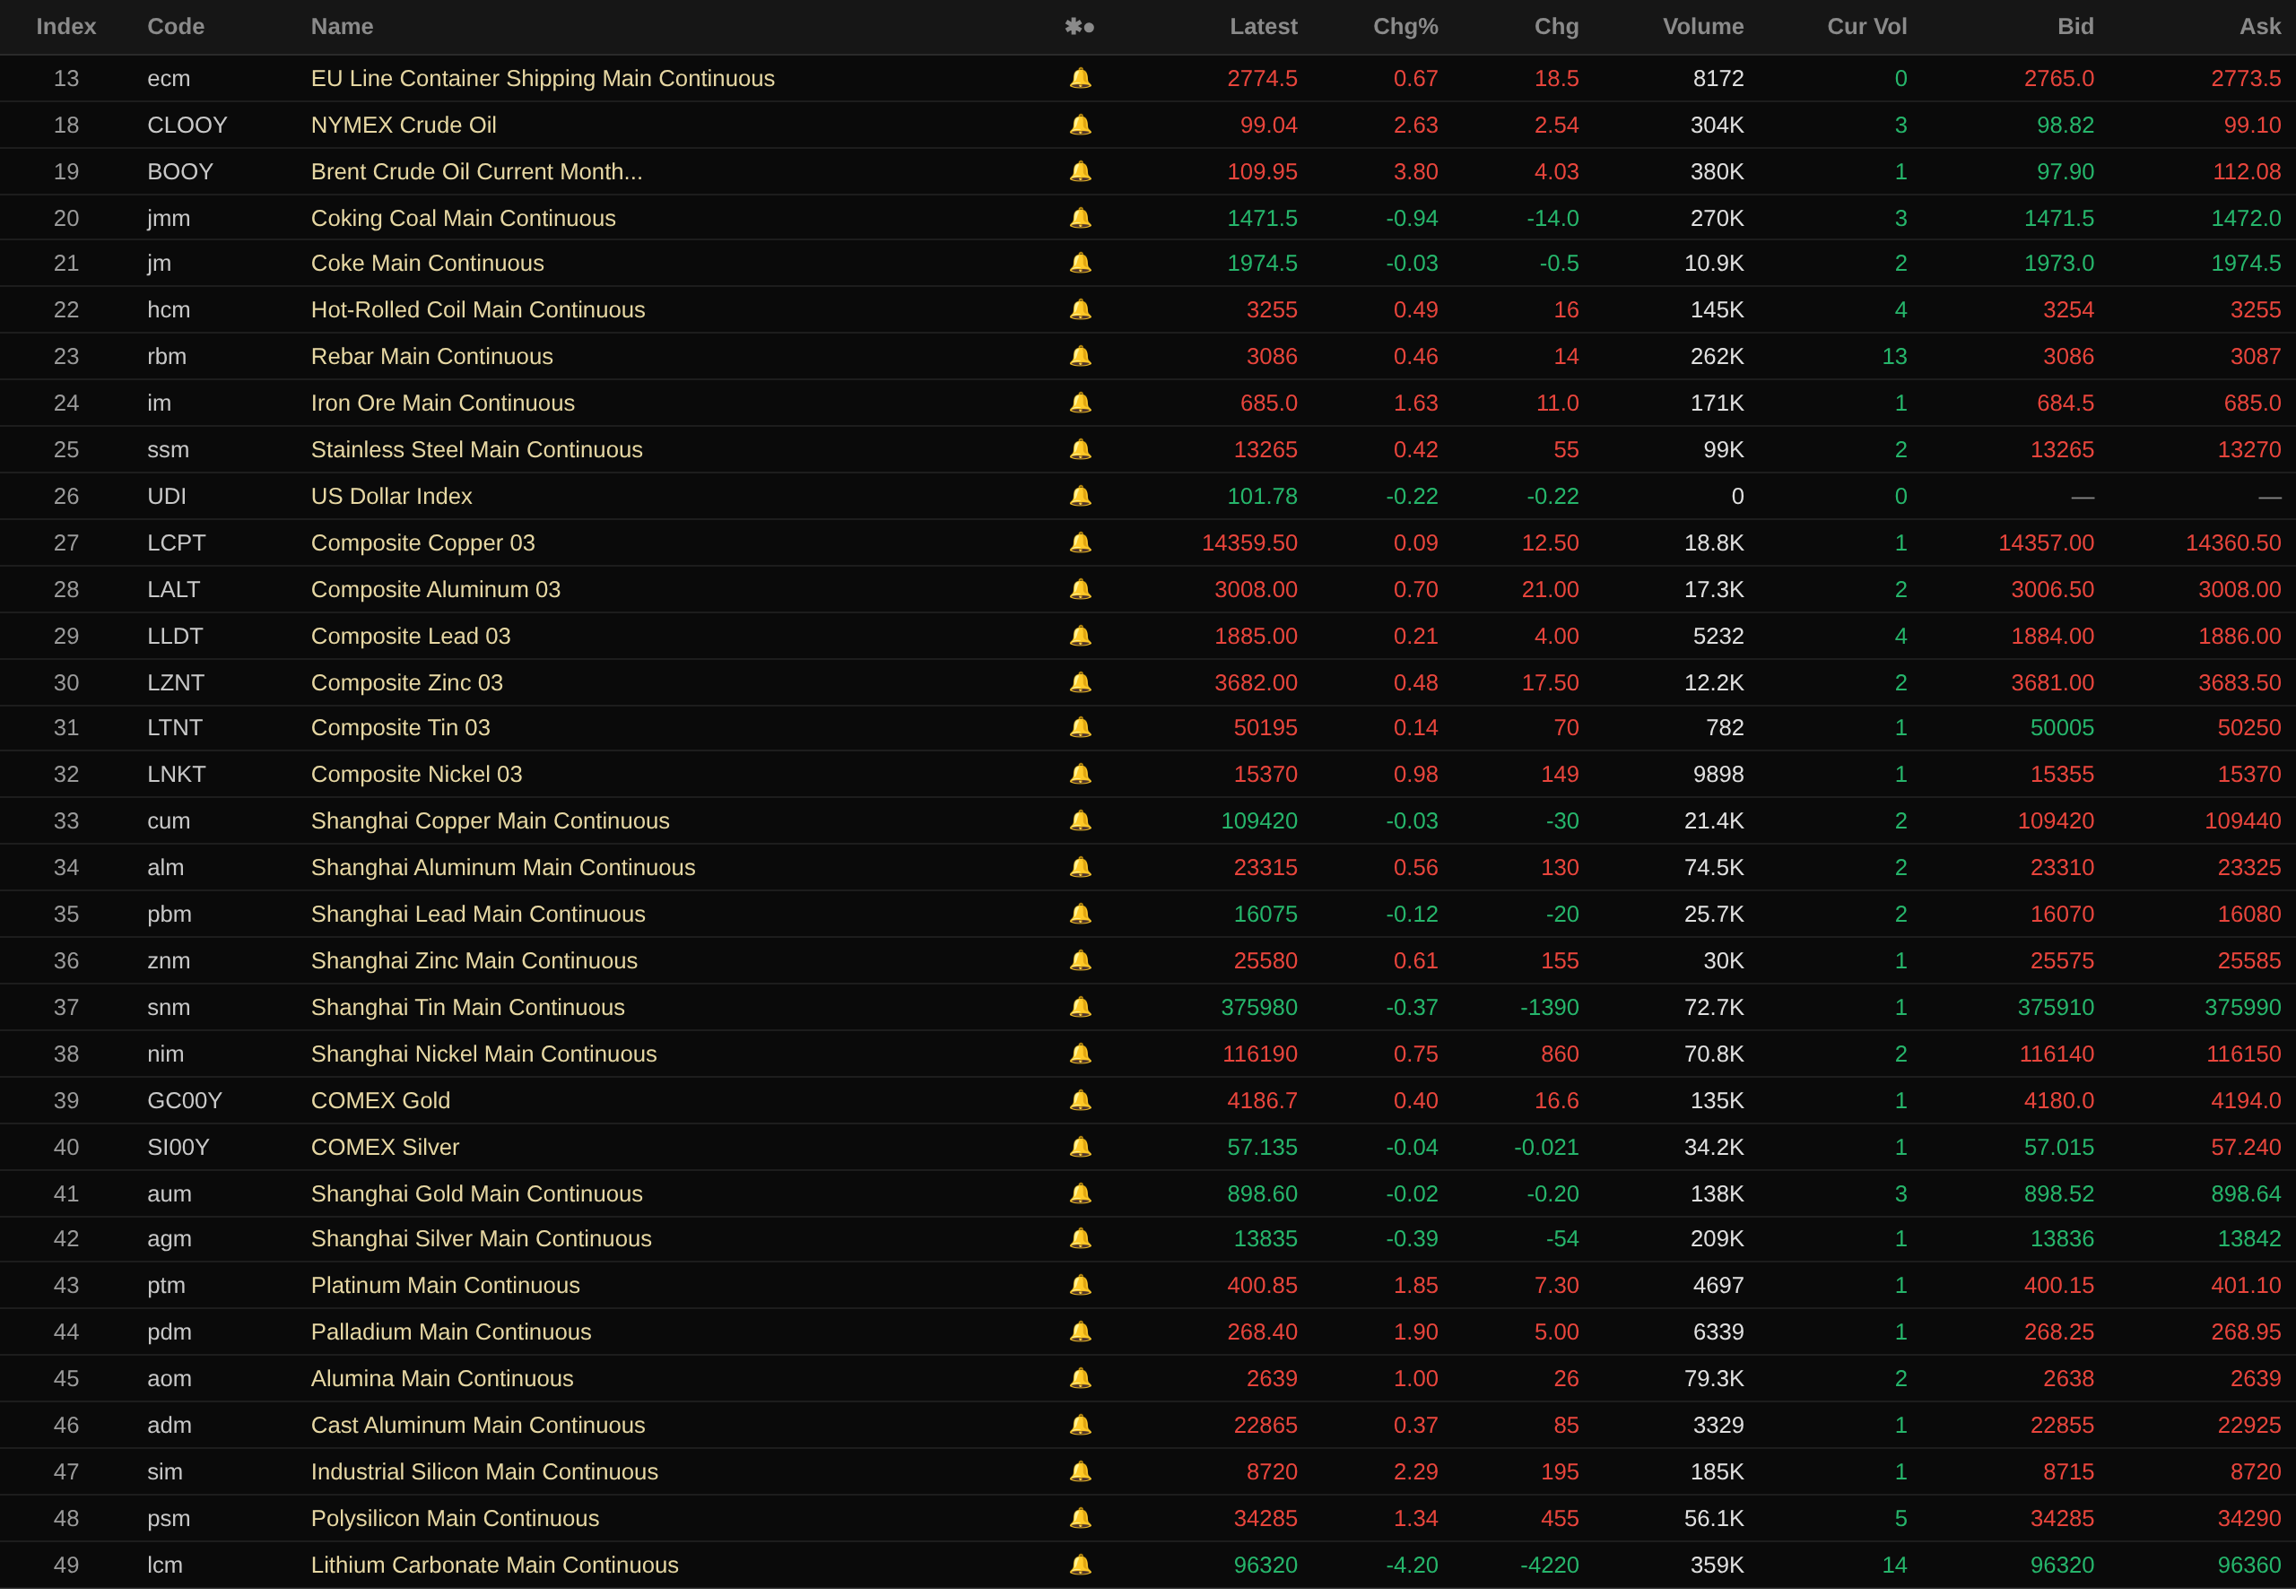
Overnight, base metals on both domestic and overseas markets mostly rose, with only SHFE copper, SHFE lead, and SHFE tin falling together. SHFE copper fell 0.03%, SHFE lead fell 0.12%, and SHFE tin fell 0.37%. LME nickel led the gains with a 0.98% increase, SHFE nickel rose 0.75%, and LME aluminum rose 0.7%. Changes for other metals were relatively small. The alumina main contract rose 1%, and the cast aluminum main contract rose 0.37%.
Overnight, ferrous metals mostly rose, with iron ore leading the gains at 1.63%. HRC, rebar, and stainless steel all rose around 0.4%. For coking coal and coke, coking coal fell 0.94%, and coke fell 0.03%.
Overnight in precious metals, COMEX gold rose 0.4%, and COMEX silver fell 0.04%. On the weekly chart, COMEX gold fell 0.7%, and COMEX silver fell 6.41%. In China, SHFE gold fell 0.02% overnight, and SHFE silver fell 0.39%. On the weekly chart, SHFE gold rose 0.3%, and SHFE silver fell 3.35%.
As of 8:57 on October 17, overnight closing prices:
Macro front
In China:
[Two ministries plan to prohibit or restrict the export of 40 technologies in AI, biomedicine, and PV] The Ministry of Commerce and the Ministry of Science and Technology announced on the 16th that they plan to revise China's Catalogue of Technologies Prohibited and Restricted from Export, adding certain AI, biomedicine, and PV technologies. Upon approval, they are now soliciting public comments and will simultaneously implement pre-export registration management for the relevant technologies. This public consultation covers 40 technologies in AI, biomedicine, and PV. The AI sector includes 23 technologies related to large models, intelligent agents, computing clusters, and information processing; technologies that have entered the public domain through open source, academic paper publication, or other means are not included in the management scope. The biomedicine sector includes 5 technologies related to cell and gene therapy, small nucleic acid drugs, and pathogenic microorganisms; for outbound licensing models that do not involve ownership transfer, facilitation measures such as automatic licensing apply. The PV sector includes 12 technologies related to polysilicon manufacturing, wafer manufacturing, and battery manufacturing; the technology management scope also includes key and core equipment carrying the relevant technologies.
[Four ministries organize discussions with over 30 automakers to strengthen management of automotive product R&D testing and verification] According to the Ministry of Industry and Information Technology, the MIIT, the Ministry of Public Security, the Ministry of Ecology and Environment, and the State Administration for Market Regulation organized discussions with more than 30 key automobile producers to strengthen the management of innovative design and R&D testing and verification for automotive products. It is understood that automotive producers should implement the requirements of the special action for quality improvement, resolutely resist irrational competition, strengthen innovative design of automotive products and management of R&D testing and verification, and firmly uphold the bottom line of product safety. Next, efforts will be accelerated to advance the revision of relevant standards, further raise baseline safety requirements, continue supervision and inspection of key automotive producers, seriously deal with producers with problems in accordance with laws and regulations, publicly expose them, urge automotive producers to strengthen product testing and verification, firmly uphold the bottom line of product safety, and promote high-quality development of the automotive industry. (CCTV News) (Jin10 Data APP)
On the US dollar front:
As of the overnight close, the US dollar index fell 0.19% to 101.78, down 0.44% for the week. Fed Chairman Warsh's remarks failed to boost the dollar, which ended a four-week winning streak. Warsh made no comments on monetary policy or the US economy at the IMF annual meeting in Bangkok on Friday morning, prompting investors to scale back bets on a Fed rate hike later this month. This was Warsh's last chance to signal a policy stance before the Fed entered its quiet period ahead of the October policy meeting on Saturday. Noah Buffam, strategist at CIBC Capital Markets, said: "Warsh offered no policy guidance. Although this was expected at this stage, the market interpreted it as a signal that the Fed may not raise rates at the October meeting." (Jin10 Data APP)
The energy shock is beginning to spill over into all areas of the US economy: enterprises are passing rising costs downstream, complicating the Fed's task of stabilizing inflation. Two reports this week showed that prices in categories such as airfares, express delivery services, and freight rose sharply in September; the main driver was higher oil prices pushed up by overseas wars. Investors expect the Fed to wait and see how inflationary pressures evolve, holding steady at the October meeting after raising rates in September for the first time in more than three years. (From Wall Street CN APP)
After this week's inflation data came in higher than expected, economists at Barclays added a January rate hike to their Fed forecast. Economists led by Mark Giannoni wrote in a report on Friday: "The September CPI and PPI reports prompted us to raise our inflation outlook, as several risks we have long highlighted—including the pass-through of energy prices to core prices, the continued resilience of consumer spending, and AI-related price pressures—are increasingly showing up in the data." The team now expects the Fed to raise rates by 25 basis points each in December and next January, followed by maintaining the federal funds target rate range at 4.25%–4.50% "for an extended period."They previously expected the Fed to make a final 25bp rate hike in December, then hold rates steady for most of next year until a 25bp cut in December 2027. (from Wallstreetcn APP)
According to CME "Fed Watch": the probability of the Fed keeping rates unchanged through October is 71.8%, and the probability of a cumulative 25bp hike is 28.2%. The probability of the Fed keeping rates unchanged through December is 7.2%, the probability of a cumulative 25bp hike is 67.4%, and the probability of a cumulative 50bp hike is 25.4%. (from Jin10 Data APP)
Other currencies:
BOJ Governor Ueda Kazuo: has been watching the impact of yen weakness and the Middle East situation on inflation. Will continue to adjust the degree of easing. Stabilising inflation at the 2% level is becoming increasingly important. Will monitor the impact of exchange rates, AI and the Middle East situation on price trends. Has not spoken with US Treasury Secretary Bessent since Asheville. Will focus on consolidating the 2% inflation target going forward. Cannot tolerate underlying inflation rising further above 2%. Underlying inflation is already quite close to 2%, marking a policy shift. Exchanged views with Fed Chairman Warsh on a number of topics. There is no evidence that the neutral rate is near any particular level. (Wallstreetcn)
Two key economic data releases on Monday may determine whether the Bank of Canada will hike rates later this month. Statistics Canada will release September inflation data at 8:30 am Ottawa time, followed by the Bank of Canada's latest business and consumer outlook surveys. These will be the last two important inputs before the October 28 rate decision for policymakers to assess how the Canadian economy is coping with oil-price-driven inflation risks and escalating trade tensions. The Bank of Canada has kept its benchmark rate unchanged at 2.25% for seven consecutive meetings. However, policymakers have warned that the longer gasoline prices stay high, the more likely businesses are to raise prices for other goods and services. Analysts leaning toward easing note that September jobs data showed employment losses and a rising unemployment rate in Canada. But if Monday's data show persistent price pressures and a stabilising economy, weak jobs data may still not be enough to stop the central bank from hiking rates. (from Jin10 Data APP)
Data:
Next week in China, data to be released include China's Q3 GDP YoY, China's September total retail sales of consumer goods YoY, China's September industrial value added above designated size YoY, China's one-year loan prime rate as of October 20, China's installed power generation capacity year-to-date as of September (TBD), China's installed power generation capacity YoY year-to-date as of September (TBD), and China's September share of Swift RMB in global payments. In the US, data to be released include the US October NAHB housing market index, US weekly change in ADP employment as of the week of October 3, US September annualised housing starts, US September total building permits, US September pending home sales index MoM, US initial jobless claims for the week ending October 17, eurozone October preliminary consumer confidence index, US October preliminary S&P Global manufacturing PMI, US October preliminary S&P Global services PMI, US October final University of Michigan consumer sentiment index, and US October final one-year inflation expectations. In the UK, data to be released include UK August three-month ILO unemployment rate, UK September unemployment rate, UK September claimant count change, UK September public sector net borrowing, UK September retail price index MoM, UK October CBI industrial order balance, UK October GfK consumer confidence index, UK September seasonally adjusted retail sales MoM, UK October preliminary manufacturing PMI, and UK October preliminary services PMI. In the eurozone, data to be released include eurozone August seasonally adjusted current account, eurozone October ZEW economic sentiment index, eurozone October preliminary consumer confidence index, and eurozone October preliminary manufacturing PMI. In Germany, data to be released include Germany September PPI MoM, Germany October ZEW economic sentiment index, and Germany October preliminary manufacturing PMI. Canada September CPI MoM, Canada August retail sales MoM, Switzerland September trade balance, France October preliminary manufacturing PMI, and Japan September core CPI YoY will also be released.
In addition, the National Bureau of Statistics (NBS) released the monthly report on residential selling prices in 70 large and medium-sized cities, the State Council Information Office held a press conference on national economic performance, the 2026 Financial Street Forum Annual Conference opened in Beijing and runs until October 22 (tentative), the 2026 Financial Street Forum Annual Conference was held (tentative), the 33rd APEC Finance Ministers' Meeting was held in Hong Kong, China from October 20 to 21 (tentative), the 2026 Financial Street Forum Annual Conference was held (tentative), Bank of England Governor Bailey delivered a speech, and European Central Bank President Lagarde delivered a speech.
It is worth noting that,on October19, the Hong Kong Exchanges and Clearing in China-was closed for one day due to the Chung Yeung Festival, with both southbound and northbound trading suspended.On October 21, affected by the contract rollover of NYMEX November crude oil futures, the final floor trading was completed at 2:30 on October 21, and the final electronic trading was completed at 5:00 a.m. Please pay attention to the expiration and contract rollover announcements of the trading venue to manage risks. In addition, the expiration time of US oil contracts on some trading platforms is usually one day earlier than the official NYMEX date, so please pay extra attention.
Crude oil:
Overnight, oil prices in both markets rose together, with US oil up 2.63%, recording a seven-day winning streak, and Brent oil up 3.8%. This was mainly affected by the Middle East situation and Russian supply concerns. On a weekly basis, US oil surged 7.83%, while Brent oil rose 4.99%.
On the 16th local time, the Iranian Navy stated that a few hours earlier, a naval surveillance team, while continuously monitoring the eastern waters of the Strait of Hormuz, discovered and identified an offending tanker on fire in a no-navigation zone. The offending tanker had turned off its navigation tracking system and attempted to cross the no-navigation zone in the Gulf of Oman. The Iranian Navy emphasized that disorderly navigation in no-navigation zones would endanger safety and pose numerous dangers to other vessels. (Jin10 Data)
According to the Islamic Republic of Iran Broadcasting (IRIB), Commander-in-Chief of the Iranian Army Khatami stated on October 15 that the Strait of Hormuz remains closed and will not reopen until the rights of the Iranian people are respected, and that external claims about the strait having reopened are untrue. Khatami said that the western part of the Strait of Hormuz is controlled by the Navy of the Islamic Revolutionary Guard Corps, while the eastern part and the Sea of Oman are controlled by the Iranian Army Navy. Khatami warned that if Iran's infrastructure is attacked, Iran will retaliate several times over against the enemy's infrastructure and interests, and urged opponents not to launch another attack. (Jin10 Data APP)
Barclays: The recent rise in oil shipping freight rates is likely to persist for at least several more weeks. Maintain the forecast for Brent crude oil prices, expected to be $100 and $85 per barrel in 2026 and 2027, respectively. Near-term oil price risks remain skewed to the upside. (Wall Street CN)
US Capitol Hill lawmakers have introduced draft legislation seeking to block President Trump's Russian diesel deal. The sponsors of this diesel bill include one Republican lawmaker and many Democratic members. (Wall Street CN)
A document shows that the US is offering up to 17 million barrels of crude oil from its Strategic Petroleum Reserve (SPR). The crude comes from sour crude oil stored in the Bryan Mound and Big Hill underground salt cavern storage sites. This supply is part of an exchange program, under which the crude is provided to participants on a "loan" basis and returned at a later date. Delivery will take place from November to January of the following year. Bidders must return the crude oil to the Strategic Petroleum Reserve between 2028 and 2029, along with a premium of at least 12.5%. The bid deadline is 11:00 a.m. Central Time on October 21. The US Department of Energy stated that this tender will be conducted on a "negotiated" basis, meaning "the government may discuss the quantity of crude oil exchanged, the quality, or any other terms of this tender with bidders." (Wall Street CN)