SMM, October 16:
Sep 2026survey data:
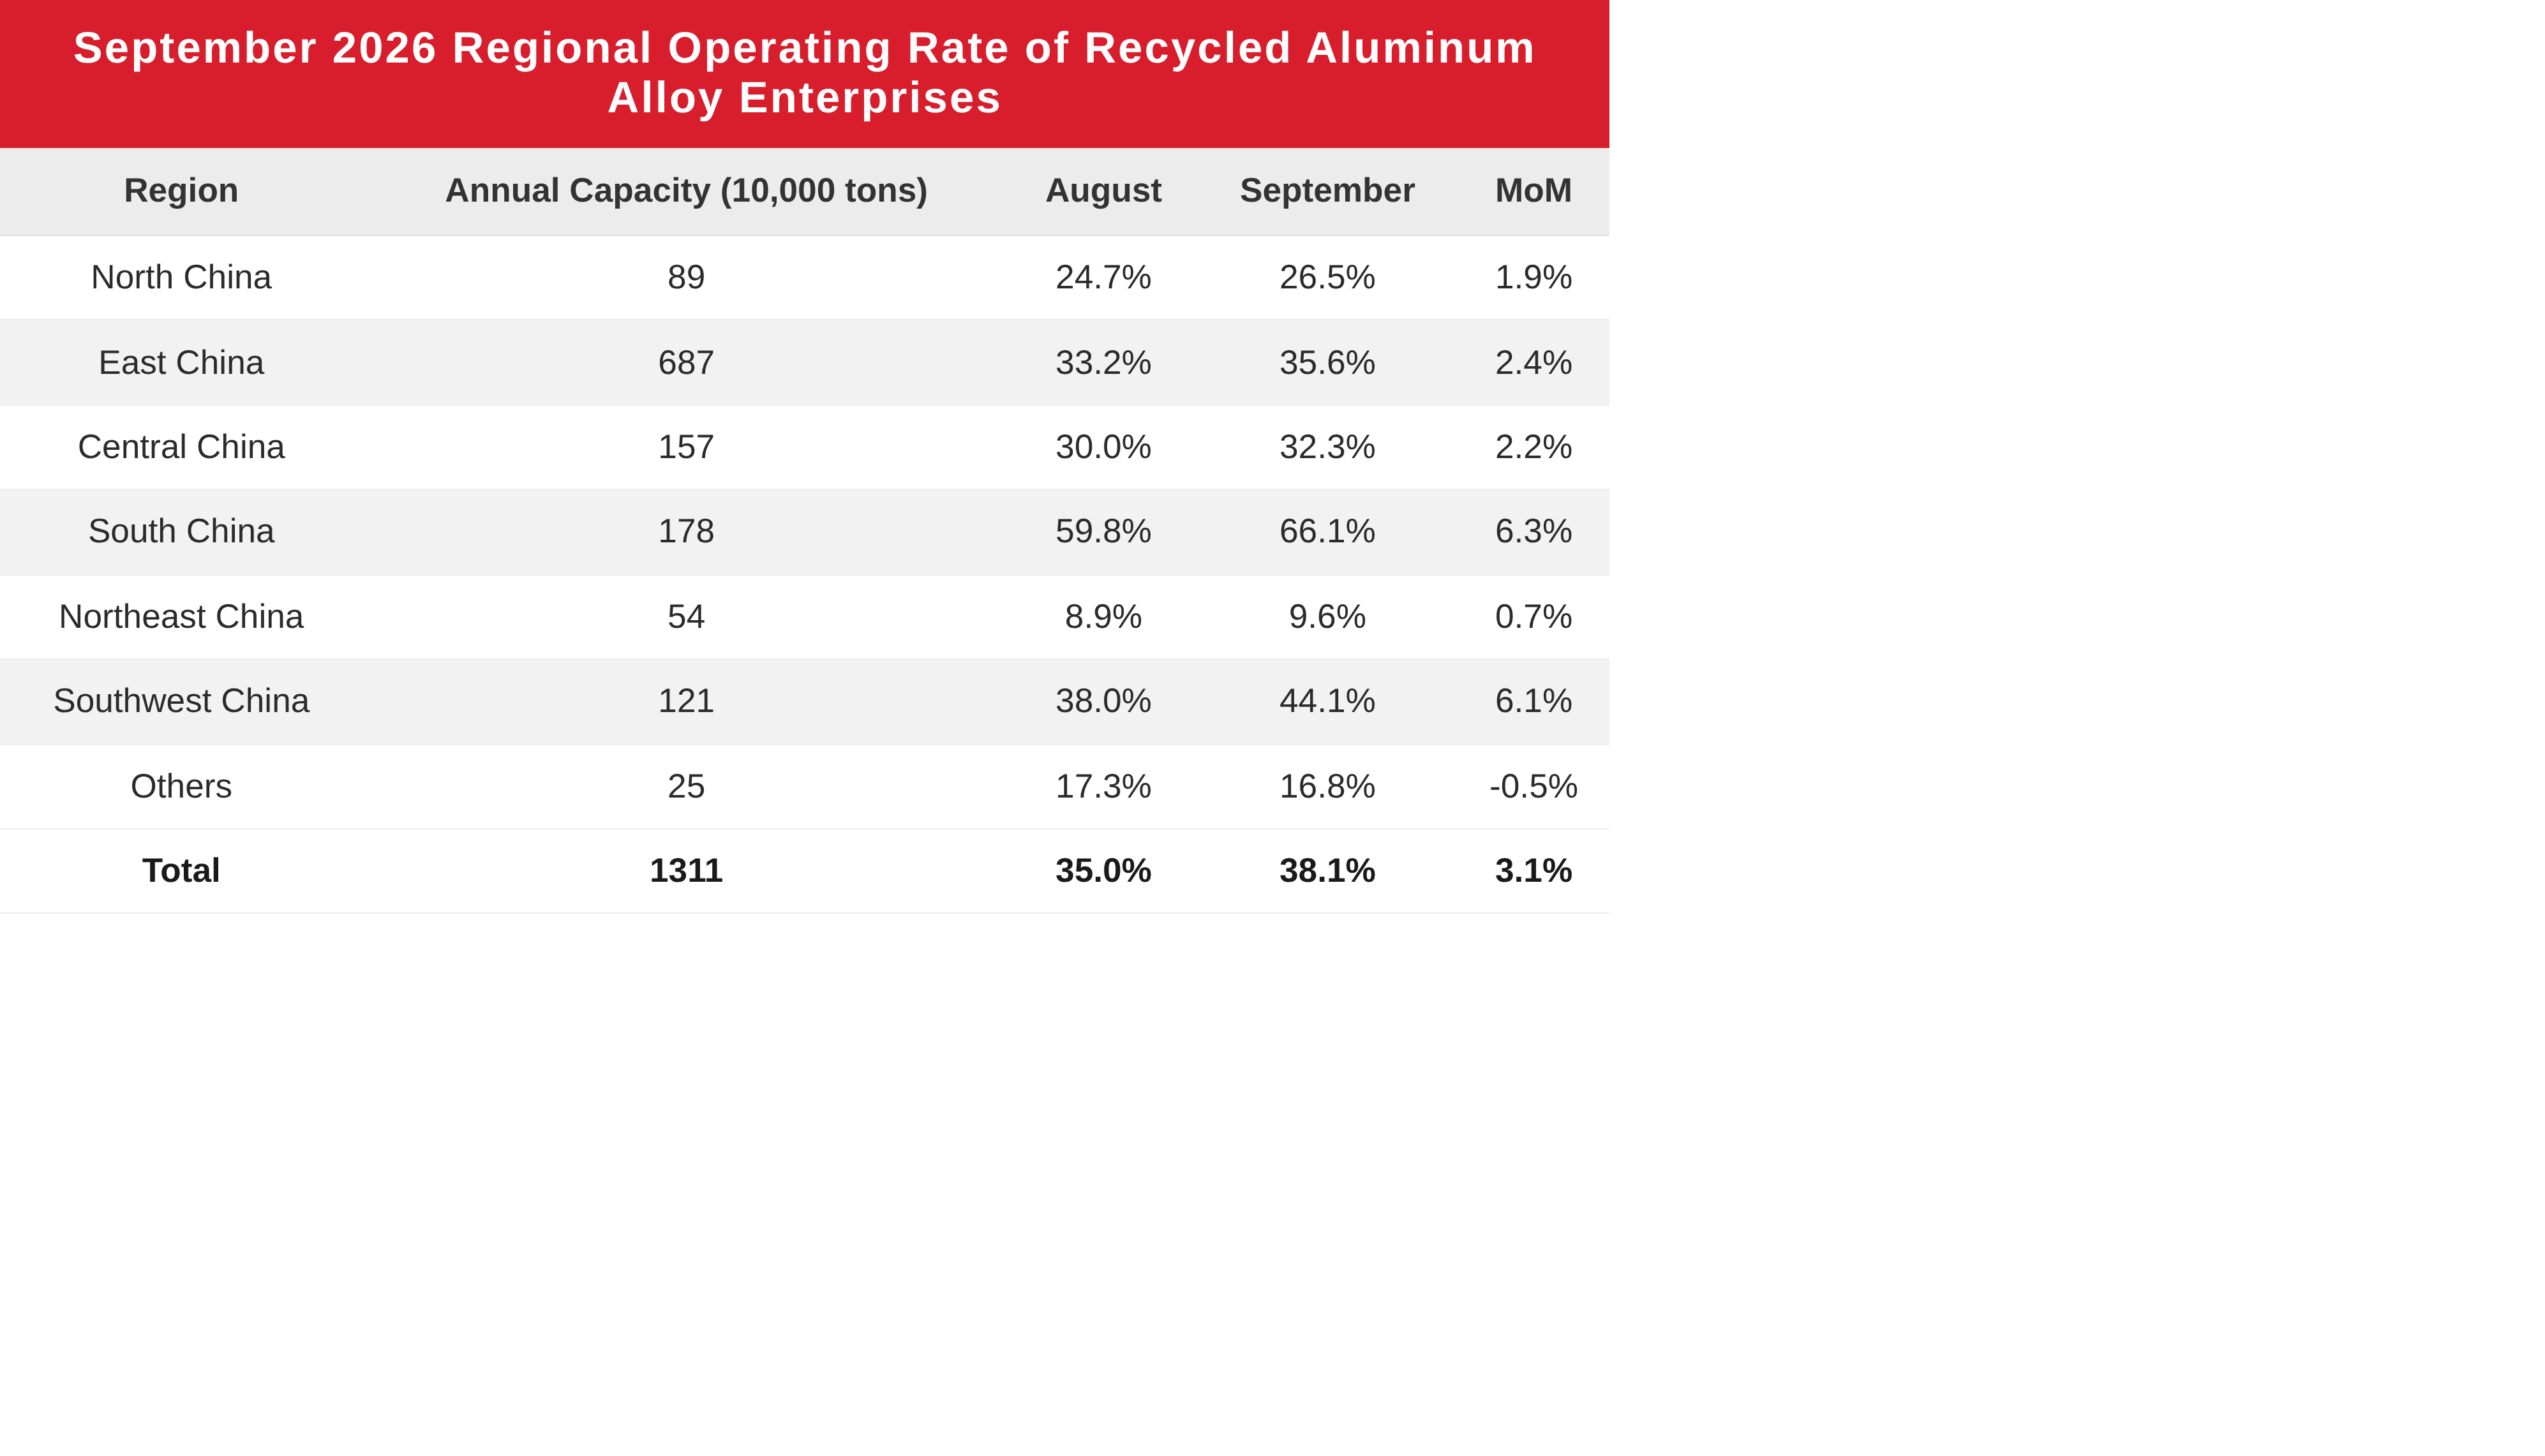
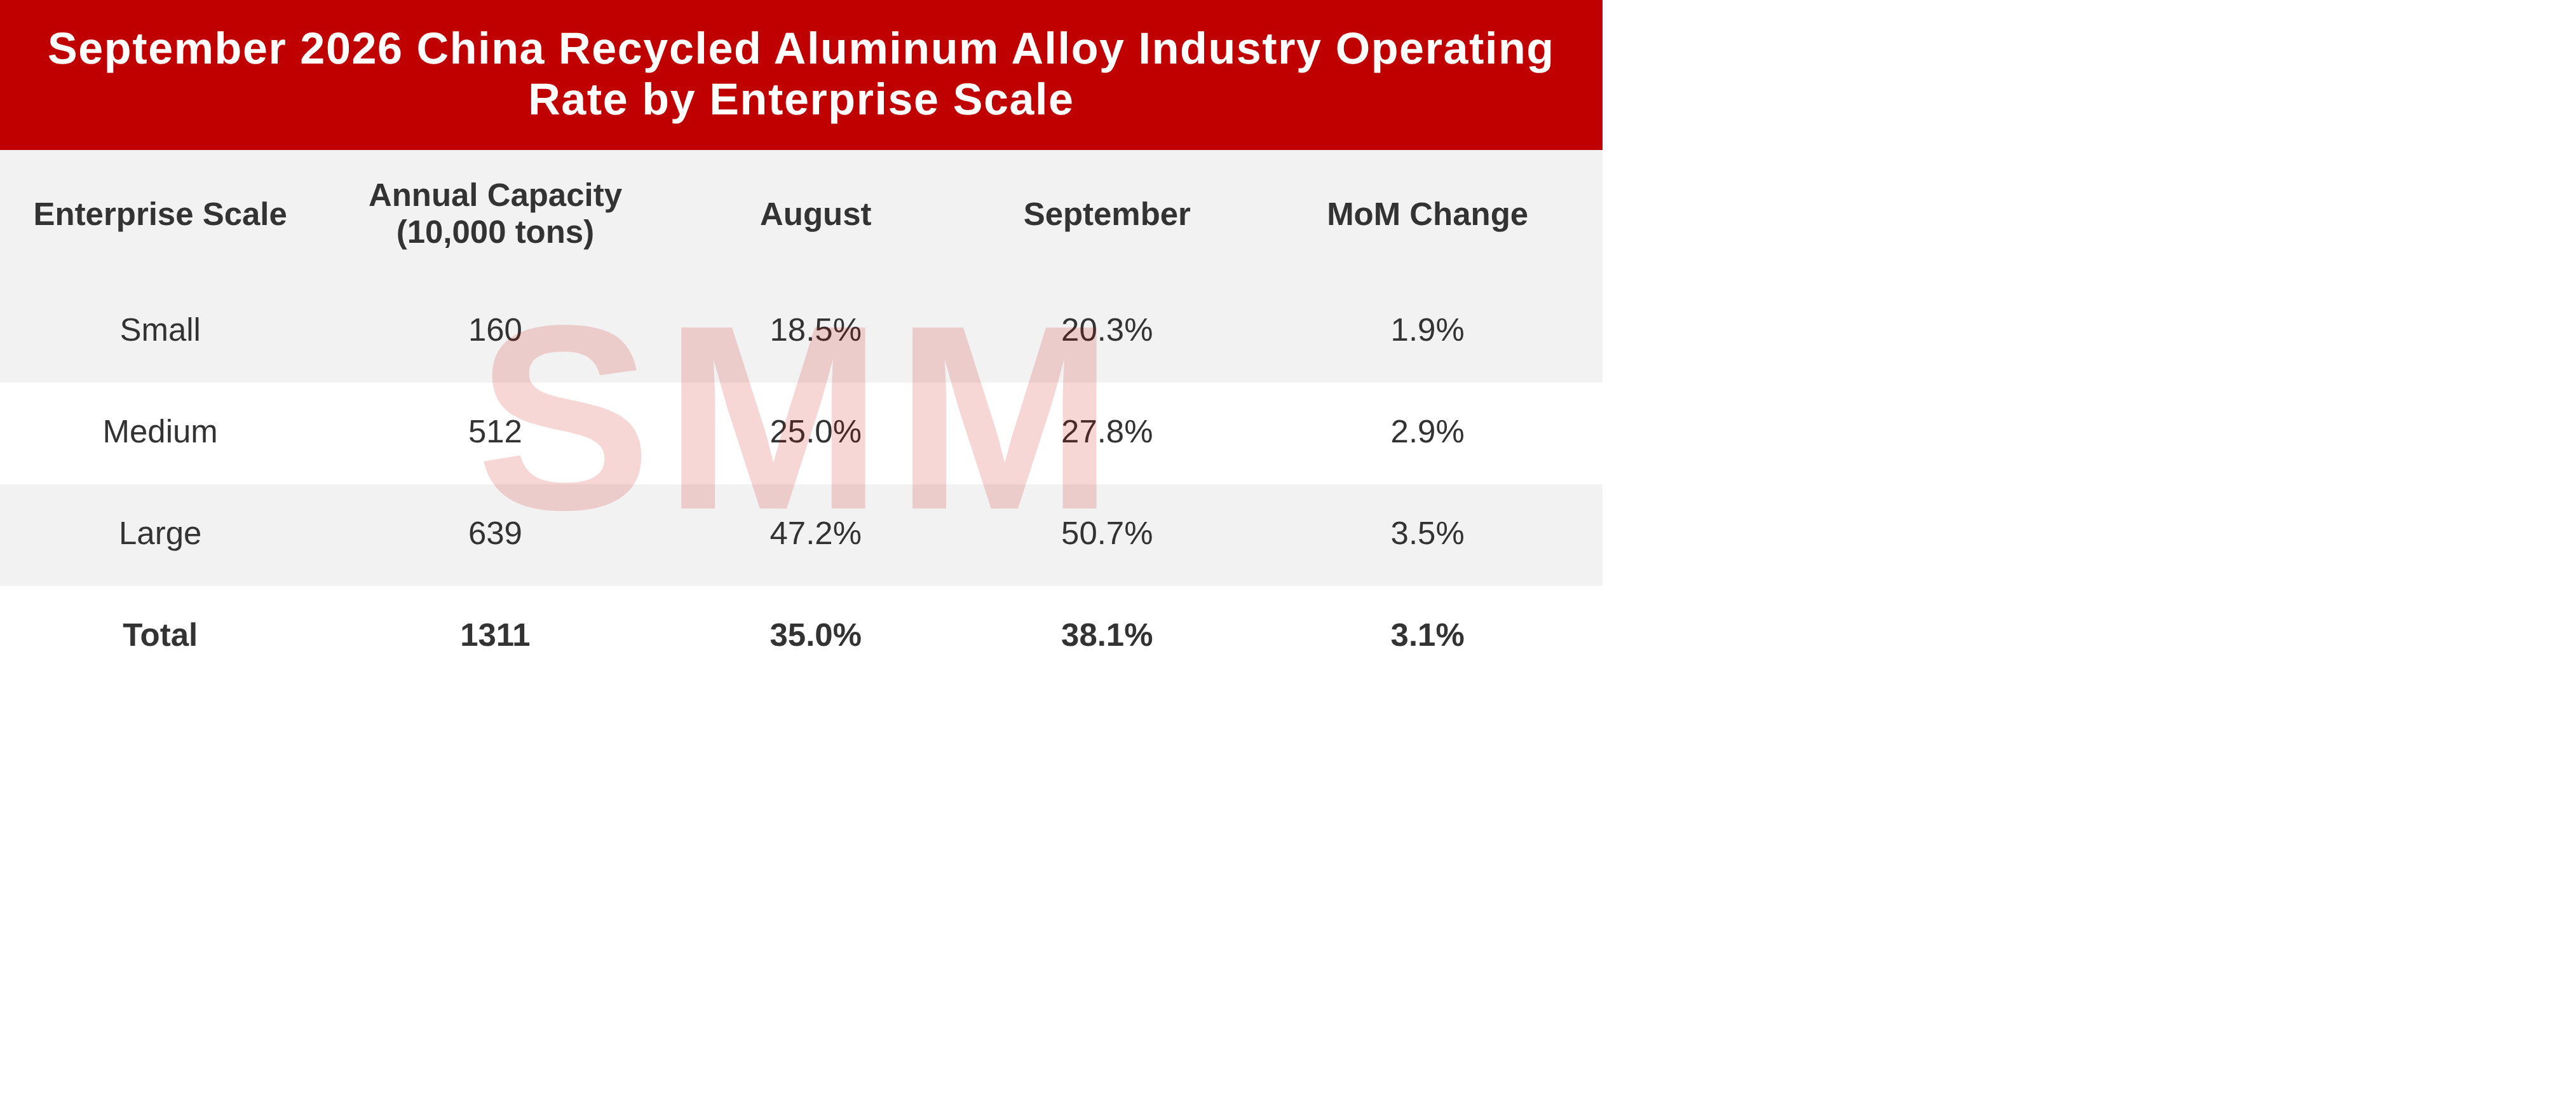
According to SMM survey statistics, the operating rate of the secondary aluminum alloy industry in September was 35.0%, up 3.1 percentage points MoM but down 6.7 percentage points YoY. Industry production continued its recovery trend, but the overall operating level remained below the same period last year.
On the demand side, September marked the traditional peak consumption season, with downstream orders recovering from August. End-use demand from automobiles and other sectors improved marginally, but the peak season effect has yet to fully materialize. According to CAAM data, automobile production in September was 2.99 million units, up 11.4% MoM but down 8.7% YoY. NEV production was 1.814 million units, up 12.2% YoY. CAAM noted that China's automotive market in the first three quarters showed a pattern of "cold at home, hot abroad," with the Chinese market remaining under pressure while exports maintained relatively fast growth, and new momentum from NEVs continued to be released. Looking ahead to Q4, as the trade-in policy takes further effect and various consumption-promotion activities continue to advance, the Chinese auto market is expected to gradually improve. Coupled with sustained export growth, demand along the automotive industry chain is expected to receive some support. However, given that the recovery of domestic end-use demand remains insufficient, downstream demand for ADC12 is expected to improve only mildly in the short term, and the actual demand growth and its boost to industry production remain to be seen.
On the raw material side, affected by stricter enforcement of fiscal and tax policies, the circulation of compliant aluminum scrap remained constrained. The issues of tight raw material supply and high procurement costs have yet to ease, and some enterprises faced greater difficulty in raw material procurement, continuing to constrain capacity release. In addition, during the Mid-Autumn Festival holiday in September, most enterprises maintained normal production, with only a few arranging short breaks, resulting in limited impact on the overall operating rate for the month.
The operating rate of the secondary aluminum alloy industry in October is expected to pull back MoM, mainly due to production suspensions during the National Day holiday and the continued tightening of fiscal and tax policies.On the holiday front, large enterprises generally maintained production, though some appropriately reduced production loads, while other enterprises mostly arranged 3-5 day holidays. The production slowdown during the holiday period will exert some drag on the monthly operating rate. On the raw material side, stricter enforcement of fiscal and tax policies is expected to continue affecting the supply of compliant aluminum scrap. Some enterprises still face significant difficulties in raw material procurement and high costs, constraining production stability and capacity release. Although downstream demand is expected to continue improving marginally after the holiday, given limited demand growth and ongoing raw material supply constraints, the room for operating rate recovery in the industry is expected to be limited.
--------------------------------------------------------------------------------------------------------------------------------------
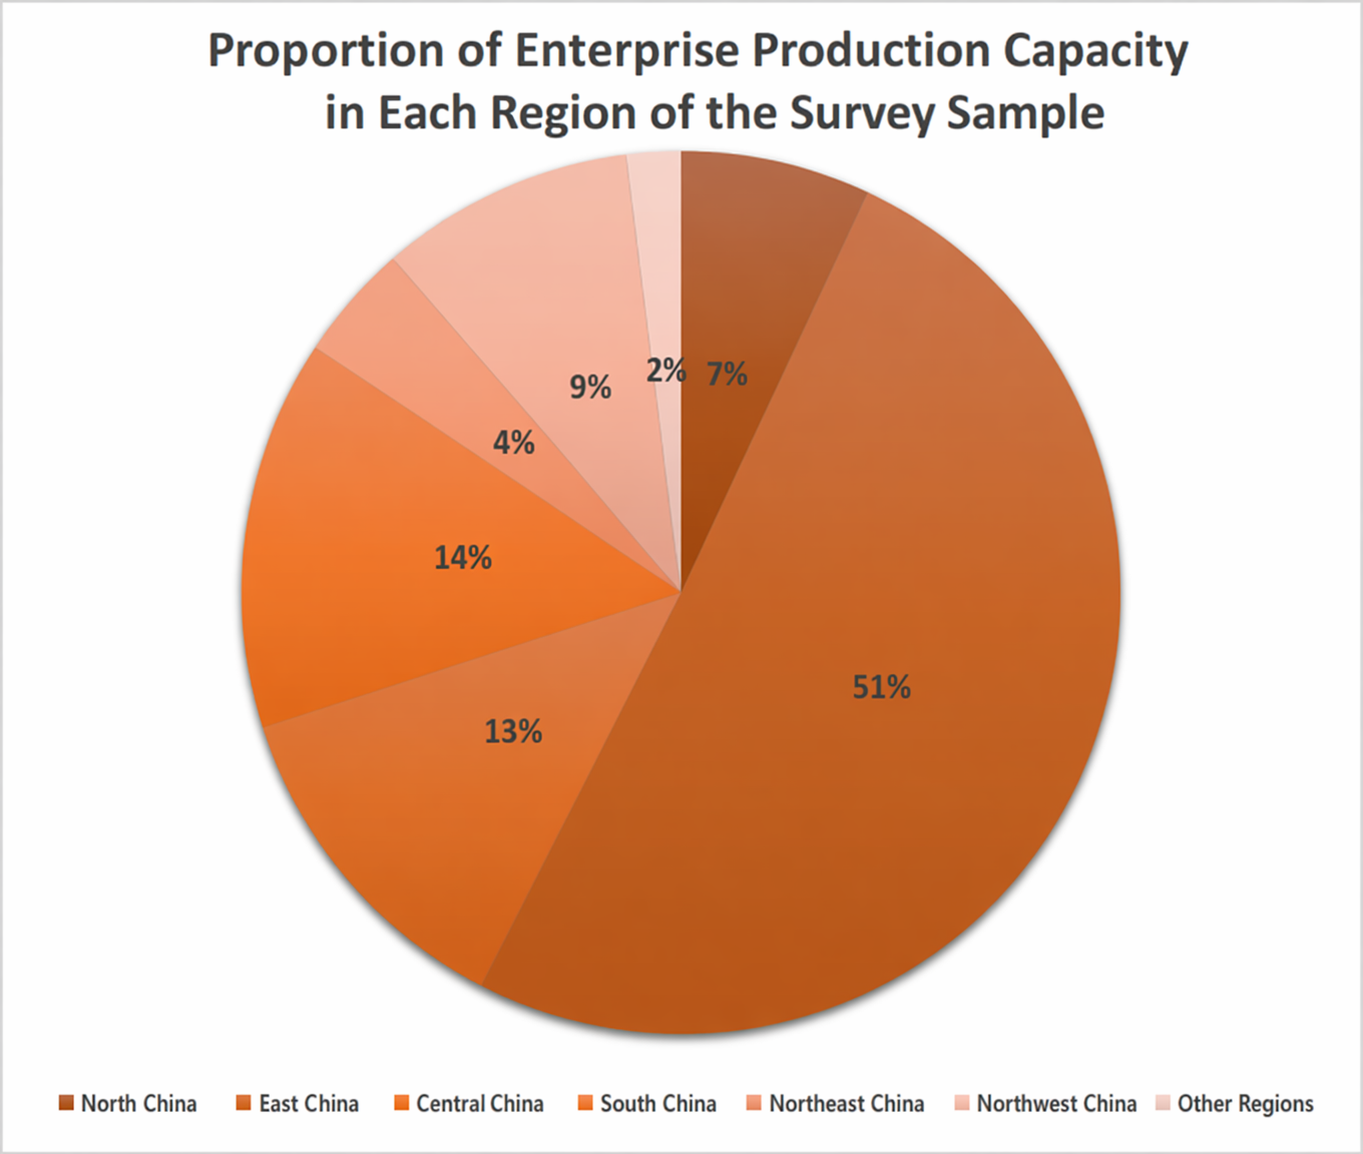
Data description: This survey covered a total capacity of 13.11 million mt.