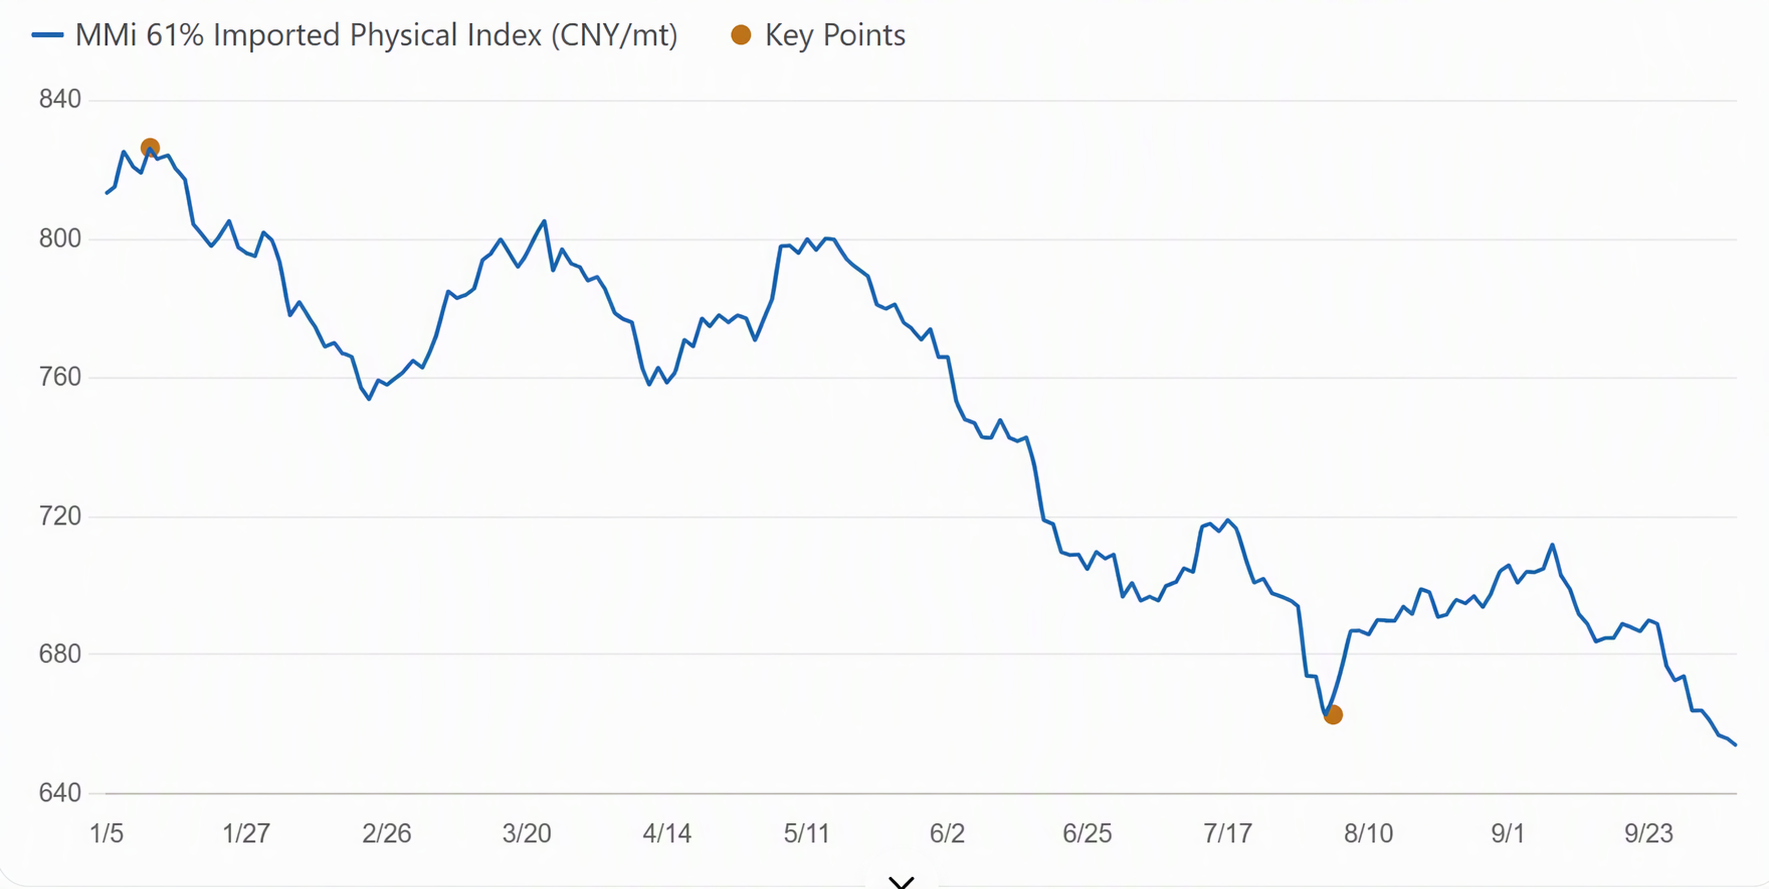
Iron ore remained in the doldrums this week, with the most-traded I2701 contract falling for four consecutive trading days to a low of 667 yuan/mt. It was down 31 yuan cumulatively from the pre-holiday level (September 30). Spot cargoes at Qingdao Port pulled back in tandem, with both futures and spot weakening together. Fundamentals showed a pattern of reduced supply and weak demand: on the supply side, although global shipments retreated from highs and China's port arrivals declined for three consecutive weeks, the first post-holiday port data showed SMM 35-port inventories increased to 148.3 million mt, an inventory buildup of 2.85 million mt from the pre-holiday level, driven mainly by coarse fines and lump ore, with the pace of inventory buildup clearly accelerating. On the demand side, the SMM survey of 242 steel mills showed daily average hot metal production fell to 2.352 million mt, down 36,200 mt from the pre-holiday level. This week, the impact from blast furnace maintenance expanded to 1.9011 million mt, rising for three consecutive weeks, leaving hot metal at a staged low. However, after two rounds of coke price cuts, the spot profit of integrated rebar improved from -179.79 yuan/mt before the holiday to -68.12 yuan/mt. Although steel mill profits have recovered, most mills remain loss-making, which is curbing raw material demand.
Chart: MMI 61% Port Spot Index
Source: SMM
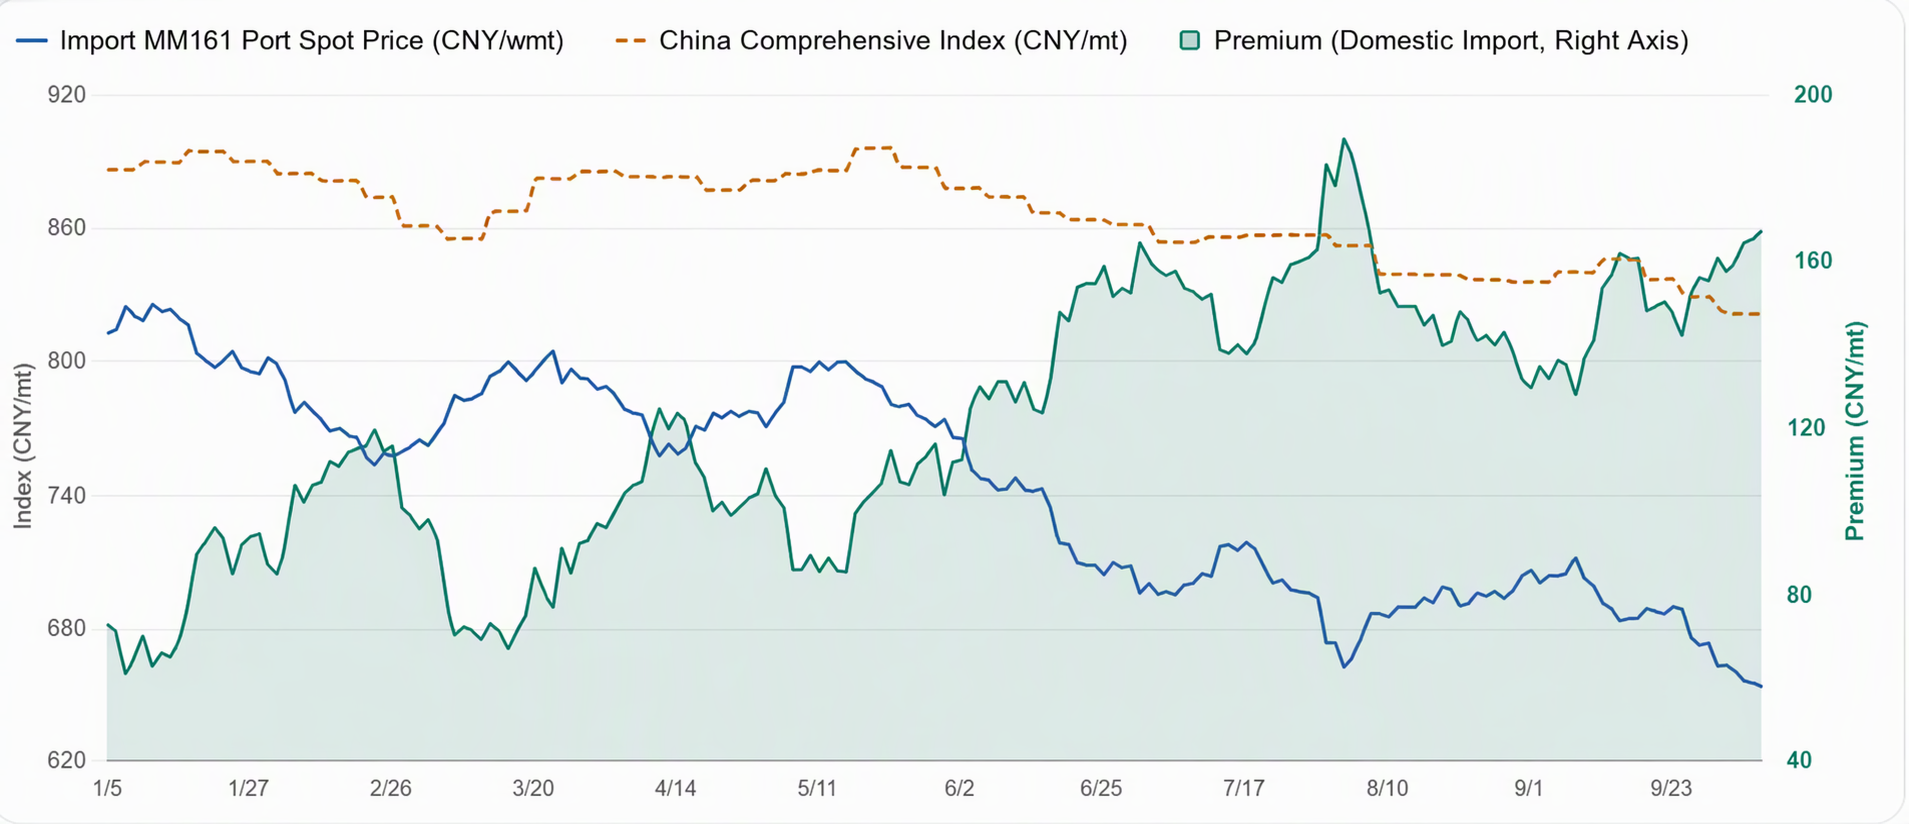
Chart: Imported ore fell more sharply, with the domestic-imported ore price spread continuing to widen
Outlook for next week
Outlook for next week, as steel mill profits recover and blast furnace maintenance winds down in stages, hot metal production is expected to hit bottom and rebound slightly, providing some support for ore prices. However, expectations for future supply growth remain strong, and mounting inventory pressure will continue to cap the upside, while falling ocean freight rates further weaken cost support. Overall, ore prices lack upward drivers and are expected to move sideways in the short term. In terms of trading, selling into rebounds is recommended as the main strategy, with close attention to steel demand and the sentiment impact from macro news.