According to the SMM survey, the MoM impact on refined lead production from secondary lead enterprises in China was approximately 25,700 mt in September 2026, with October expectations at approximately 24,900 mt, a slight narrowing of 800 mt in MoM growth. Overall, production resumptions by previously suspended or reduced enterprises remained the main theme on the supply side in September-October, but the momentum of resumptions marginally converged in October, with growth contributions continuing to concentrate in east China.
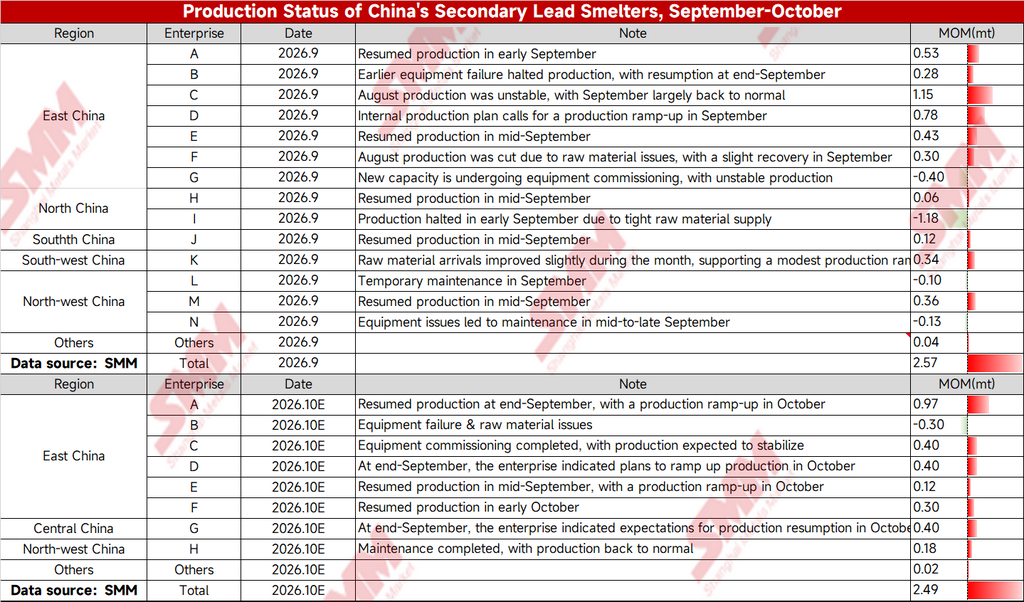
By region, east China was the core engine of this round of production resumptions. In September, seven enterprises in east China contributed a combined growth of approximately 30,700 mt. Among them, Enterprise 3 contributed 11,500 mt as production largely returned to normal in September after unstable output in August; Enterprise 4 executed internal production plans and ramped up production in September, contributing 7,800 mt; Enterprise 1 and Enterprise 5 resumed production in early and mid-September respectively, contributing a combined 9,600 mt. However, Enterprise 7 was affected by equipment commissioning for new capacity, with production still unstable, resulting in an offsetting reduction of 4,000 mt. In October, east China is expected to contribute 18,900 mt. Enterprise 1 is expected to continue ramping up production in October after resuming at end-September, contributing 9,700 mt in the month alone, while Enterprise 3 and Enterprise 4 are expected to achieve stable production after completing equipment commissioning, each contributing 4,000 mt.
North and north-west China presented a mix of production resumptions and disruptions. In north China, Enterprise 9 halted production in early September due to tight raw material supply, causing a reduction of 11,800 mt, the largest single reduction item in September; Enterprise 8 resumed production in mid-month, contributing only 600 mt. In north-west China, Enterprise 13 resumed production in mid-month, contributing 3,600 mt, but Enterprise 12's temporary maintenance and Enterprise 14's equipment-related maintenance brought reductions of 0.1 mt and 1,300 mt respectively. South and south-west China were relatively stable, contributing 0.12 mt and 3,400 mt respectively.
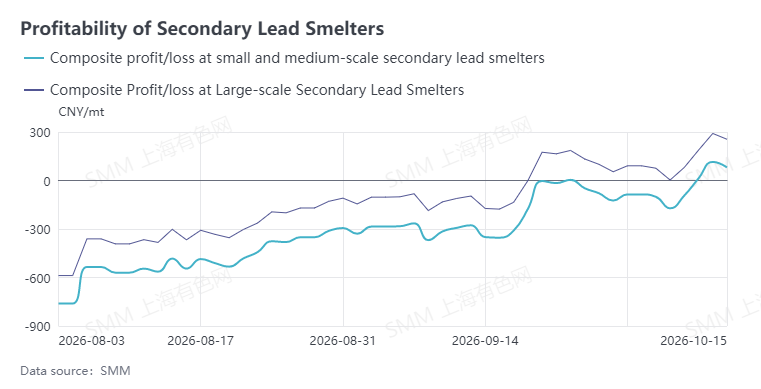
Price side, lead prices consolidated within the range of 15,700-16,300 yuan/mt in September, with secondary refined lead smelting profits fluctuating narrowly around the cost line. By-product revenues from waste lead slag, plastic fragments, and flue dust provided a partial buffer for profits. In October, if the pace of raw material arrivals remains tight, the pace of production resumptions and ramp-ups may be slower than expected; if lead prices can hold above 16,300 yuan/mt, enterprises' willingness to produce is likely to improve, and the growth in refined lead supply may approach more than 25,000 mt.