October 15, 2026
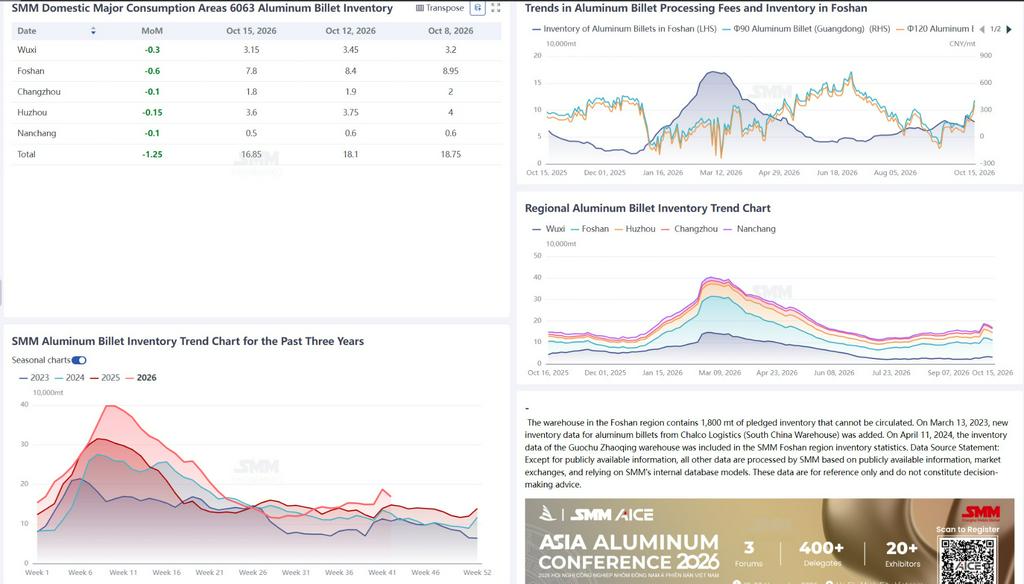
According to SMM statistics, aluminum billet inventory in major domestic consumption sites stood at 168,500 tonnes on October 15, down 19,000 tonnes from last Thursday and down 12,500 tonnes from this Monday, as post-holiday inventories retreated quickly from the seasonal high of 187,500 tonnes. Compared with the same period in previous years, inventory is about 21,000 tonnes higher than in 2025 and about 42,000 tonnes higher than in 2024, still the highest for the same period in four years. In terms of shipments, aluminum billet shipments reached 55,900 tonnes during September 28-October 11, holding steady over the two weeks and pointing to continued consumption resilience. By region, Foshan held 78,000 tonnes, down 11,500 tonnes from last Thursday and the main driver of the destocking; Huzhou held 36,000 tonnes and Changzhou 18,000 tonnes, down 4,000 tonnes and 2,000 tonnes respectively; Wuxi held 31,500 tonnes and Nanchang 5,000 tonnes, both broadly flat. The rapid destocking was driven by both supply and demand. On the demand side, downstream processors resumed production and picked up cargo after the holiday, while the sharp fall in aluminum prices revived buying interest, giving a strong boost to shipments. On the supply side, concentrated arrivals during the holiday gave way to a slower inflow pace afterwards, easing supply pressure for the time being.
Aluminum prices trended down during the week, with the SMM A00 aluminum spot price falling from RMB 23,760/t last Thursday to RMB 23,260/t this Thursday, a cumulative decline of about RMB 500/t. Against weaker aluminum prices, aluminum billet processing fees rebounded almost across the board. By region, Foshan quoted RMB 410/t for φ90 aluminum billet and RMB 360/t for φ120, both up RMB 210/t from last Thursday; Wuxi quoted RMB 540/t for φ90 and RMB 440/t for φ120, both up RMB 40/t; Nanchang quoted RMB 600/t for φ90 and RMB 550/t for φ120, both up RMB 220/t. The broad rebound in processing fees was driven by two factors: first, the sharp drop in aluminum prices strengthened producers' willingness to hold prices firm given their high-cost raw material inventories; second, the surge in shipments and recovering downstream buying sentiment provided support for higher fees. Processing fee trends next week will depend on the direction of aluminum prices and the sustainability of post-holiday restocking by downstream buyers.