SMM, October 15:
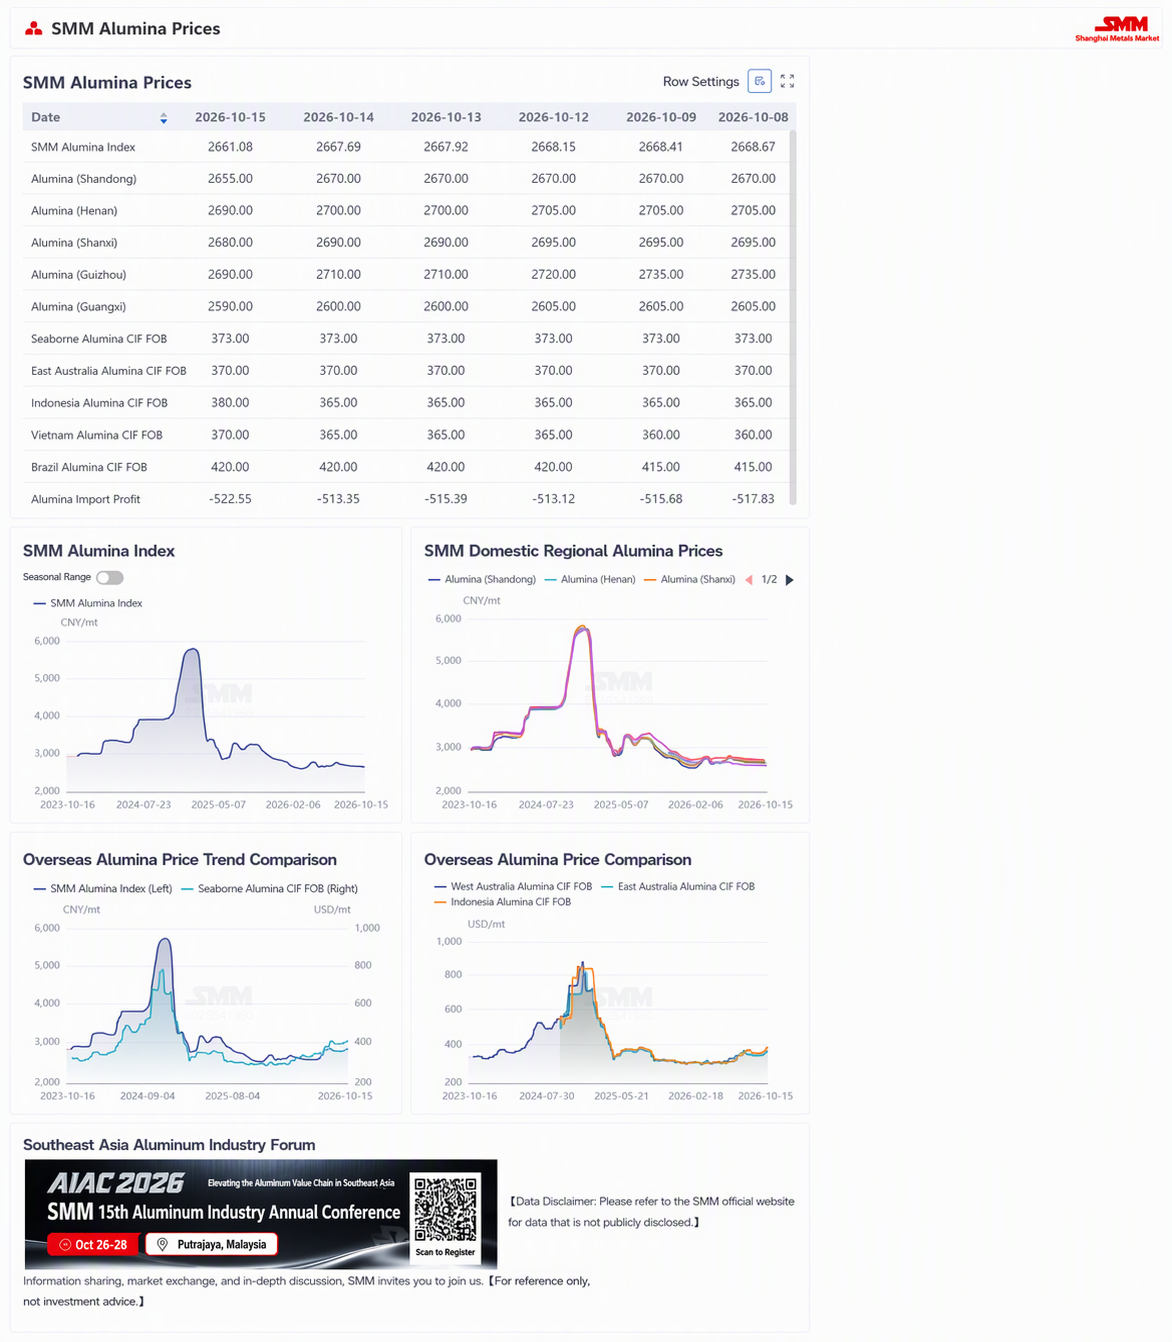
According to SMM data, as of Thursday this week, the SMM alumina index stood at 2,661.08 yuan/mt, down 7.59 yuan/mt WoW. By region, Shandong was at 2,620-2,690 yuan/mt, down 15 yuan from last Thursday; Henan was at 2,660-2,720 yuan/mt, down 15 yuan from last Thursday; Shanxi was at 2,650-2,710 yuan/mt, down 15 yuan from last Thursday; Guangxi was at 2,570-2,610 yuan/mt, down 15 yuan from last Thursday; Guizhou was at 2,660-2,720 yuan/mt, down 45 yuan from last Thursday.
Markets outside China: As of October 15, 2026, the FOB Western Australia alumina price was $373/mt, with an ocean freight rate of $36.35/mt and a USD/CNY selling rate around 6.71. This translates to a delivered price at major Chinese ports of approximately 3,183.63 yuan/mt, 522.6 yuan/mt above the alumina index price. Three overseas spot alumina transactions were reported this week, as follows:
(1) On October 1, 2026, 30,000 mt of alumina was traded overseas at $380/mt FOB Eastern Australia, for December shipment.
(2) On October 9, 2026, 30,000 mt of alumina was traded overseas at $387/mt FOB Western Australia, for November shipment.
(3) On October 9, 2026, 30,000 mt of alumina was traded overseas at $426/mt FOB Brazil, for November shipment.
According to SMM data, as of Thursday this week, China's total built metallurgical-grade alumina capacity was 119.62 million mt/year, with operating capacity at 93.11 million mt/year. The national weekly metallurgical-grade alumina operating rate rose 0.17 percentage points WoW to 77.84%. By region, Shandong's weekly alumina operating rate was flat WoW at 85.44%; Shanxi's weekly alumina operating rate was flat WoW at 74.24%; Henan's weekly alumina operating rate was flat WoW at 54.83%; Guangxi's weekly alumina operating rate rose 0.76 percentage points WoW to 84.65%; Guizhou's weekly alumina operating rate was flat WoW at 84.50%.
In the spot market, two transactions were concluded this week. Xinjiang purchased 10 kt of spot alumina at a delivered price of 2,960 yuan/mt. Qinghai purchased 30,000 mt of alumina at a delivered price of 2,890 yuan/mt.
This week, China's total alumina inventory increased by 47,500 mt WoW to 7.4829 million mt, extending the overall accumulation trend. By segment, raw material inventory at aluminum smelters rose by 17,500 mt to 3.59 million mt, as downstream winter stockpiling willingness gradually picked up; finished product inventories at alumina refineries rose by 26,000 mt to 1.3499 million mt, continuing to accumulate amid high production levels; port inventory edged down by 16,000 mt to 878,000 mt, maintaining the destocking trend as cargo continued shifting to plant sites and in-transit channels; in-transit and platform stockpiled inventory rose by 20,000 mt to 1.431 million mt, as post-holiday shipment pace recovered and boosted cargo in transit; warrant inventory edged down to 234,000 mt, remaining basically stable overall. Industry-wise, national weekly alumina production this week was 1.786 million mt, up 4,000 mt WoW, with the growth mainly from the continued release of new capacity in Guangxi. Overall supply stayed high and continued to edge up. Futures prices have fallen notably recently, overall market sentiment is weak, and futures prices have plunged. Looking ahead, futures prices are expected to remain low. Looking ahead, no maintenance or production cut plans have been heard from enterprises so far, and supply pressure is expected to keep increasing. On the inventory side, high production and the gradual release of winter stockpiling demand are offsetting each other, and national alumina total inventory is expected to continue a mild inventory buildup trend. On the price side, the supply-demand surplus pattern remains unchanged, upward drivers are weak, and spot prices are expected to keep falling.
[All data other than public information are processed by SMM based on public information, market communication, and SMM's internal database models, for reference only and do not constitute decision-making advice.]