Cast aluminum midday gains 0.67%, cost support pushes ADC12 center slightly higher [ADC12 Price Daily Review]

Published: Oct 12, 2026 14:24 (GMT+8)
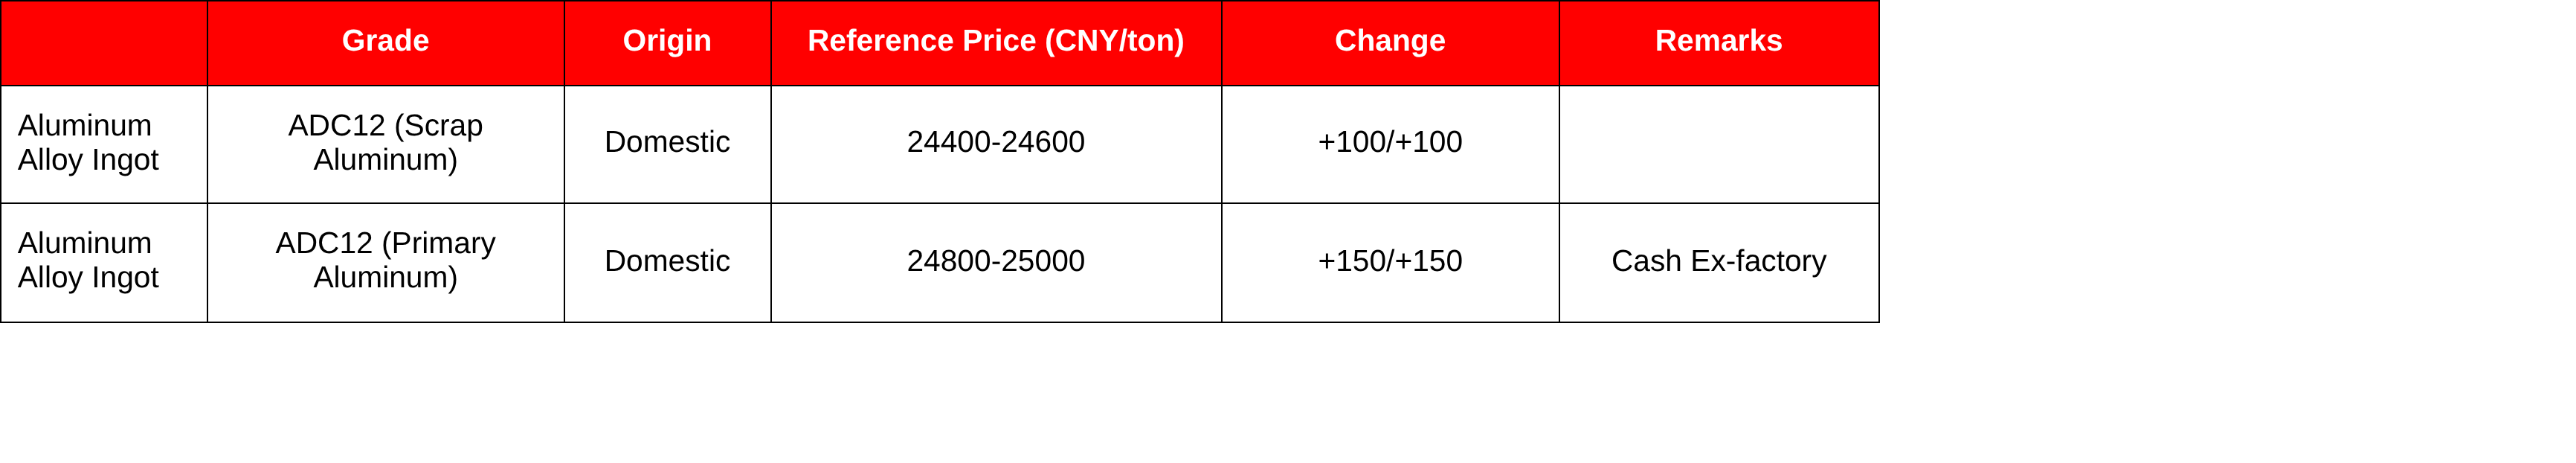
[ADC12 Price Daily Review: Die-cast aluminum closed up 0.67% at midday; cost support nudges ADC12 center slightly higher] The ADC12 market center edged up slightly today. SMM ADC12 price rose 100 yuan/mt from the previous day to 24,500 yuan/mt. Cost side, higher aluminum and copper prices pushed up procurement costs for aluminum scrap and copper alloy elements. Combined with ongoing invoice issues constraining compliant raw material procurement, enterprises still face cost pressure, providing strong support for ADC12 prices and leaving limited downside in the short term.

Futures: The most-traded AD2612 cast aluminum alloy futures contract opened at 23,370 yuan/mt today, dipped to 23,300 yuan/mt after the open before quickly rallying, shot up to 23,465 yuan/mt in early trading where it met resistance, consolidated at highs before pulling back step by step, dipped to 23,315 yuan/mt on heavier volume where it stabilized, rebounded in late trading, and closed at 23,355 yuan/mt in the midday session, up 155 yuan/mt, or 0.67%, from yesterday's settlement price of 23,200 yuan/mt.

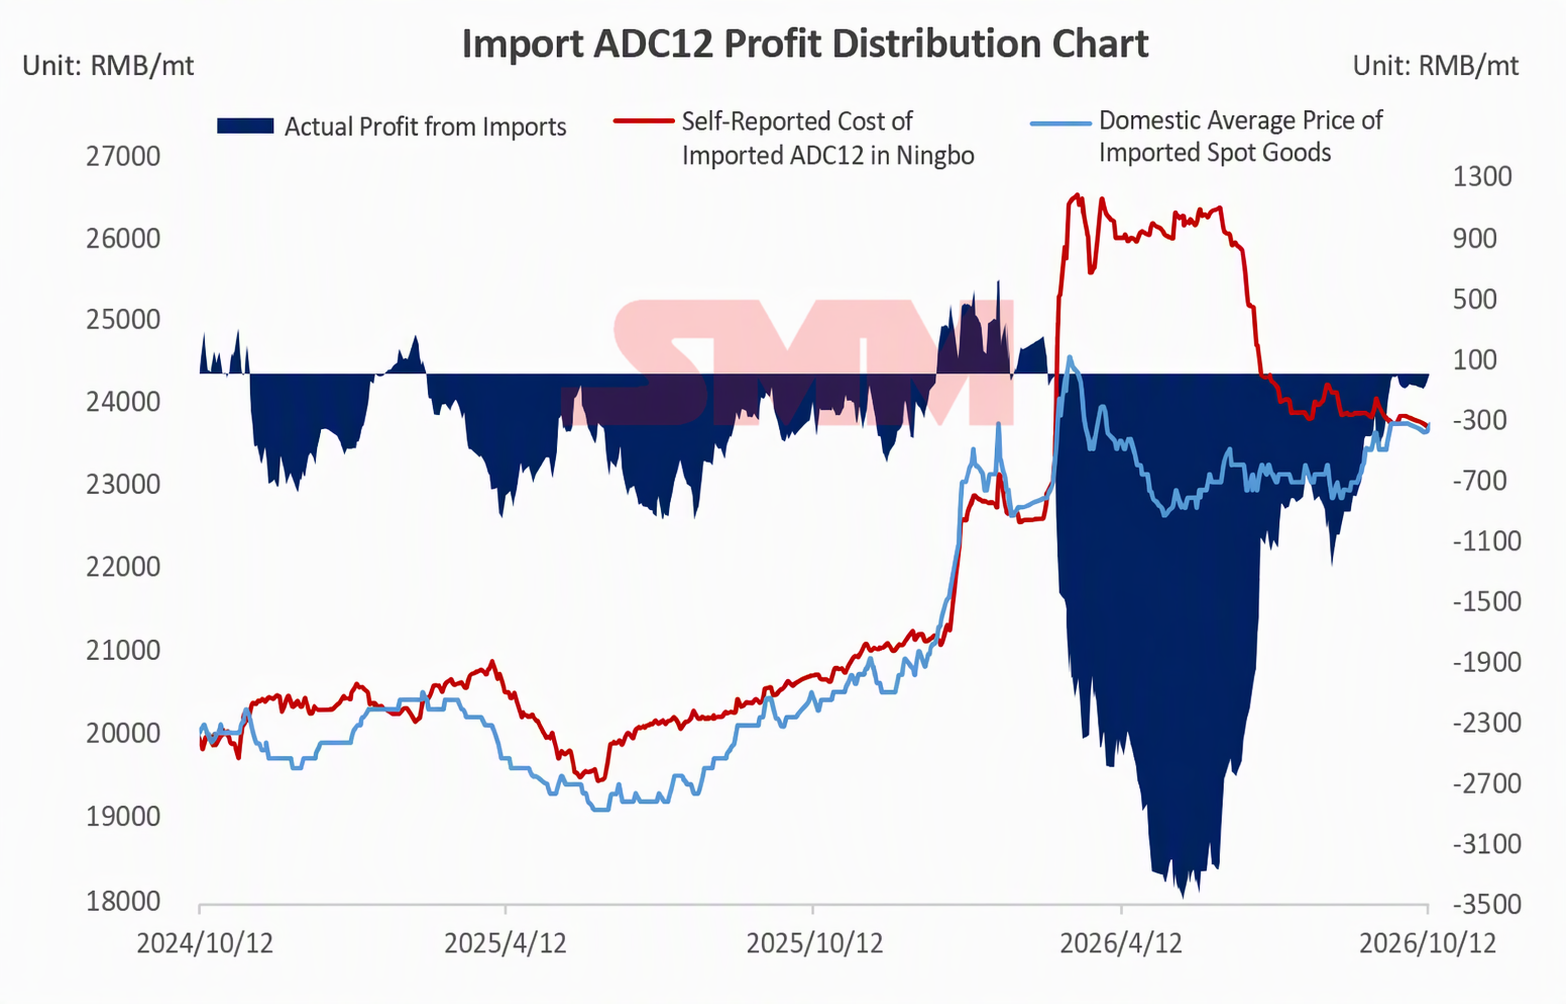
Spot: The ADC12 market center moved slightly higher today, with SMM ADC12 prices up 100 yuan/mt from the previous day to 24,500 yuan/mt. Cost side, higher aluminum and copper prices pushed up procurement costs for aluminum scrap and copper alloy elements, while tax invoice issues continued to constrain compliant raw material procurement, leaving enterprises under persistent cost pressure that provides relatively strong support for ADC12 prices and limits near-term downside. Demand side remained weak, with demand release during the traditional September-October peak season falling short of expectations, constraining the sustainability of price rises. Overall, the ADC12 market currently features strong cost support and insufficient demand follow-through, with the conflict between the willingness to hold prices firm and downstream affordability still present. Prices are expected to move sideways in the near term, with further upside dependent on aluminum price trends, raw material cost changes, and actual downstream procurement.
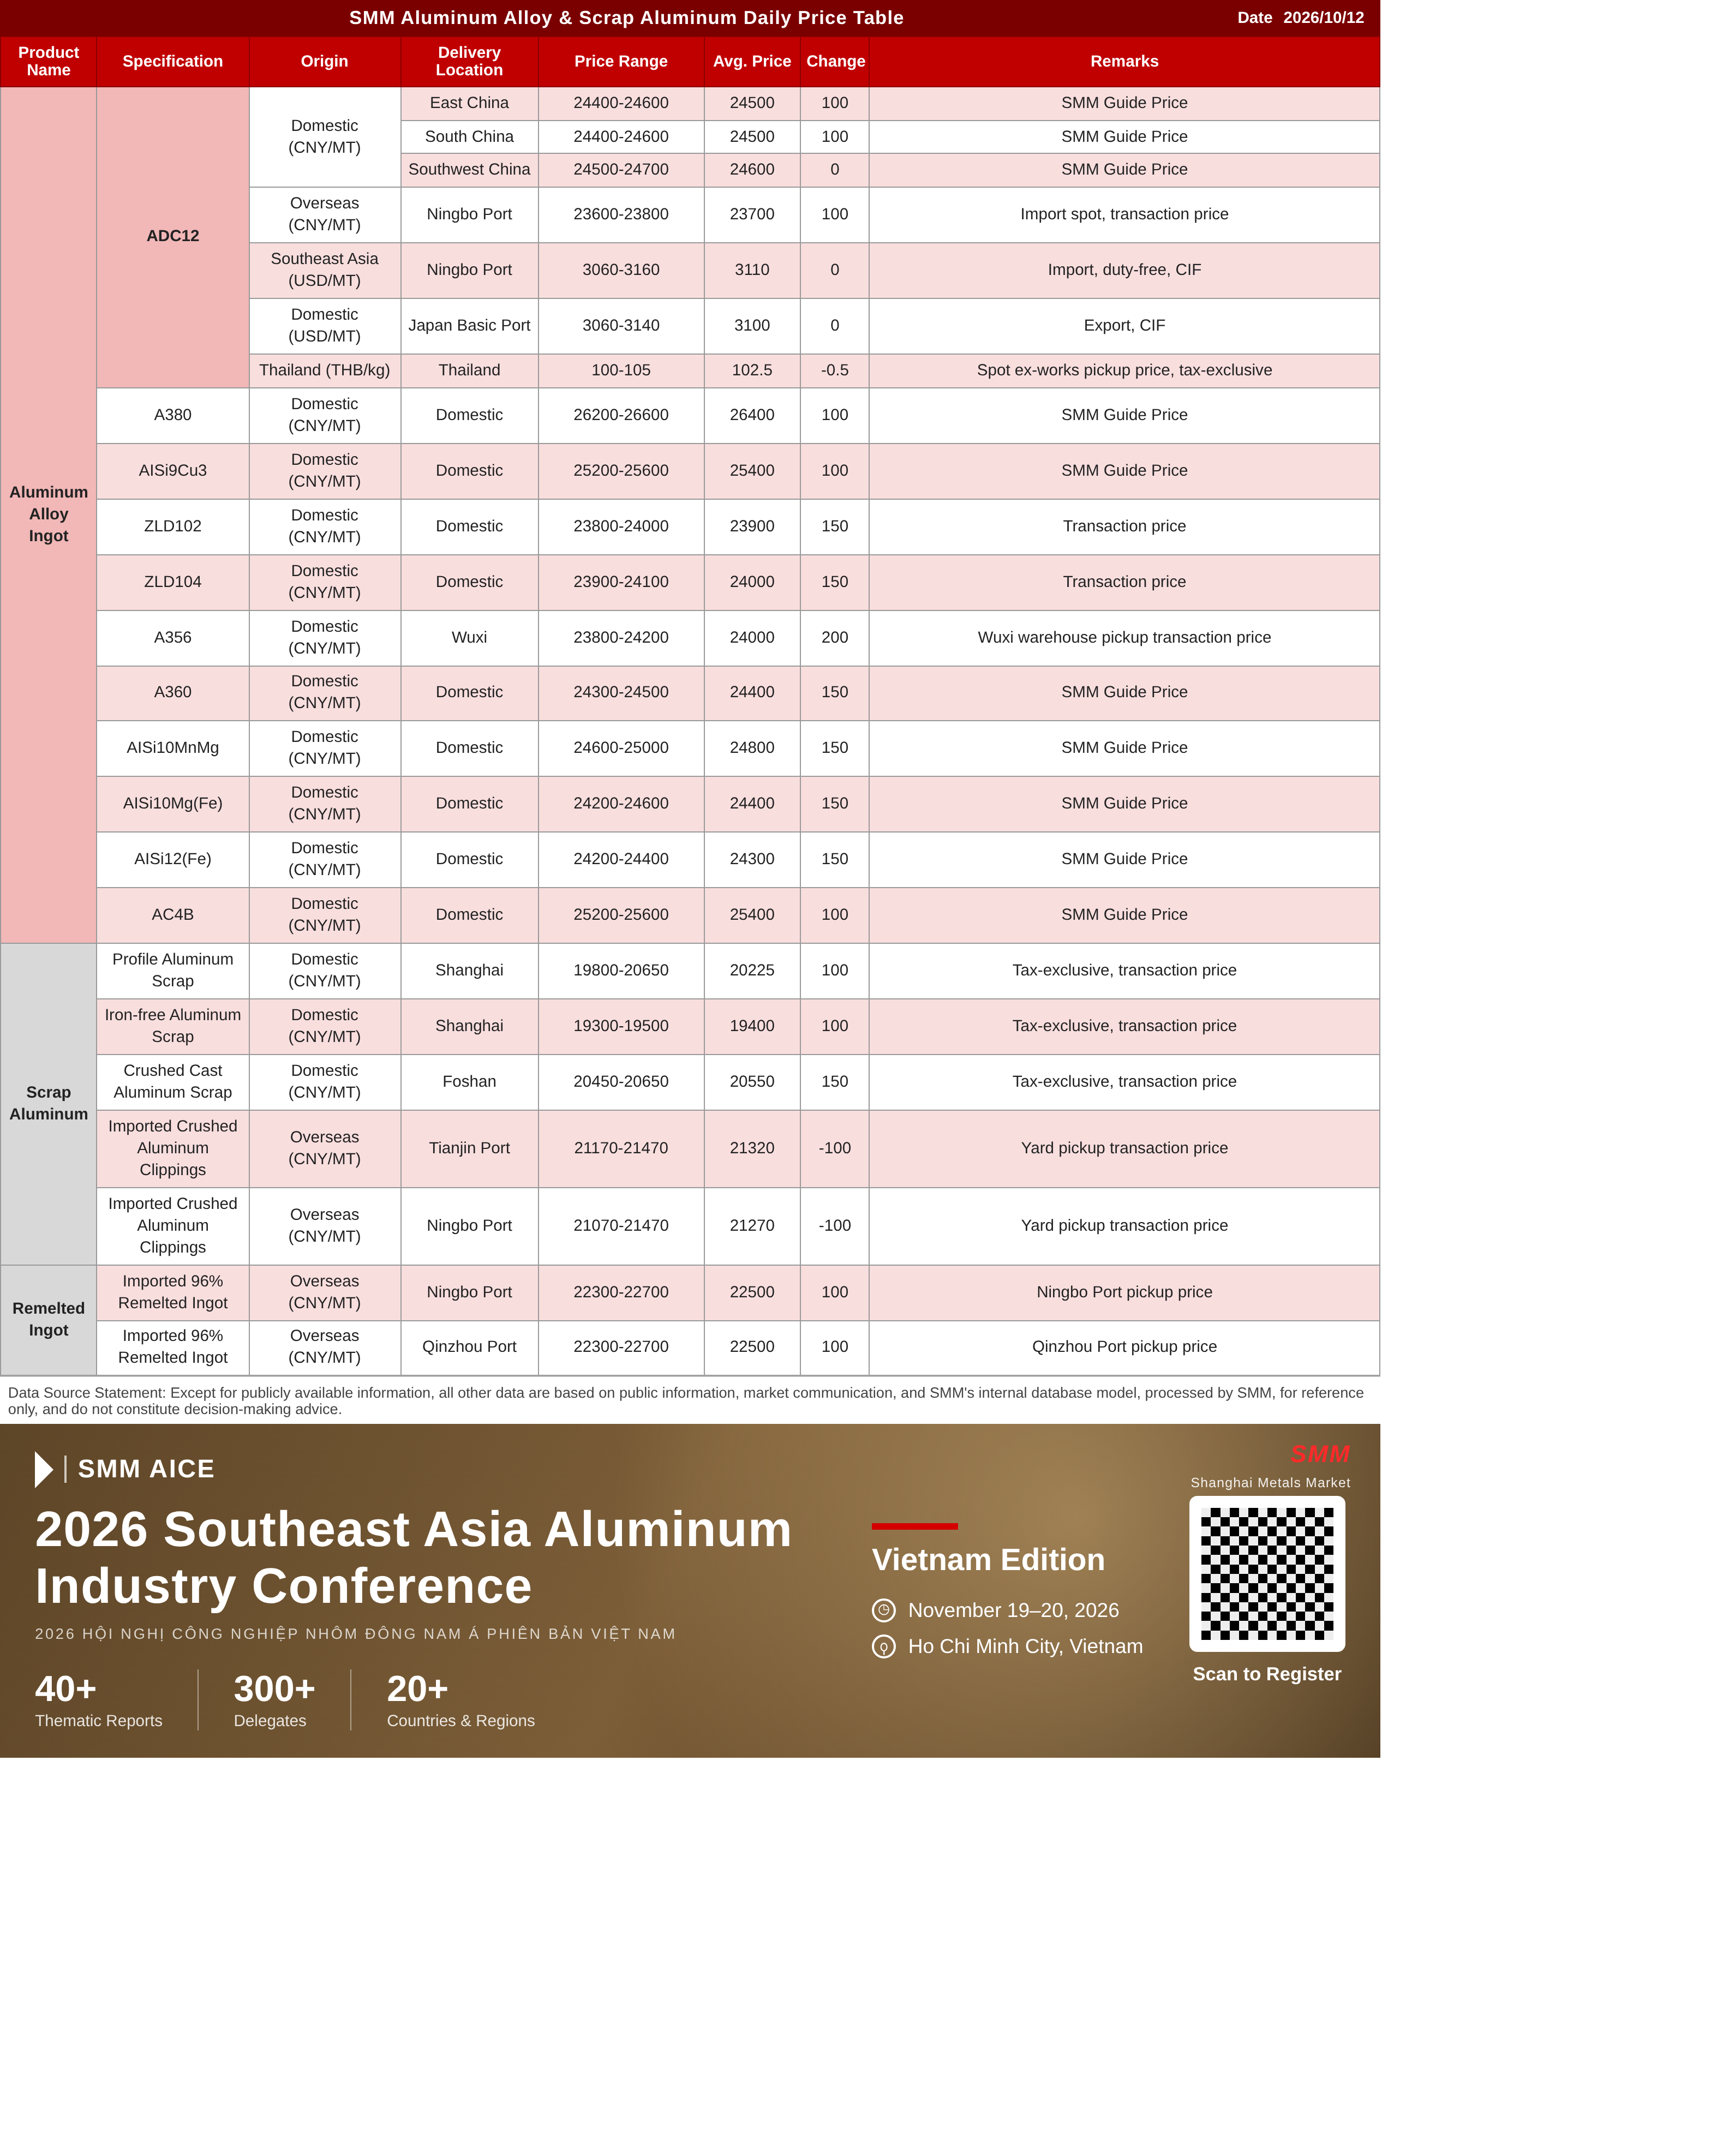


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Chromium Flash] Global Chrome Ore Departures Surge 32.16% WoW to 849,100 mt, Richards Bay Leads Gains
19 mins ago
[SMM Chromium Flash] Global Chrome Ore Departures Surge 32.16% WoW to 849,100 mt, Richards Bay Leads Gains
Read More
[SMM Chromium Flash] Global Chrome Ore Departures Surge 32.16% WoW to 849,100 mt, Richards Bay Leads Gains
[SMM Chromium Flash] Global Chrome Ore Departures Surge 32.16% WoW to 849,100 mt, Richards Bay Leads Gains
Global chrome ore departures totaled 849,100 mt in the week ended October 9, up 32.16% week-on-week, according to SMM’s latest data. This is the highest weekly volume among the past 10 weeks of data, ahead of the 717,000 mt recorded in the week ended August 7. Unlike recent weeks, the increase was not driven by Maputo, as three of the four tracked ports posted gains while Maputo moved lower. Richards Bay led the rebound, with departures rising 182.76% to 270,600 mt from 95,700 mt, lifting its share of total departures to roughly 32% from about 15% a week earlier. The sharp swing, following a 57.99% decline the prior week, reinforces the intermittent, batch-driven loading pattern seen at the port in recent weeks. Mersin also climbed 92.24% to 111,500 mt from 58,000 mt, its highest weekly volume over the same period. Beira resumed shipments with 34,400 mt after four consecutive weeks of zero departures, its second active week in the series. Maputo departures eased 11.50% to 432,600 mt from 488,800 mt, and its share of total departures narrowed to roughly 51% from about 76% the previous week. The port nonetheless remained the largest single corridor, with volumes still well above the 340,200 mt recorded in the week ended September 25. Overall, the week’s data points to a broader distribution of seaborne chrome ore flows from Southern Africa, with the strength in total departures coming from the secondary ports rather than from Maputo. Whether Richards Bay and Mersin can sustain these elevated volumes will be a key factor for regional shipment levels in the weeks ahead.
19 mins ago
Baiyin Nonferrous Group Completes Tender Sale of 220 Tonnes of Crude Cadmium Amid Strong Market Demand
3 hours ago
Baiyin Nonferrous Group Completes Tender Sale of 220 Tonnes of Crude Cadmium Amid Strong Market Demand
Read More
Baiyin Nonferrous Group Completes Tender Sale of 220 Tonnes of Crude Cadmium Amid Strong Market Demand
SMM News, October 12: SMM has learned that Northwest Lead‑Zinc Smelter of Baiyin Nonferrous Group completed the successful public tender sale of approximately 220 tonnes of crude cadmium over the past weekend. According to official information, the transaction price was concluded at a small discount to SMM average price for 1# cadmium. Market participants commented that given the recent strong cadmium prices, the completed tender at a firm price reflects robust market demand.
3 hours ago
【Flash | USGS Revises U.S. H1 Molybdenum Output Lower】
6 hours ago
【Flash | USGS Revises U.S. H1 Molybdenum Output Lower】
Read More
【Flash | USGS Revises U.S. H1 Molybdenum Output Lower】
USGS revised U.S. molybdenum concentrate production for April-June 2026 from 3,470, 3,650 and 3,510 tonnes to 3,420, 3,610 and 3,480 tonnes, respectively, cutting the three-month total by 120 tonnes. Based on the revised monthly data, SMM calculates H1 output at about 20,900 tonnes, versus 21,100 tonnes previously reported. Part of the 200-tonne displayed difference reflects USGS rounding. H1 output nevertheless remained about 4% higher YoY.
6 hours ago
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here