September silicon metal production fell 11% MoM; Q4 production is expected to weaken significantly YoY [SMM Analysis]

Published: Oct 10, 2026 11:00 (GMT+8)
[September silicon metal production down 11% MoM; Q4 production expected to weaken significantly YoY] According to SMM data, silicon metal production in September was 317,000 mt, down 11.0% MoM and down 24.7% YoY. Cumulative silicon metal production in January-September 2026 was 3.052 million mt, up 1% YoY.
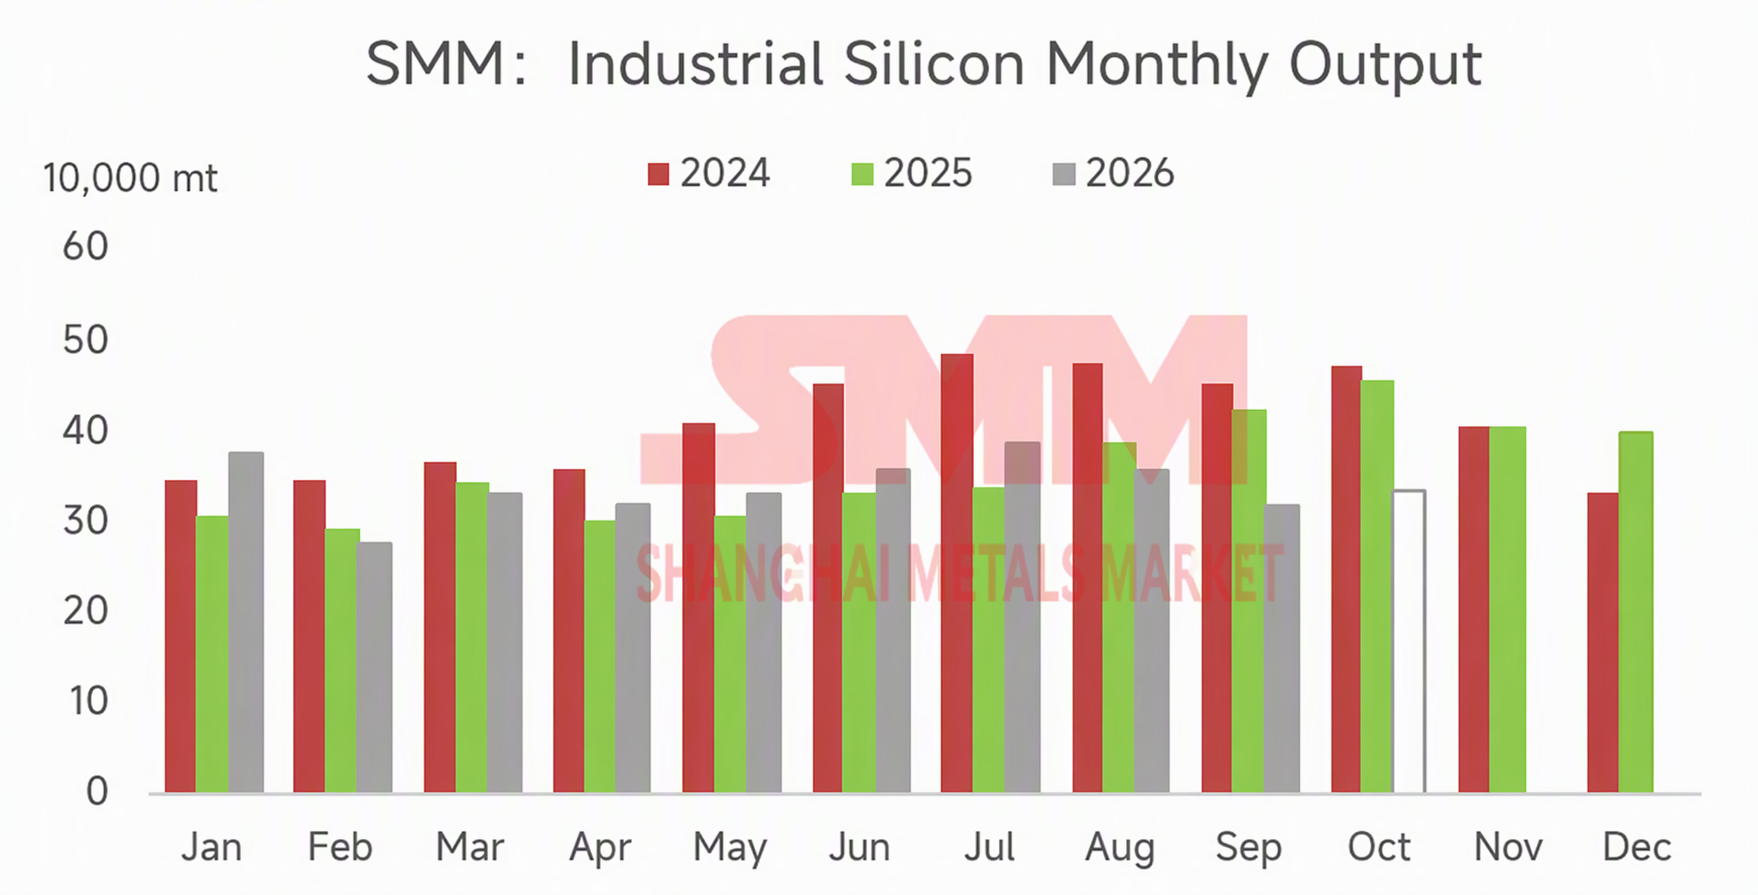
According to SMM data, silicon metal production in September was 317,000 mt, down 11.0% MoM and down 24.7% YoY. Cumulative silicon metal production in January-September 2026 was 3.052 million mt, up 1% YoY.

In September, silicon enterprises in different regions saw mixed production changes, with Xinjiang posting the largest decline. Silicon metal production in Xinjiang fell 26% MoM in September, a reduction of around 55,000 mt. Production in Gansu and Inner Mongolia rose 76% and 25% MoM respectively, with combined growth of 17,000 mt across the two regions. In addition, Sichuan and other regions saw minor production fluctuations. Overall, September production declined MoM.

In October, production growth in northern regions mainly reflects the full-month output of capacity that resumed production in September. New production resumptions in the north are limited in October, and large plants in Xinjiang have no production resumption plan for October. In southern regions, operating rates are expected to weaken starting in October. From late October, Sichuan and Yunnan will gradually enter the dry season. Rising electricity prices, coupled with higher raw material prices such as silicon coal and petroleum coke, will push up production costs for silicon enterprises. In early October, a few silicon enterprises in Sichuan and Yunnan cut production, and most plan to cut or halt production in late October or at month-end. In addition, October has one more production day than September. Taking all factors into account, silicon metal production in October is expected to edge up around 5% MoM.

Looking back at 2025, the highest monthly production was 452,000 mt in October. This year's peak was 388,000 mt in July, mainly because operating rates in Sichuan and Yunnan during the rainy season fell YoY, combined with high H1 operating rates and weakening H2 operating rates at northern silicon enterprises. As a result, silicon metal production in H2 2026 was flat to slightly lower than H1, and Q4 silicon metal production is expected to see a significant YoY decline.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Germanium Prices Stable Post-Holiday, Ingot and Dioxide Remain Unchanged at 27,250 and 19,250 Yuan/kg
3 hours ago
Germanium Prices Stable Post-Holiday, Ingot and Dioxide Remain Unchanged at 27,250 and 19,250 Yuan/kg
Read More
Germanium Prices Stable Post-Holiday, Ingot and Dioxide Remain Unchanged at 27,250 and 19,250 Yuan/kg
The supply-demand balance remains unchanged, and germanium prices continue to fluctuate on a firm footing. Germanium ingot (50Ω/cm) is quoted at 27,250 yuan/kg, and germanium dioxide (99.999%) at 19,250 yuan/kg; both prices are flat compared with the pre-holiday level, with no price adjustments in the two trading days after the holiday. Previously on September 24, germanium ingot and germanium dioxide were raised by 250 yuan/kg and 100 yuan/kg respectively. The market has entered a phase of high-level digestion after the holiday.
3 hours ago
Rwanda spot offers at “4.8+” leave one buyer waiting
14 hours ago
Rwanda spot offers at “4.8+” leave one buyer waiting
Read More
Rwanda spot offers at “4.8+” leave one buyer waiting
[SMM Tantalum Flash] A trading contact said on 9 October that it was still receiving Rwandan tantalum offers at “4.8+” and had bought no tantalum in the preceding few weeks. Other contacts in the supplied sample described offers above US$4 per kg per grade percentage point. The “4.8+” message did not restate its pricing unit, assay, delivery basis or the dates of the underlying offers. It is a received asking indication, not a transaction price. The contact said its Rwanda tin flows remained stable, but it had held off buying tantalum while considering air-freight economics and had shifted more attention to West Africa. It reported a Nigerian offer and expressed interest in a Sierra Leone trader; neither was described as a completed tantalum purchase. These conversations show how one buyer is responding to the offers, without establishing a representative Rwanda price or a wider change in trade flows.
14 hours ago
DRC coltan spot sample received at US$60/kg for 38% material
14 hours ago
DRC coltan spot sample received at US$60/kg for 38% material
Read More
DRC coltan spot sample received at US$60/kg for 38% material
[SMM Tantalum Flash] A trader quotation recorded on 2 October in the supplied survey lists DRC-origin coltan described as 38% Ta₂O₅ at US$60,000 per tonne, or US$60/kg. The sheet marks it CIF, names Dar es Salaam as the origin port and leaves the destination blank. The same trader mentioned US$43/kg for material spanning 6–35% grade. These are two received asking indications from one trader; the survey provides no accepted order or completed-trade evidence. At the stated 38% grade, US$60/kg calculates to about US$1.58 per kg per grade percentage point. A separate 9 October conversation described traders sourcing from the DRC and routing material through Zambia towards Dar es Salaam, but did not link a shipment to this quoted lot. Assay, quantity and delivery terms still need checking. This small survey sample does not establish a DRC-wide price or a price movement.
14 hours ago
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here

