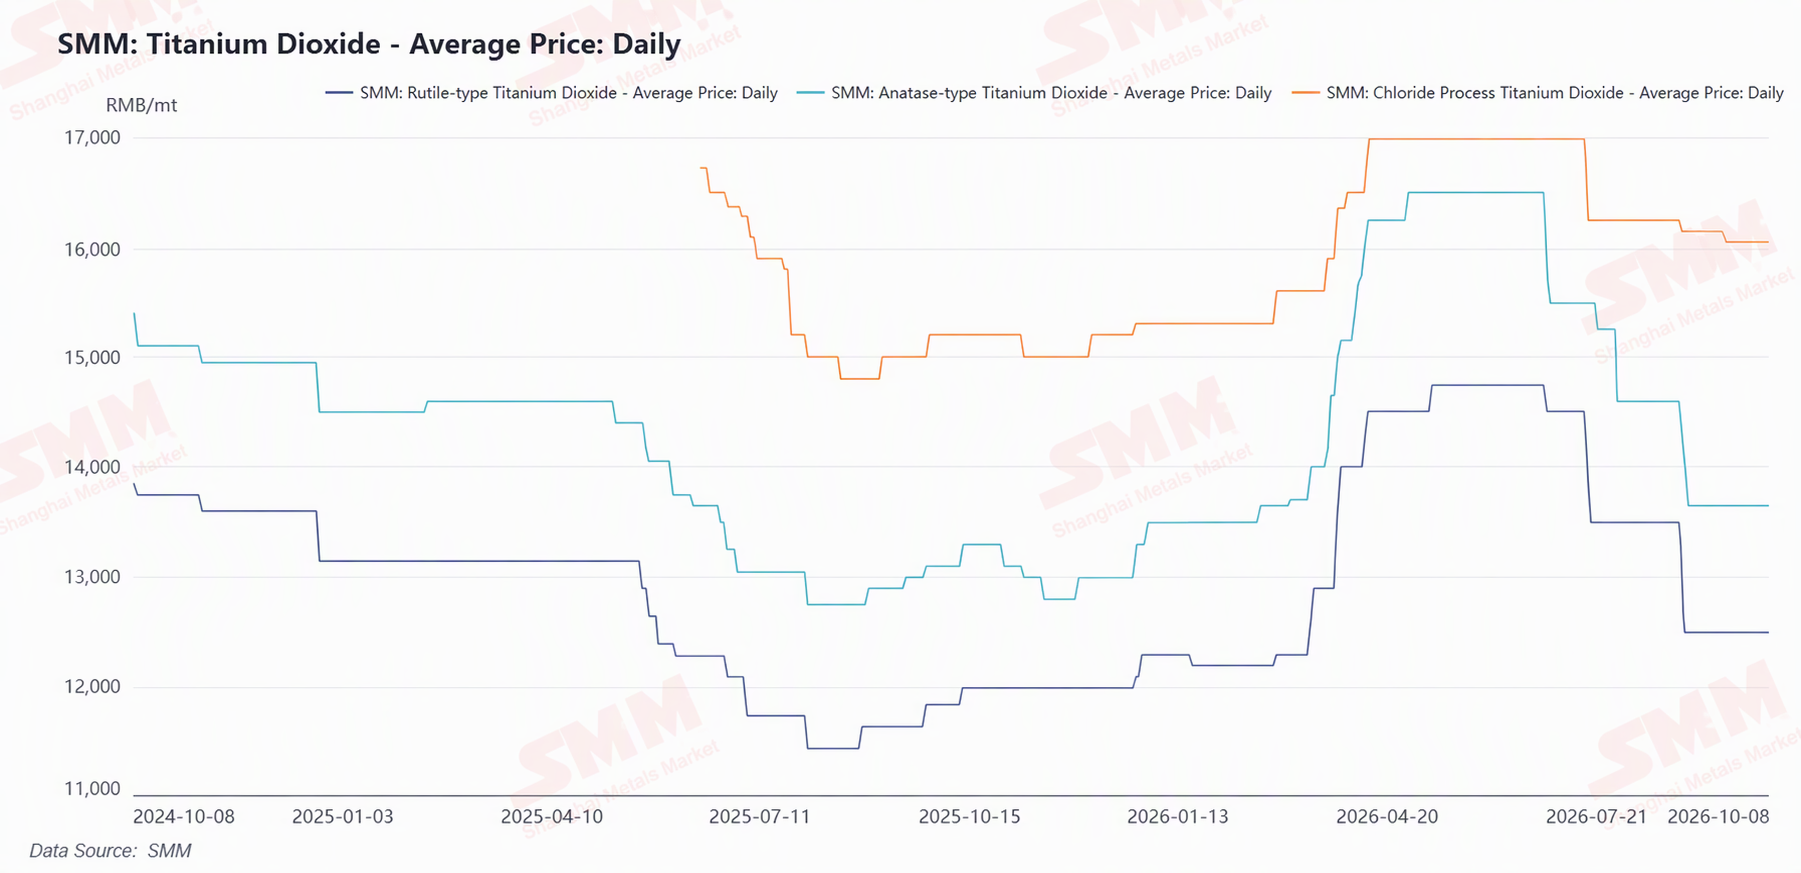
During the National Day holiday, China's titanium market remained stable overall but under pressure. Upstream titanium ore was in the doldrums and stagnant, with the supply-demand imbalance becoming more pronounced. Titanium sponge remained under pressure, with enterprises maintaining high operating rates, but downstream civil end-use demand was weak, industry inventory buildup intensified, and mainstream transaction prices for grade 0 titanium sponge were 44,000-45,000 yuan/mt. The titanium dioxide sector held steady before the holiday, with price spreads between products of different processes relatively stable: mainstream quotations for sulphate-process rutile type were 12,500-14,800 yuan/mt, sulphate-process anatase type 12,000-13,000 yuan/mt, while chloride-process titanium dioxide trended relatively firm, with mainstream quotations at 15,300-16,800 yuan/mt. On the first trading day after the holiday, quotations for titanium products across the entire industry chain extended pre-holiday levels, with no significant change, and market wait-and-see sentiment was strong. The market direction remains to be validated by actual downstream procurement orders after the holiday.
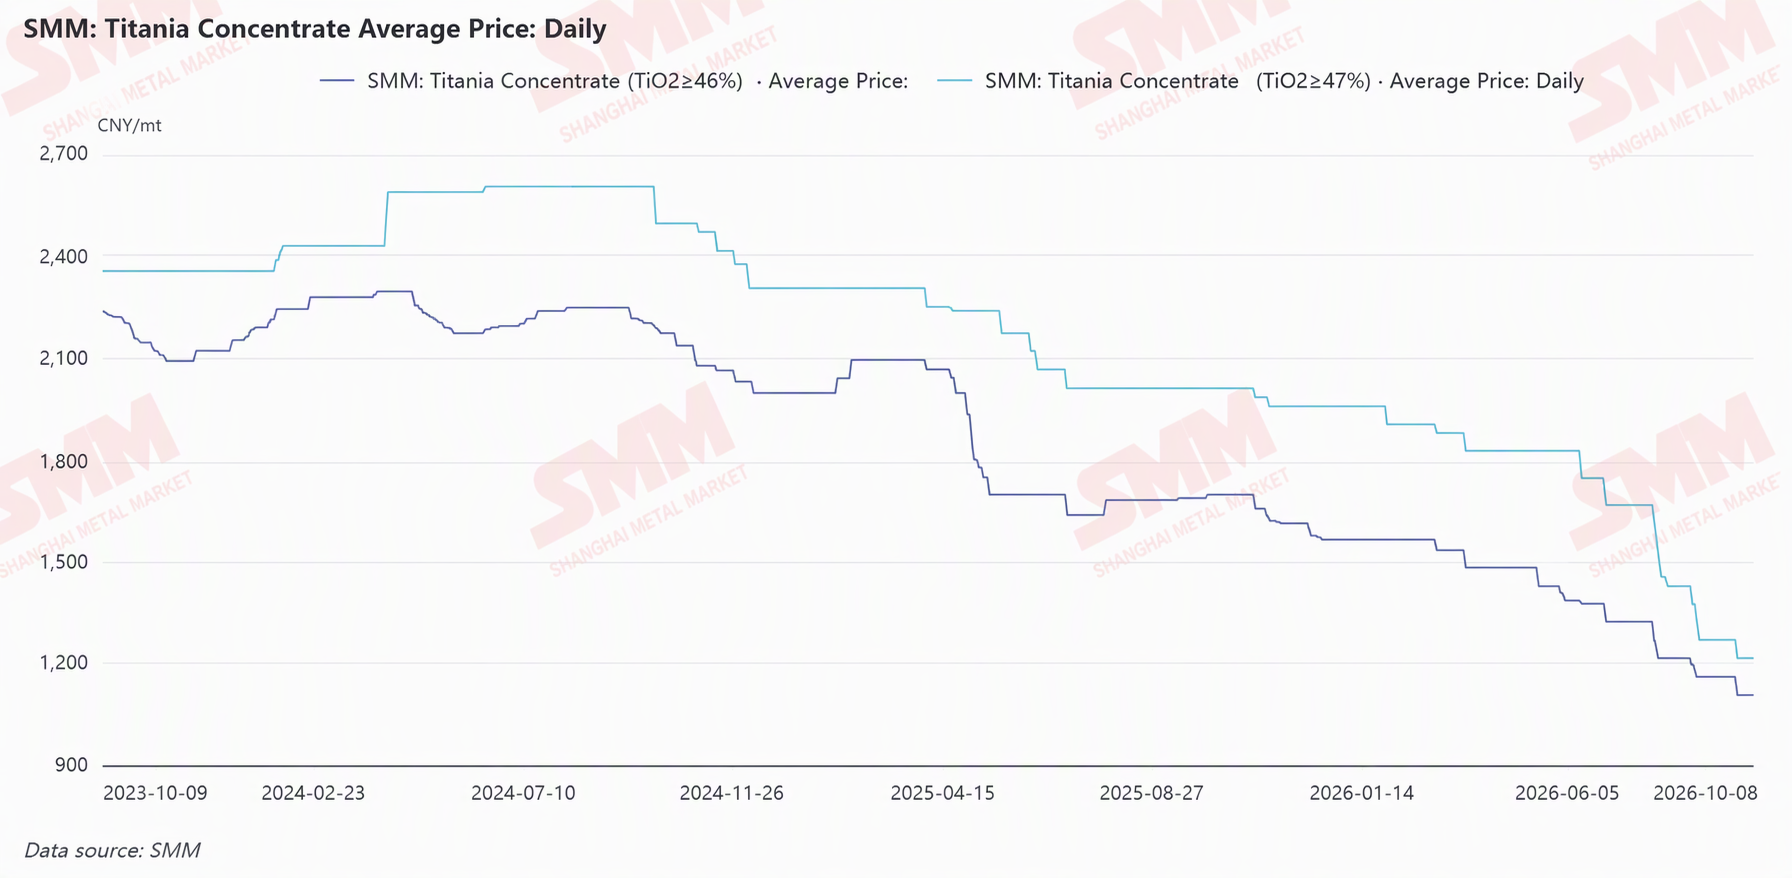
Raw material side, domestic titanium ore mines were generally loss-making, with overall operating rates low, but production growth in Xinjiang was significant, and combined with large arrivals of imported ore, market supply was generally ample. Sulphur and sulphuric acid markets were under pressure and consolidating, and the raw material side struggled to provide strong cost support for the titanium industry chain.
On the first day after the holiday, the titanium market extended its pre-holiday trend. The "September peak season" expectations fell through, and the market turned more cautious about the "October peak season." Given the weak raw material support and soft domestic downstream demand, whether the titanium market can see a turnaround will depend on marginal changes driven by exports and macro policies.
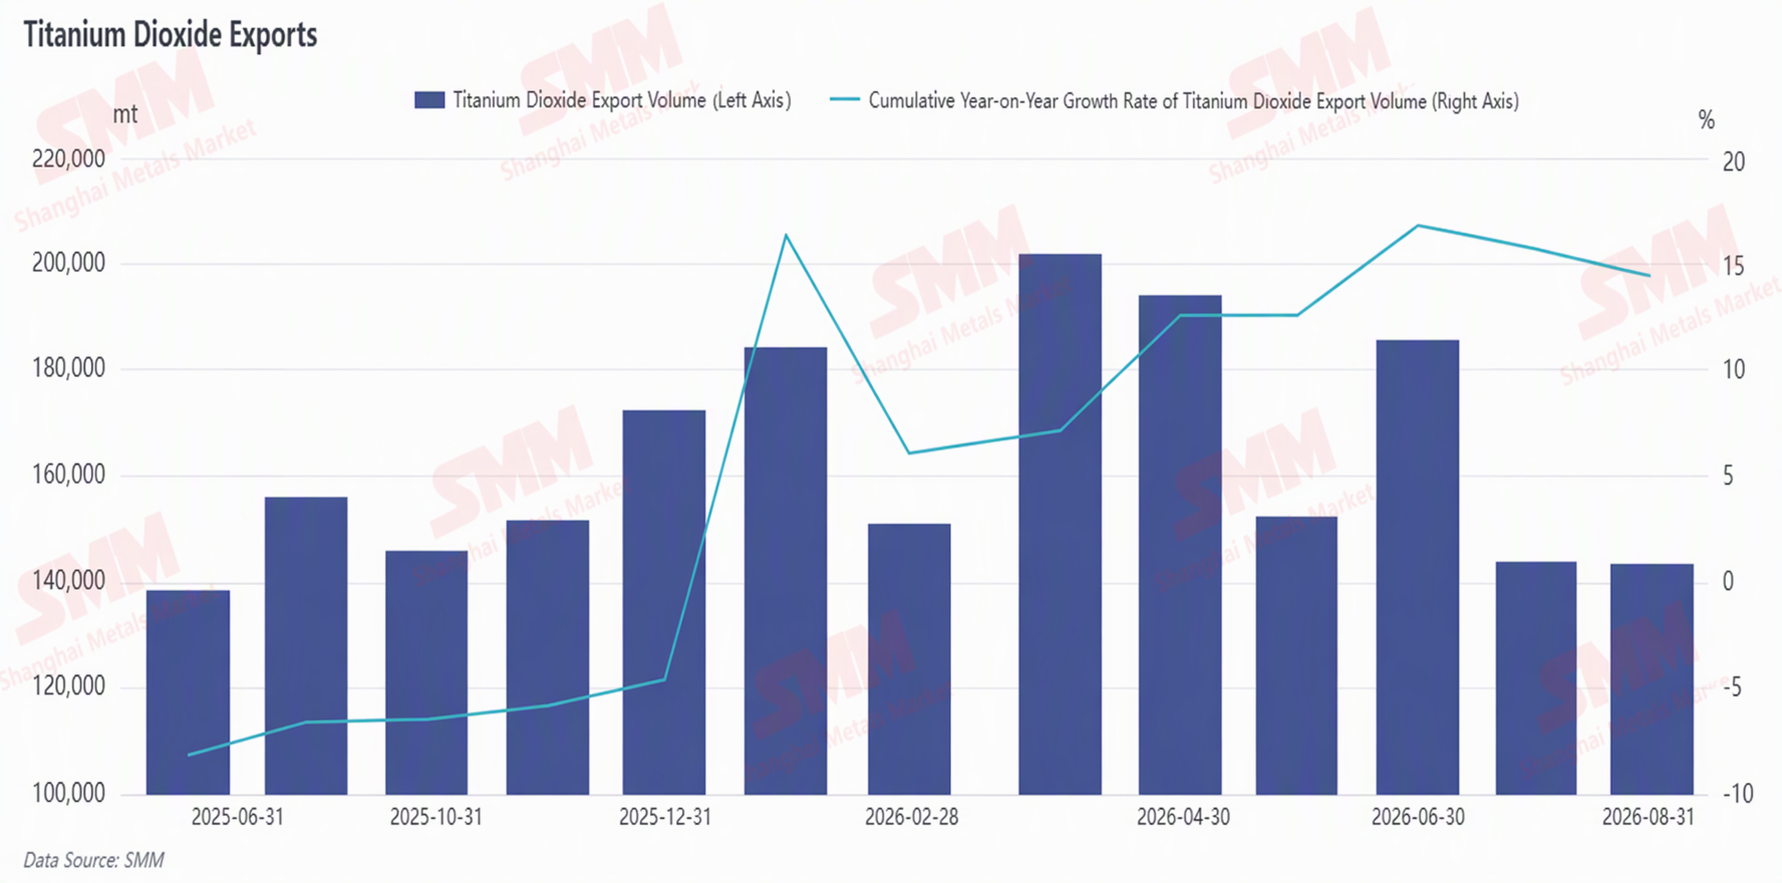
On the export front, there are structural positives: During the National Day holiday, Shandong Jinhai Titanium ran at full capacity to fulfill export orders, with daily production of 700-800 mt and exports of about 1,000 mt/day, providing phased support from export orders. Titanium material prices in Northwest Europe rose more than 3%, benefiting from recovering aerospace and national defense demand, and expectations for high-end titanium materials outside China are improving. From January to August 2026, China's cumulative titanium dioxide exports reached 1.357 million mt, up 14.02% YoY. As the titanium dioxide market recovers, exports are the core direction to watch. However, there are also disruptions on the export side. In August, titanium dioxide exports were 144,100 mt, down 0.21% MoM, with external demand marginally weakening. The EU, Brazil, and the UK maintained anti-dumping policies, export space remained constrained, and growth in a single market was difficult to fully offset the shortfall in domestic demand.
On the macro policy front: On September 21, the Eurasian Economic Commission decided to suspend anti-dumping measures on Chinese titanium dioxide, effective until August 10, 2027. Russian domestic titanium dioxide enterprises proactively applied for the suspension of duties after production constraints in June, opening the export channel to Russia. In August, Russia became China's second-largest export destination for titanium dioxide, accounting for 7.89%. Starting October 1, the resident home purchase loan interest subsidy policy took effect, targeting rigid demand in second- and third-tier cities. If housing deliveries accelerate, post-completion home improvement demand is expected to improve marginally, and titanium dioxide, as a raw material linked to the completion chain, has expectations of demand recovery.
Market outlook: The current titanium market is in a bottom-consolidating pattern characterized by weak cost support, ample supply, and weak end-use demand. The suspension of Eurasian anti-dumping measures, the mortgage interest subsidy policy, and incremental export orders are short-term positives, while the titanium ore supply-demand imbalance, continued titanium sponge inventory buildup, and slow end-use demand recovery remain core suppressing factors. After the holiday, the market is likely to remain in a "limited downside, lacking upward momentum" stalemate. If end-use orders in mid-to-late October fall short of expectations and inventory destocking is hindered, titanium product prices still face the risk of weakening again.