

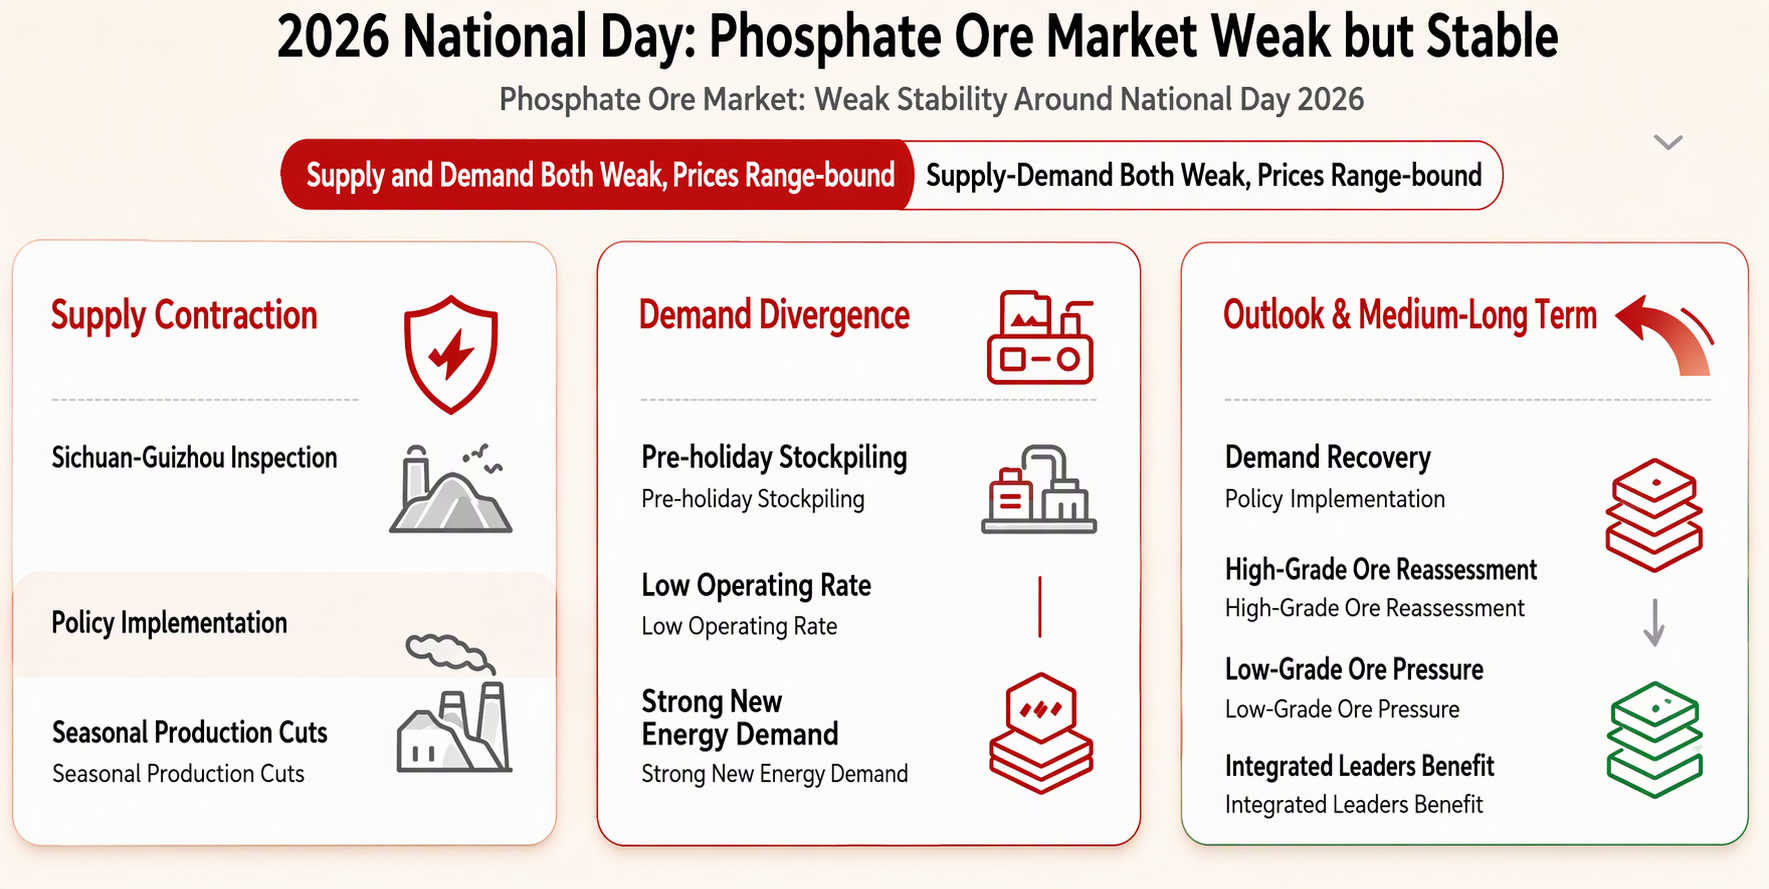
Key points: During the 2026 National Day holiday, phosphate ore remained in the doldrums, with both supply and demand weak and prices consolidating. Supply contracted due to environmental protection checks in Sichuan and Guizhou and seasonal production restrictions; demand was front-loaded before the holiday, downstream operating rates were low, and only new energy demand was relatively strong. After the holiday, the market will focus on demand replenishment and policy implementation. In the medium and long term, high-grade ore values are being reassessed upward, low-grade ore is under pressure, and integrated industry leaders stand to benefit.
During the 2026 National Day holiday (October 1-October 7), China's phosphate ore market was generally in the doldrums, with limited price fluctuations. Downstream procurement pace slowed somewhat, traders mostly took a wait-and-see stance, and market trading sentiment was subdued. Mine quotes remained stable, sellers and buyers were cautious, actual transactions were limited, and the market was unlikely to see significant improvement before the holiday.
In terms of price levels, as of the holiday period, price systems across regions were basically flat compared with pre-holiday levels, and the continuous consolidation trend remained unchanged.
Supply side:Environmental protection checks disrupted supply, with seasonal contraction in south China
The supply side showed structural contraction. Mine rectification in Sichuan and Guizhou continued to advance, with Sichuan's environmental protection checks being relatively stringent this time, most mines halted production, and production resumptions at the Leibo mining area were delayed. The phosphate ore market in Hubei remained in the doldrums, with downstream phosphate fertiliser and phosphate chemical enterprises' operating rates persistently low, significantly weakening support for ore prices.
Affected by seasonal mining restrictions, supply in major south China producing areas was expected to contract around the National Day and New Year holidays. Inventory at Sichuan phosphate ore mines declined significantly and was already at low levels, easing shipment pressure compared with earlier periods, but overall sales remained slow. On the import side, phosphate ore exports from Egypt's Abu Tartur mine remained stalled, while production at Red Sea mining areas increased somewhat to fill the gap. July imports plunged to 17,000 mt, down 87.3% MoM, and this extremely low base continued to weigh on import replenishment capacity, making a near-term import rebound unlikely.
Demand side:Pre-holiday stockpiling front-loaded, downstream operating rates subdued
The demand side showed a clear "pre-holiday stockpiling front-loading" pattern. Downstream enterprises had completed their main procurement arrangements before the holiday, new orders signed during the holiday were extremely limited, and both traders and mines mainly handled previous orders. Capacity utilization rates for ammonium phosphate remained low, significantly restraining phosphate ore demand.
Market outlook:Focus on post-holiday demand replenishment and policy variables
After the holiday, the market needs to focus on two core variables: first, the pace of recovery in downstream phosphate fertiliser and phosphate chemical enterprises' operating rates. If monoammonium phosphate (MAP) and diammonium phosphate (DAP) operating rates rebound after mid-October, this will provide phased demand replenishment for phosphate ore; new energy demand is relatively strong, and demand for phosphate ore continues to increase. Second, marginal changes on the policy front, particularly the enforcement of total phosphate ore mining volume controls and the specific implementation of export quotas.
Overall, in the short term, the phosphate ore market is expected to consolidate with prices remaining stable amid weak supply and demand, with post-holiday focus on demand recovery and policy changes. In the medium and long term, the logic of phosphate ore's resource value reassessment as a strategic mineral remains unchanged, and high-grade ore price centers are expected to stay high, but mid- and low-grade ore faces structural pressure from new capacity releases. Integrated industry leaders with "mining, beneficiation, and processing" operations will continue to benefit from replacing old growth drivers with new ones, thanks to their resource barriers and technological advantages.
Note: If you have any supplements regarding the details mentioned in this article or any questions about phosphate chemicals (phosphate ore, iron phosphate, LFP, etc.) and solid-state batteries, please feel free to contact us as follows:
Tel: 021-20707860 (or add WeChat 13585549799) Yang Chaoxing, thank you!



