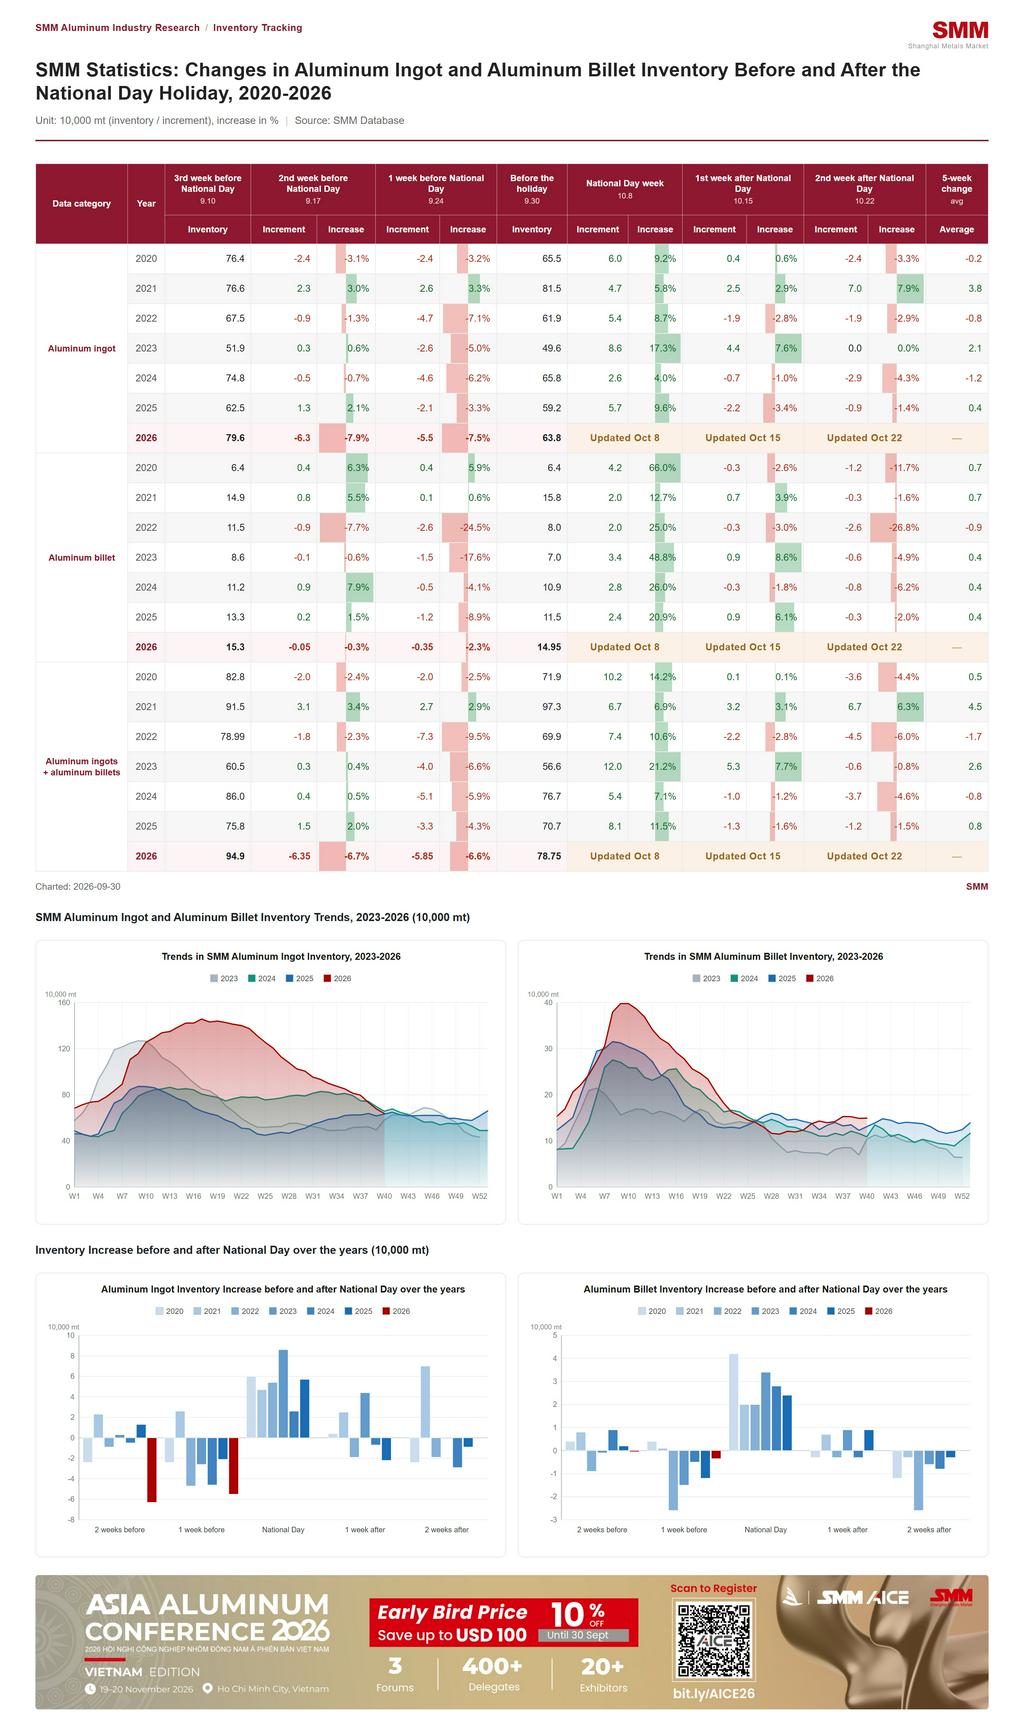
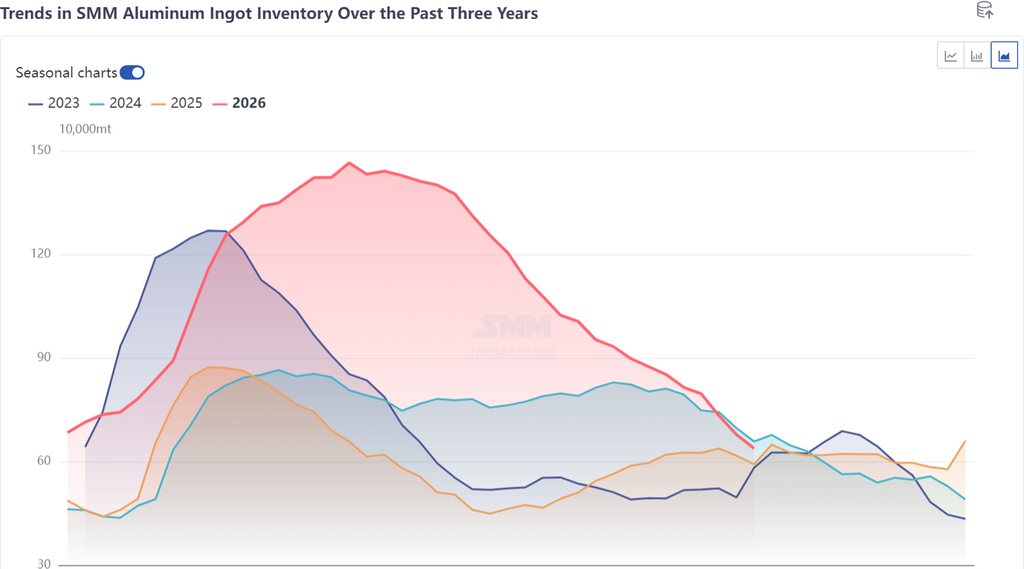
Ahead of the National Day holiday, domestic aluminum ingot inventories continued to set fresh year-to-date lows. According to SMM statistics, as of September 30, electrolytic aluminum ingot inventories in China's major consuming regions stood at 638,000 mt, down 36,000 mt from Monday and 40,000 mt from last Thursday. The pace of pre-holiday destocking was relatively fast overall, leaving ample buffer for inventory accumulation during the holiday.
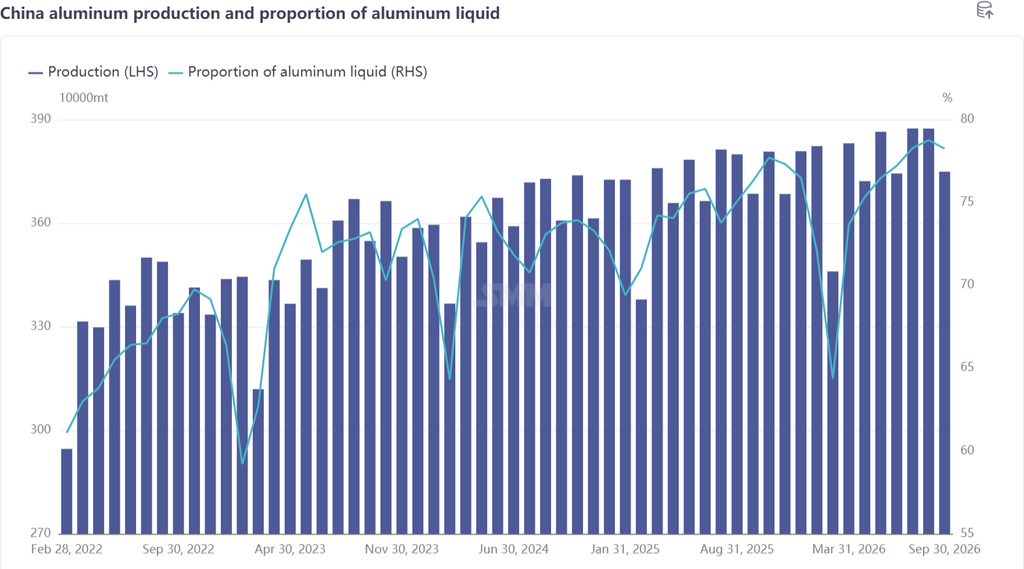
On the supply side, domestic downstream demand recovered somewhat month on month in September, but processing fees for some fabricated products came under pressure, leading some downstream enterprises to cut or suspend production, which lowered their willingness to purchase molten aluminum and pulled the molten-aluminum output ratio down. The molten-aluminum ratio fell 0.5 percentage points month on month to 78.2% in September, coming in below expectations set at the beginning of the month, with the core decline mainly concentrated in parts of the Central Plains and Southwest China. Based on SMM's molten-aluminum ratio estimates, domestic electrolytic aluminum ingot casting volume fell 6.2% year on year and 0.8% month on month in September. Looking into October, affected by the National Day holiday, a few downstream enterprises have staged output cuts or suspensions, and the molten-aluminum ratio is expected to edge down a further 0.3 percentage points to 77.9%. As processing fees for some downstream products still face downside risk and molten-aluminum demand remains under downward pressure, ingot casting volume is likely to stay on a rising trend month on month during the holiday.
However, transportation constraints are expected to offset the concentrated release of the increase in ingot casting. The shortage of rail containers in Xinjiang has yet to be resolved, compounded by transport bottlenecks in the Southwest, leaving overall shipping efficiency limited during the National Day holiday and easing the pressure from concentrated arrivals. As such, domestic aluminum ingot arrivals remain broadly manageable.
By region, SMM expects Foshan inventories to build by around 25,000–28,000 mt over the holiday, driven by increased casting in the Southwest and inter-regional cargo transfers spurred by price spreads; Wuxi and Gongyi are each expected to see accumulation of 10,000–20,000 mt. Taken together, the total domestic stock build over the holiday is projected to be broadly on par with the 57,000 mt accumulated during the same period last year, and domestic inventories are expected to rise to around 700,000 mt on the first trading day after the holiday.
Overall, the magnitude of holiday accumulation is moderate and controllable. Combined with the low absolute inventory level before the holiday, the post-holiday build will exert relatively limited pressure on the spot market, and the domestic aluminum ingot spot fundamentals will remain in a tight balance.