Secondary lead production in September 2026 rose 9.69% MoM but fell 13.37% YoY. Secondary refined lead production increased 15.56% MoM but declined 19.25% YoY. The MoM improvement in September production was mainly driven by a rebound in lead prices, which restored smelter profitability, coupled with stronger pre-holiday battery stockpiling demand from downstream users, lifting industry operating rates.
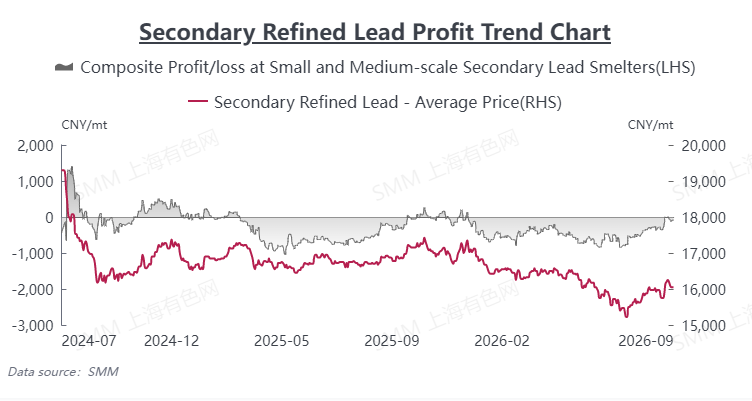
However, production remained weak on a YoY basis, with overall capacity utilization rate still at low levels and pronounced regional divergence. In east China, growth was constrained by the transition between old and new capacity and equipment commissioning issues. In north and northeast China, tight scrap battery collection led to production cuts at small smelters and early shutdowns at large smelters, further limiting the pace of overall supply recovery.
Looking ahead to October, secondary refined lead production is expected to increase by 24,900 mt MoM, marking a phased supply recovery. The growth will mainly come from east China: smelters that previously underwent maintenance and equipment commissioning are stabilizing operations, with capacity being steadily released. Some enterprises are actively ramping up production to fulfill long-term contracts, while a few long-idled smelters have restarted raw material procurement, and the progress of production resumptions will continue to contribute incremental output.
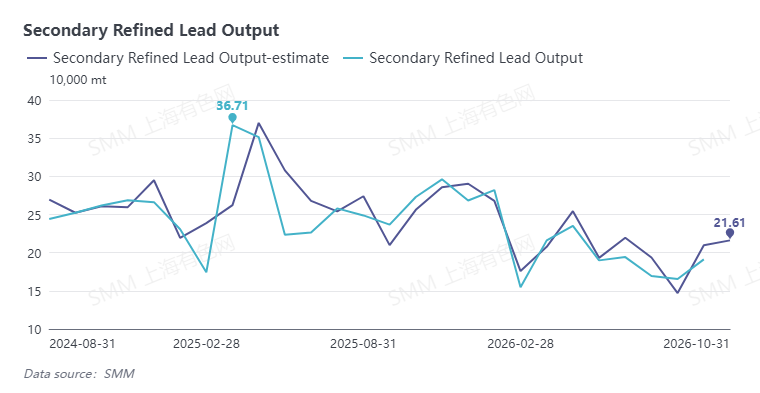
However, October production still faces significant uncertainty. A large smelter in central China has yet to confirm its production resumption pace, planning to decide whether to resume production after the National Day holiday based on lead price trends, costs, and end-use orders, which will be a key variable affecting this month's production realization. In addition, scrap battery collection and transportation will be disrupted during the holiday, limiting raw material restocking, and the sustainability of post-holiday end-use demand remains questionable, which may cap the overall production rebound.