

I. September Cold Rolled and Galvanized Market Review
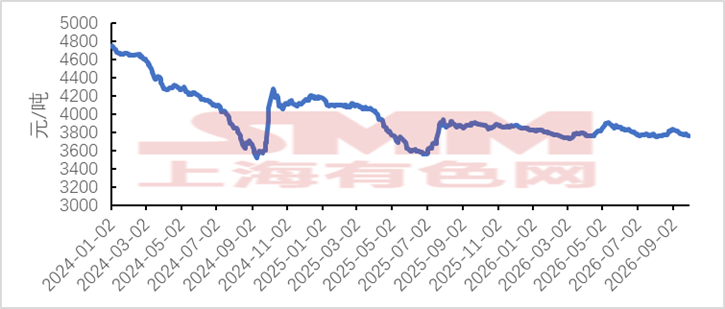
In September, the average price of cold rolled coil was yuan 3,798.15/mt, up yuan 14.96/mt from yuan 3,783.19/mt in August.
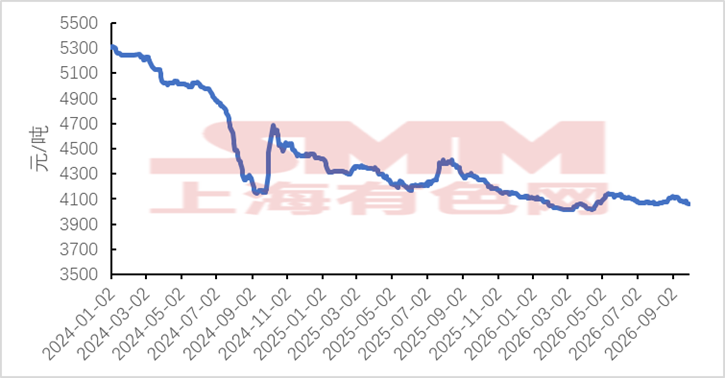
In September, the average price of galvanized coil was yuan 4,093.99/mt, up yuan 13.49/mt from yuan 4,080.5/mt in August.
In September, the cold rolled and galvanized market overall showed a consolidation pattern of rising first and then falling, with costs providing a floor while demand acted as a cap. The market was centered on the tug-of-war between raw materials and end-use demand. In early September, the pace of production resumptions at Shanxi coking coal mines fell short of expectations. Mines held back from selling, auctions closed at high premiums, and the fourth round of coke price hikes was implemented. Iron ore rose on news of mine suspensions, and multiple bullish factors on the cost side jointly pushed ferrous metals higher, with cold rolled and galvanized prices following raw materials upward. Cost-side support continued to build as the fifth round of coke price hikes took effect, lifting the cost floor step by step. Market expectations for the "September peak season" remained intact, and cold rolled and galvanized prices consolidated on a strong note. However, inventories of sheets and plates kept accumulating, end-use demand during the peak season had yet to materialize effectively, downstream acceptance of high-priced resources was weak, and upside for prices was limited. In mid-September, news emerged about railway construction at the China-Mongolia border port, raising concerns that Mongolian coal supply would recover. The rise in coking coal and coke was blocked, ferrous metals futures began to pull back, and iron ore weakened under the drag of long-term contract negotiation rumors and a rebound in port inventories. Cost support loosened at the margin, and cold rolled and galvanized prices retreated after a rapid rise. In late September, multiple rounds of coke price hikes continued to squeeze steel mill profits, widening losses at mills. Hot metal production gradually pulled back, the scope of maintenance and production halts increased, and expectations for raw material demand declined. In addition, the anticipated impact of the three ministries' policy on stabilizing coal production and ensuring supply weakened coking coal and coke, further eroding cost-side support. Although downstream restocking before the holiday generated some speculative demand, the release of end-use demand for sheets and plates was limited, the peak season underdelivered, and the supply-demand imbalance persisted. Cold rolled and galvanized prices consolidated within a narrowing range, and at month-end they moved sideways amid the tug-of-war between loosening costs and weak demand.
SMM Cold Rolled Nationwide Average Price
Data source: SMM
SMM Galvanized Nationwide Average Price
Data source: SMM
II. September Cold Rolled and Galvanized Market Fundamentals Review
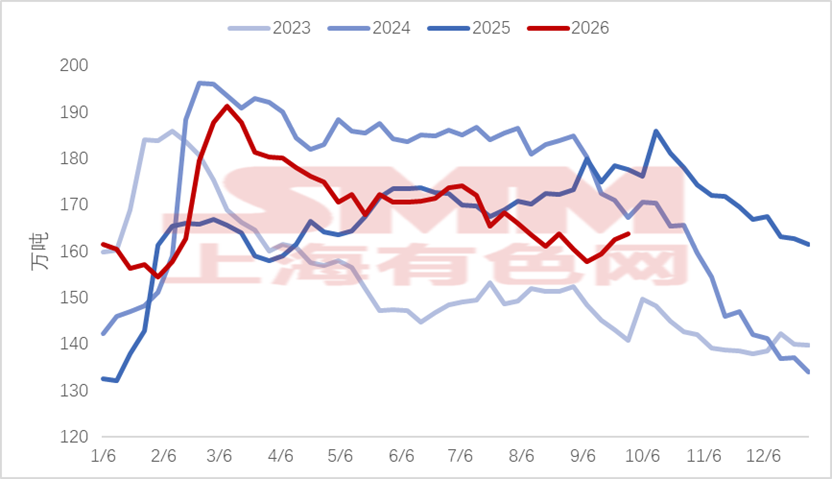
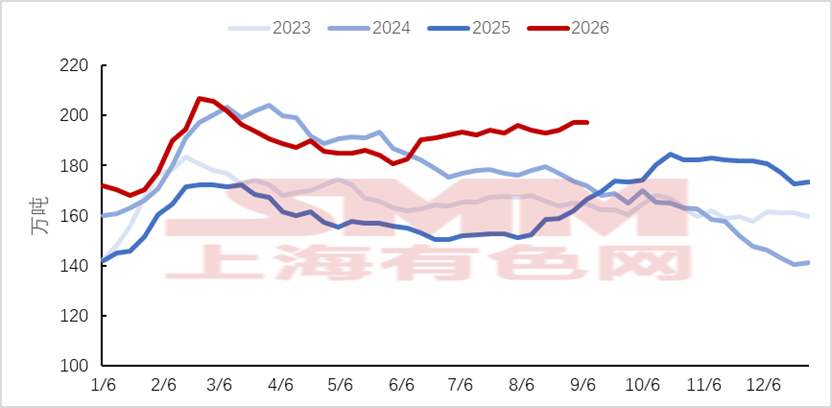
From a fundamentals perspective, steel mill orders in September improved compared with August. With the peak season arriving, steel mill orders improved in September, but this year's peak season demand level was significantly lower than the same period in previous years. Market demand only improved relative to the off-season of the previous few months, but overall demand conditions were not ideal. In September, cold rolled and galvanized inventories both showed an inventory buildup trend, mainly because traders in the market deliberately stockpiled more goods in September to guard against stronger-than-expected peak season demand and the upcoming Mid-Autumn Festival and National Day holidays at the end of September. However, it now appears that the recovery in downstream demand has fallen short of expectations. Although there was some stockpiling before the holiday, the stockpiling volumes were relatively cautious, and under the drag of less-than-optimistic market demand, inventories showed an inventory buildup trend.
SMM Cold Rolled Total Inventory
Data source: SMM
SMM Galvanized Total Inventory
Data source: SMM
III. October Cold Rolled and Galvanized Market Outlook
Looking ahead to October, cold rolled and galvanized prices are expected to consolidate on a subdued note. From the cost side, according to SMM statistics, steel mill losses continued to widen in September, hot metal production gradually pulled back, and raw material demand expectations declined. Iron ore was affected by steel mills pushing for lower prices and rebounding port inventories, weakening price support. Coking coal and coke were suppressed by expectations of stable production and supply guarantee policies, limiting their upside. After multiple rounds of coke price hikes, the tug-of-war between coke producers and steel mills intensified, and cost support showed some loosening. However, expectations for production cuts driven by steel mill losses still provide some support to the bottom of finished steel prices. From the demand side, October marks the tail end of the traditional "October peak season," compounded by the disruption of the National Day holiday. End-use demand growth from downstream sectors such as automobiles and home appliances for sheets & plates is limited. The pre-holiday stockpiling momentum has faded, speculative demand in the market has weakened, inventory accumulation pressure on sheets & plates persists, and end-users have low acceptance of high-priced resources. Overall demand in October is unlikely to see significant volume growth. In summary, October cold rolled and galvanized prices are expected to consolidate amid a pattern where costs still provide a floor but peak season demand gradually weakens. Upside is limited by demand pressure, while deep downside risk is constrained by expectations for steel mill production cuts. However, attention should still be paid to the pace of orders and inventory destocking in downstream automobile and home appliance industries in October. If end-use demand recovers more than expected, there is a possibility of a phased rebound in prices.



