SMM, September 24:
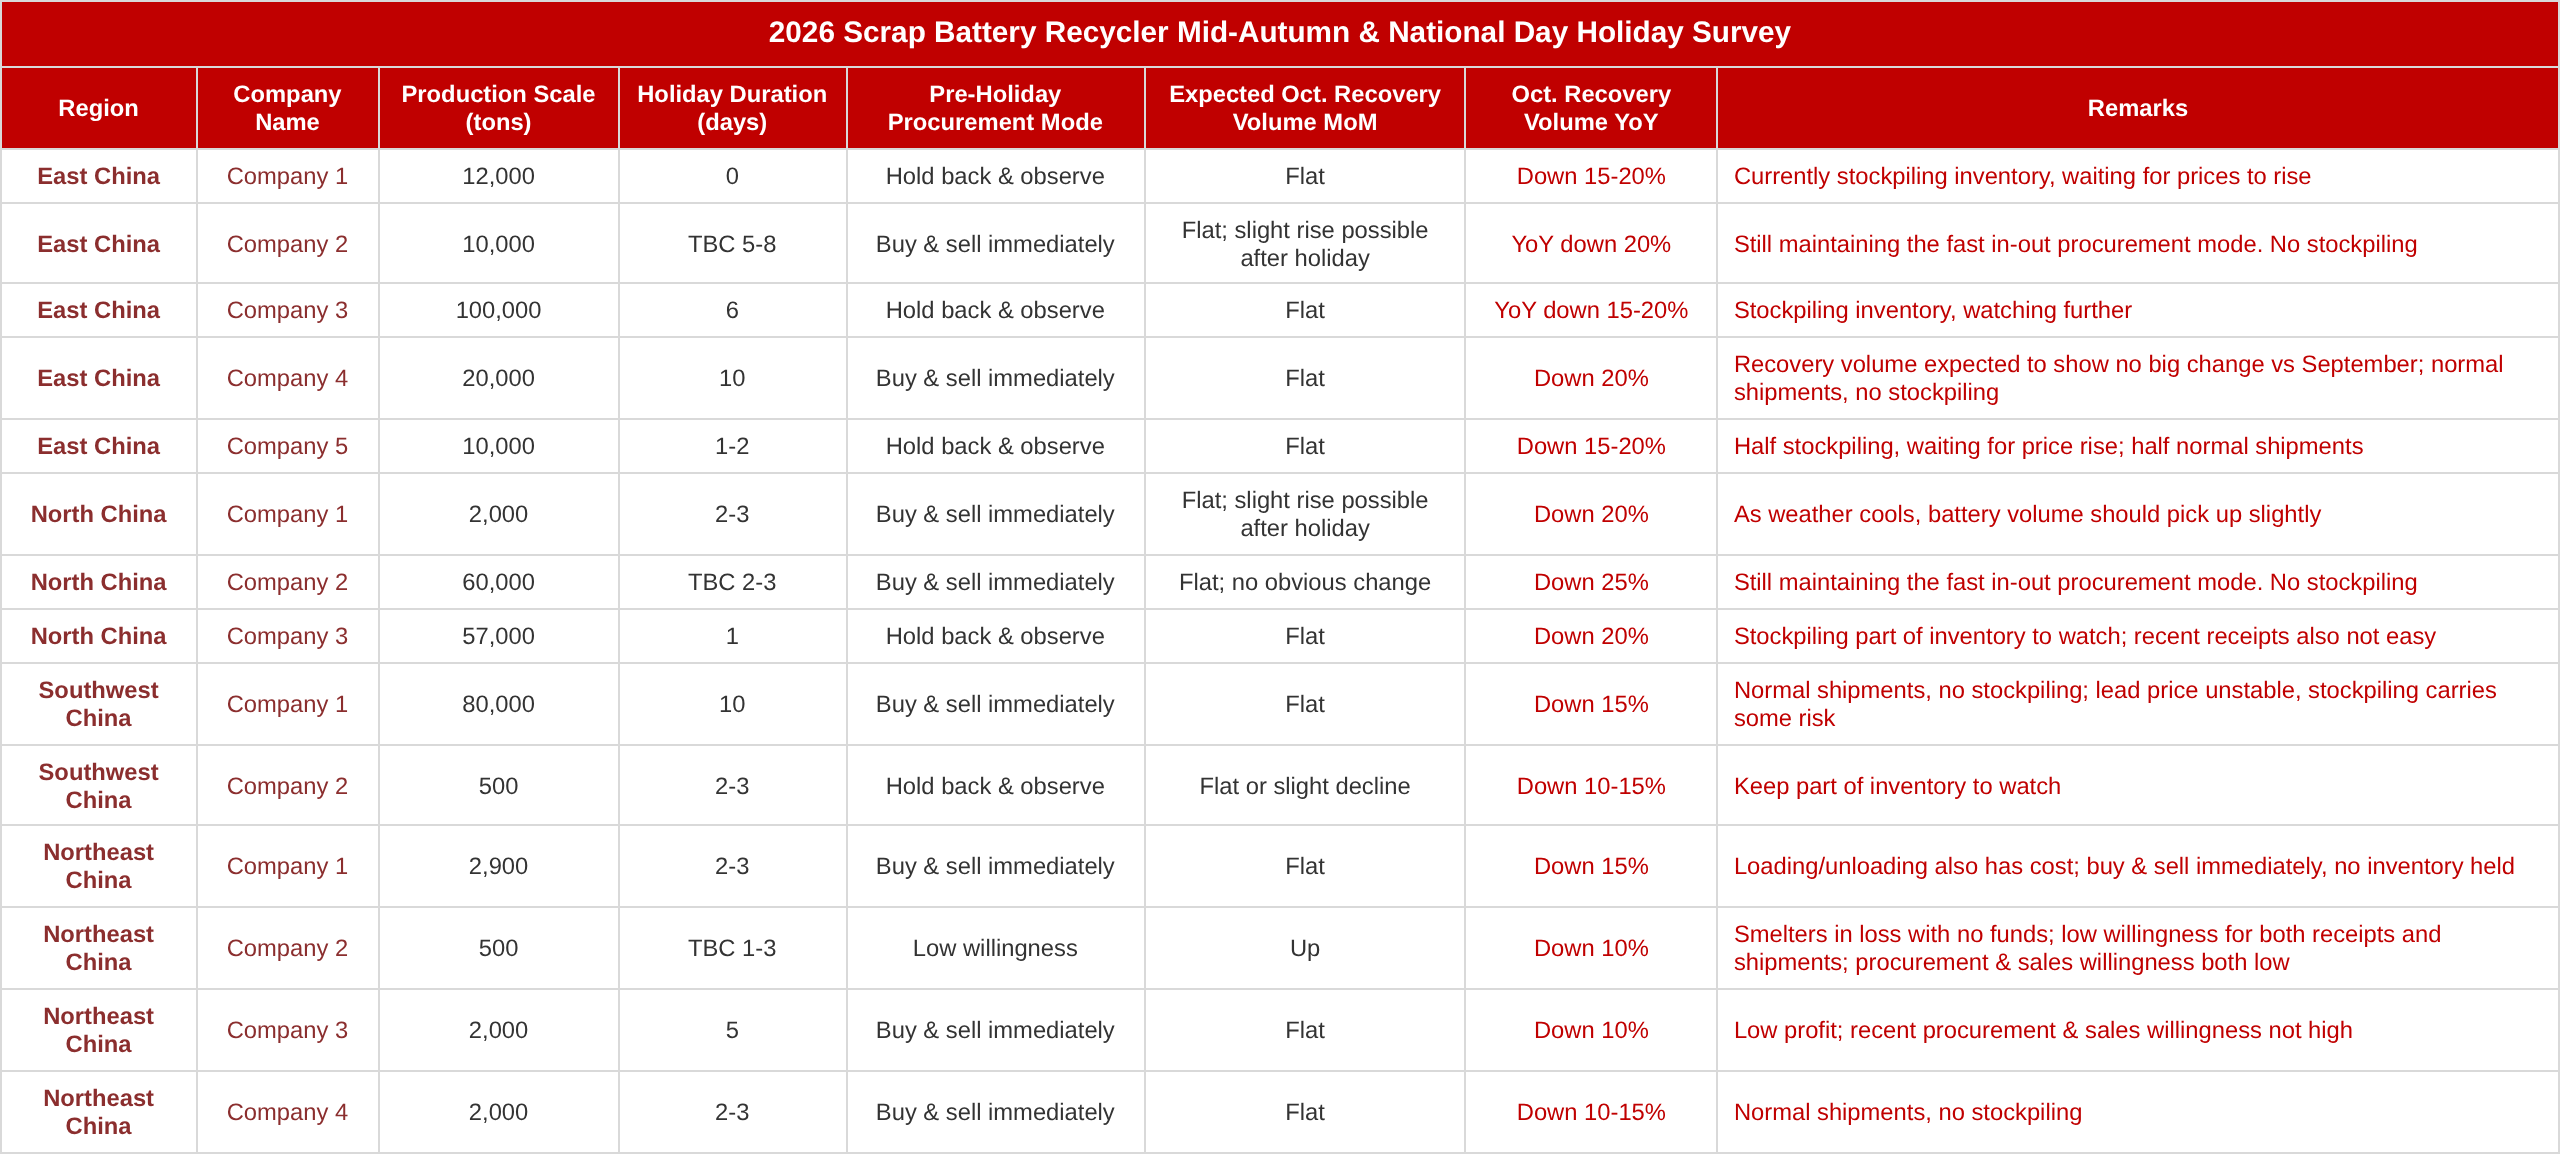
With the Mid-Autumn Festival and National Day holidays approaching, the market is focused on the pace of scrap battery buying and selling during the holidays and the price trend after the holidays. SMM recently conducted a telephone survey of 14 scrap battery recycling enterprises, with a combined annual recycling volume of approximately 360,000 mt, covering east China, north China, southwest China, and northeast China. The survey shows that recyclers will mostly take short holidays of 1-3 days with no long-term shutdown arrangements, and pre-holiday buying and selling sentiment is roughly split 50/50, with overall cautious expectations for post-holiday prices.
1. Holiday arrangements: mostly short breaks of 1-3 days
Among the 14 sampled enterprises, 9 will take 1-3 days off and 5 will take 5-10 days off. By region, the 5 enterprises in east China show varied holiday lengths (ranging from 0 to 10 days); the 3 in north China will mostly take 1-3 days off; in southwest China, 1 will take 10 days off in line with statutory holidays and 1 will take 2-3 days off; the 4 in northeast China will mostly take 2-3 days off (1 will take 5 days). Overall, holiday periods at sampled enterprises are generally short, and the impact of the holidays on recycling operations is limited.
2. Pre-holiday buying and selling status of recyclers: a 50/50 split between selling as collected and holding back to wait and see
Pre-holiday buying and selling sentiment is roughly split 50/50, with 8 of the 14 enterprises selling as collected, 5 holding back inventory to wait and see, and 1 showing sluggish willingness. Those selling as collected mainly adopt a fast-in, fast-out approach with no inventory retention, with some believing that lead prices are unstable and stockpiling carries risk, or considering loading and unloading costs and thus selling as they collect; those holding back to wait and see mostly keep some inventory and wait for price increases, concentrated in east China, north China, and southwest China; in northeast China, 1 additional enterprise shows sluggish buying and selling willingness due to long payment terms at smelters and slow capital turnover.
3. Recycler expectations: recycling volume generally seen lower YoY, cautious on post-holiday prices
On recycling volume forecasts, according to recycler feedback, October volume is expected to be mainly flat MoM—10 enterprises expect basically flat, 3 expect a slight rebound, and 1 expects flat to slightly lower; on a YoY basis, sentiment is broadly cautious, with all 14 enterprises expecting YoY declines, with declines concentrated in the 10%-25% range (4 expecting a 10%-15% decline, 5 expecting a 15%-20% decline, and 5 expecting a 20%-25% decline). On prices, most recyclers expect post-holiday scrap battery prices to remain flat and move sideways, while a few still expect a slight increase, but their expectations are not firm. The main reason is that after suppliers concentrated their shipments last week, smelters' raw material inventories are relatively sufficient, and some enterprises are already at full inventory. Pre-holiday purchasing is mainly as needed, with limited willingness to raise prices. Recyclers believe there is a lack of direct momentum to boost scrap battery prices in the short term, and most are waiting for smelters to digest their scrap battery raw material inventories before restocking and adjusting prices.
SMM believes that with the two holidays approaching and weakening guidance from futures, recyclers and suppliers are showing strong wait-and-see sentiment, market trading is tending toward sluggishness, and scrap battery prices are expected to remain stable in the short term. Post-holiday, price movement is limited in both directions: On one hand, smelters hold ample raw material inventory, downstream battery makers are nearing the end of pre-holiday stockpiling, and scrap battery retirement volume is expected to rebound seasonally as weather cools, so prices encounter resistance on the upside and may edge slightly lower. On the other hand, currently available supply is tight and some suppliers are holding back from selling, which supports prices and limits the downside. Overall, scrap battery prices are expected to remain largely stable in the near term. After the holiday, both a slight decline and a follow-up rise are possible. Key areas to watch include the pace of smelters' raw material inventory digestion and restocking price adjustments, as well as the release of supply from suppliers.