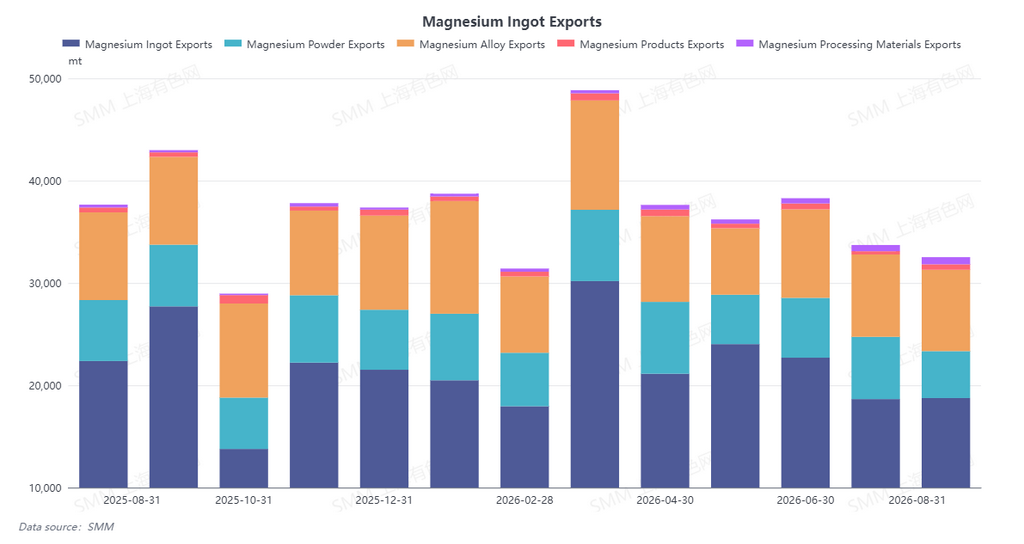
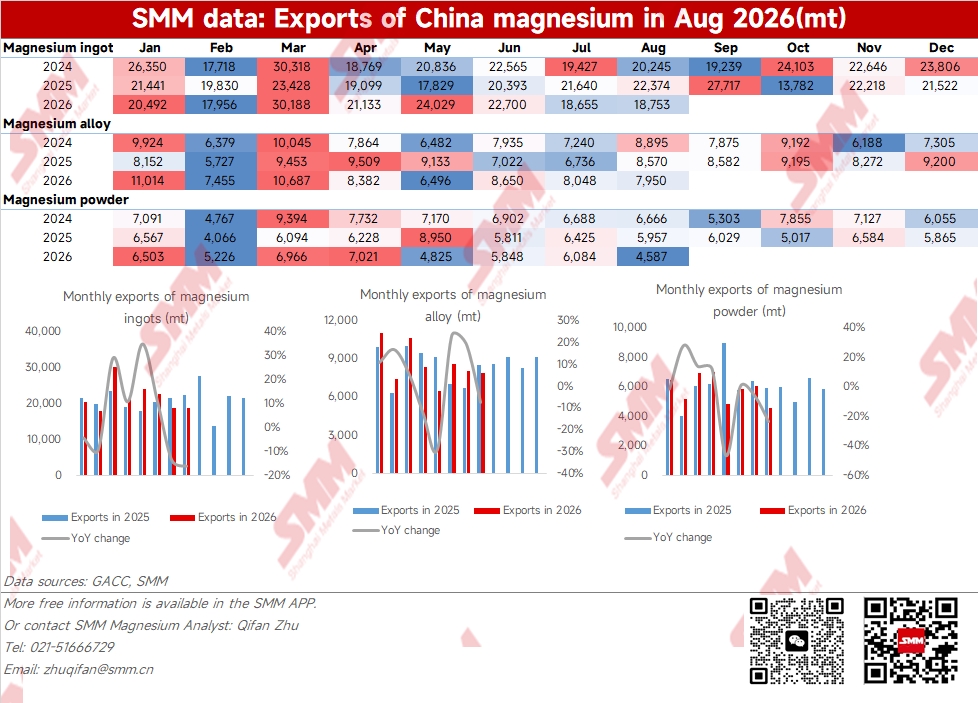
In August, China's total magnesium product exports were 33,400 mt, down 3.5% MoM and down 13.7% YoY. By product, magnesium ingot exports were 18,800 mt, up 0.5% MoM and down 16.2% YoY, ending two consecutive months of export declines since May. The downtrend in magnesium powder exports intensified further, with August exports at 4,587 mt, down 24.6% MoM. Magnesium alloy exports were 7,950 mt, down 1.2% MoM and down 7.2% YoY. Apart from magnesium powder, the fluctuation in magnesium ingot and magnesium alloy exports in August was relatively limited. Looking ahead, with the traditional September-October peak season gradually arriving and some foreign trade orders being delivered in a concentrated manner, magnesium product exports may see a MoM recovery in September-October, but the actual extent of the rebound still needs to be continuously observed and verified.
August magnesium product export volume continued to pull back MoM, but cumulative exports in 2026 remained on an uptrend YoY
In August 2026, China's magnesium product exports were 33,400 mt, down 3.5% MoM from July and down 13.7% YoY from August last year. Cumulative exports of various magnesium products from January to August reached 307,000 mt, up 3.5% YoY.
Although August monthly exports still showed a pullback trend, cumulative export value from January to August was approximately $748 million, up 5.97% YoY. In January-August 2026, the growth rate of China's magnesium product export value was significantly higher than that of export volume, reflecting the continuous optimization of China's magnesium product export structure. As the industry's trade model gradually transforms and upgrades from low-end, low-value-added magnesium ingot raw material exports to high-value-added magnesium alloy and high-end die-cast finished product exports, the unit value of exports has steadily risen, driving overall export value growth to outpace sales volume growth. This reflects the continuous improvement of China's magnesium industry's deep processing capabilities and global product premium capacity.
There are two main reasons for the continued decline in magnesium product export volume in August. First, the traditional off-season overseas summer break continued to suppress demand, which began to emerge in July and deepened further in August. In July, major consumer markets such as Europe had already entered the summer break period, with downstream factory operating rates declining and procurement pace slowing. This seasonal factor continued to intensify in August. European clients were generally on holiday, with inquiries and actual orders significantly reduced, and the release of new orders nearly stagnant. From the export data, magnesium ingot exports fell 16.2% YoY in August, and magnesium powder fell 23.00% YoY, with declines significantly larger than the 7.2% for magnesium alloy. This indicates that the summer break had a more direct impact on primary raw materials, while alloys were relatively less affected due to deeper downstream production line integration and stronger rigid demand. This structural difference confirms that the off-season pressure on exports was mainly concentrated in magnesium ingot and magnesium powder, which have higher substitutability. Second, the upward cost side supported magnesium smelters in holding prices firm, creating a stalemate with overseas buyers' expectations of pushing for lower prices. In August, coal and semi coke price centers moved upward, driving up ferrosilicon costs, and ferrosilicon spot prices drifted higher. This round of raw material increases mainly came from supply-side tightening and fuel cost transmission, while downstream magnesium demand did not strengthen simultaneously, creating cost-side pressure on magnesium smelting. In August, the monthly average ex-works price of domestic magnesium ingot was 15,881 yuan/mt, up slightly by 35 yuan/mt MoM from July, an increase of only 0.22%, but the absolute price level remained above overseas buyers' psychological price levels. The price divergence between buyers and sellers was difficult to bridge, leading to sluggish export trading. Meanwhile, ocean freight rates remained high in August, with freight rates rising due to tight shipping capacity on routes, and the additional transportation costs further compressed traders' profit margins and downstream purchase willingness.
August magnesium product exports continued to diverge, with magnesium ingot and magnesium alloy exports basically flat MoM from July, while magnesium powder exports pulled back notably.
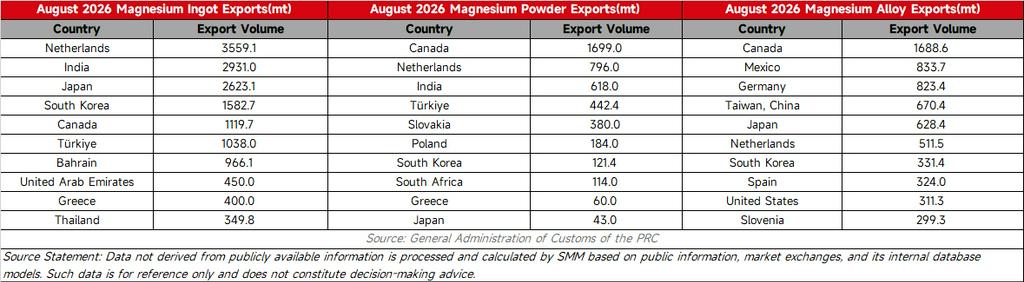
Specifically, magnesium ingot exports saw the largest YoY decline. August magnesium ingot exports were 18,753 mt, down 16.2% YoY, the steepest YoY drop among the three major products. The core reason is that magnesium ingot, as a primary raw material, is the most substitutable, and overseas clients cut magnesium ingot procurement first during the summer break off-season. In addition, domestic producers held prices firm amid losses, making it difficult to bridge the price gap between buyers and sellers, leaving transactions in a prolonged stalemate. Magnesium alloy showed the strongest resilience and was the only product to achieve a YoY increase in average price. August magnesium alloy exports were 7,950 mt, down 7.2% YoY, less than half the decline of magnesium ingot. The core reason is that alloyed products have deeper downstream ties, with die-casting enterprises in markets such as Canada, Mexico, and Germany showing strong rigid demand and significantly better resistance to summer break seasonal factors than primary magnesium ingot. Magnesium powder exports saw the sharpest pullback, facing multiple demand pressures. August magnesium powder exports were 4,587 mt, down 23.0% YoY and down 24.6% MoM, the largest decline in export volume among all products for the month. Magnesium powder is mainly used in steel desulfurization, and overseas small and medium-sized steel mills slowed production, while previously imported inventory was still being digested, with purchase willingness continuing to weaken. In addition, tightening export controls on dual-use items further constrained magnesium powder exports, with multiple factors combining to drive a notable decline in August magnesium powder exports.
High-end magnesium product export demand was strong, with the foreign trade structure continuing to optimize.
Looking at export data by destination, among the top three destinations for magnesium ingot, the Netherlands fell 8.6% MoM and 39.7% YoY, Germany fell 41.4% MoM and 47.0% YoY, and Spain, Italy, Poland, and other countries also generally declined. European clients' holidays led to a slower procurement pace, while India rose 60.3% MoM and Japan rose 8.7% MoM, indicating that Asia's holiday schedule differs from Europe's and demand is relatively stable. The same was true for magnesium powder, with Turkey plunging 70.4% MoM and the Netherlands down 31.9%, as European steel desulfurization demand contracted notably during the summer break. High-end magnesium product exports performed strongly, becoming the core growth driver of foreign trade. Among them, magnesium semi-finished product exports surged 148.5% YoY, with growth driven mainly by the North American market. Exports to the US accounted for as much as 81.8%, up 187.9% YoY, while exports to Canada soared 261.5% MoM. Magnesium alloy exports also showed broad-based strength, with exports to Germany up 20.9% MoM and 162.8% YoY, and exports to Taiwan, China up 108.1% MoM and 451.6% YoY. This demonstrates that rigid demand for high-end magnesium alloys remains resilient and is relatively unaffected by the overseas summer break off-season, fully confirming that the export demand structure for China's magnesium products is undergoing a shift and that foreign trade patterns continue to upgrade. Meanwhile, magnesium product exports to Thailand rose sharply MoM, and the Southeast Asian market is steadily emerging as a new growth pole for China's magnesium product exports. Overall, August export data reflect structural changes in global magnesium trade. The European off-season mainly affected primary raw material exports, while demand for alloys and deep-processed products in North America and some Asian markets continued to grow. The resilience of China's magnesium exports is increasingly reflected in high-end categories such as alloys and semi-finished products.
Magnesium export market outlook: exports are expected to recover gradually in the short term as the traditional peak season approaches, and total export volume for full-year 2026 is still expected to edge up.
After the European summer break ends, local downstream die-casting enterprises will gradually resume production schedules, and phased restocking demand for magnesium ingots and magnesium alloys is expected to be released. Although overall overseas demand has not yet shown a comprehensive market reversal or concentrated recovery, and overseas buyers have a strong desire to bargain down prices, coupled with firm domestic magnesium prices, the price spread between Chinese and overseas markets remains significantly divergent, and short-term foreign trade transactions may continue to face a stalemate. However, demand resilience in Asian markets such as India, Japan and South Korea was evident in August. If this trend persists, it could effectively offset the pressure from a slower recovery in the European market. Overall, with the start of the traditional September-October peak season, magnesium product exports are likely to improve MoM, but the market may be driven mainly by restorative replenishment. The extent of the subsequent rebound will depend on the sustainability of overseas demand and the outcome of price bargaining between domestic and overseas markets. In January-August 2026, China's total exports of various magnesium products reached approximately 307,200 mt, up 3.53% YoY, already achieving 68.6% of the 447,600 mt total export volume for full-year 2025. Although magnesium product exports have continued to weaken over the past two months, inventory accumulated earlier by clients outside China has pulled back after continuous consumption, and the market is expected to see a restocking window after October. However, further release of demand still requires price levels to align with expectations of buyers outside China. Moreover, lightweighting demand in downstream magnesium applications outside China is growing steadily, and no large-scale new primary magnesium capacity is expected to come online outside China in the short term. Global primary magnesium supply remains highly dependent on Chinese sources, so China's overall magnesium product export volume still has upside potential.