The 2026 National Day holiday is approaching. SMM surveyed some copper processing enterprises regarding their production arrangements during the National Day holiday.This survey covered 98 downstream copper processing enterprises, with a total annual capacity of 16.7348 million mt.The holiday schedules of downstream enterprises showed significant divergence this time, with varying holiday durations across different sectors and prominent differentiation in production strategies.Affected by copper prices consolidating at highs before the holiday, tight spot supply, and high premium levels, coupled with uneven demand across terminal sub-sectors, downstream enterprises were generally cautious in stockpiling before the holiday and purchased as needed, with the industry as a whole showing a clear characteristic of operating at low inventory levels. Details of the survey by sector are as follows: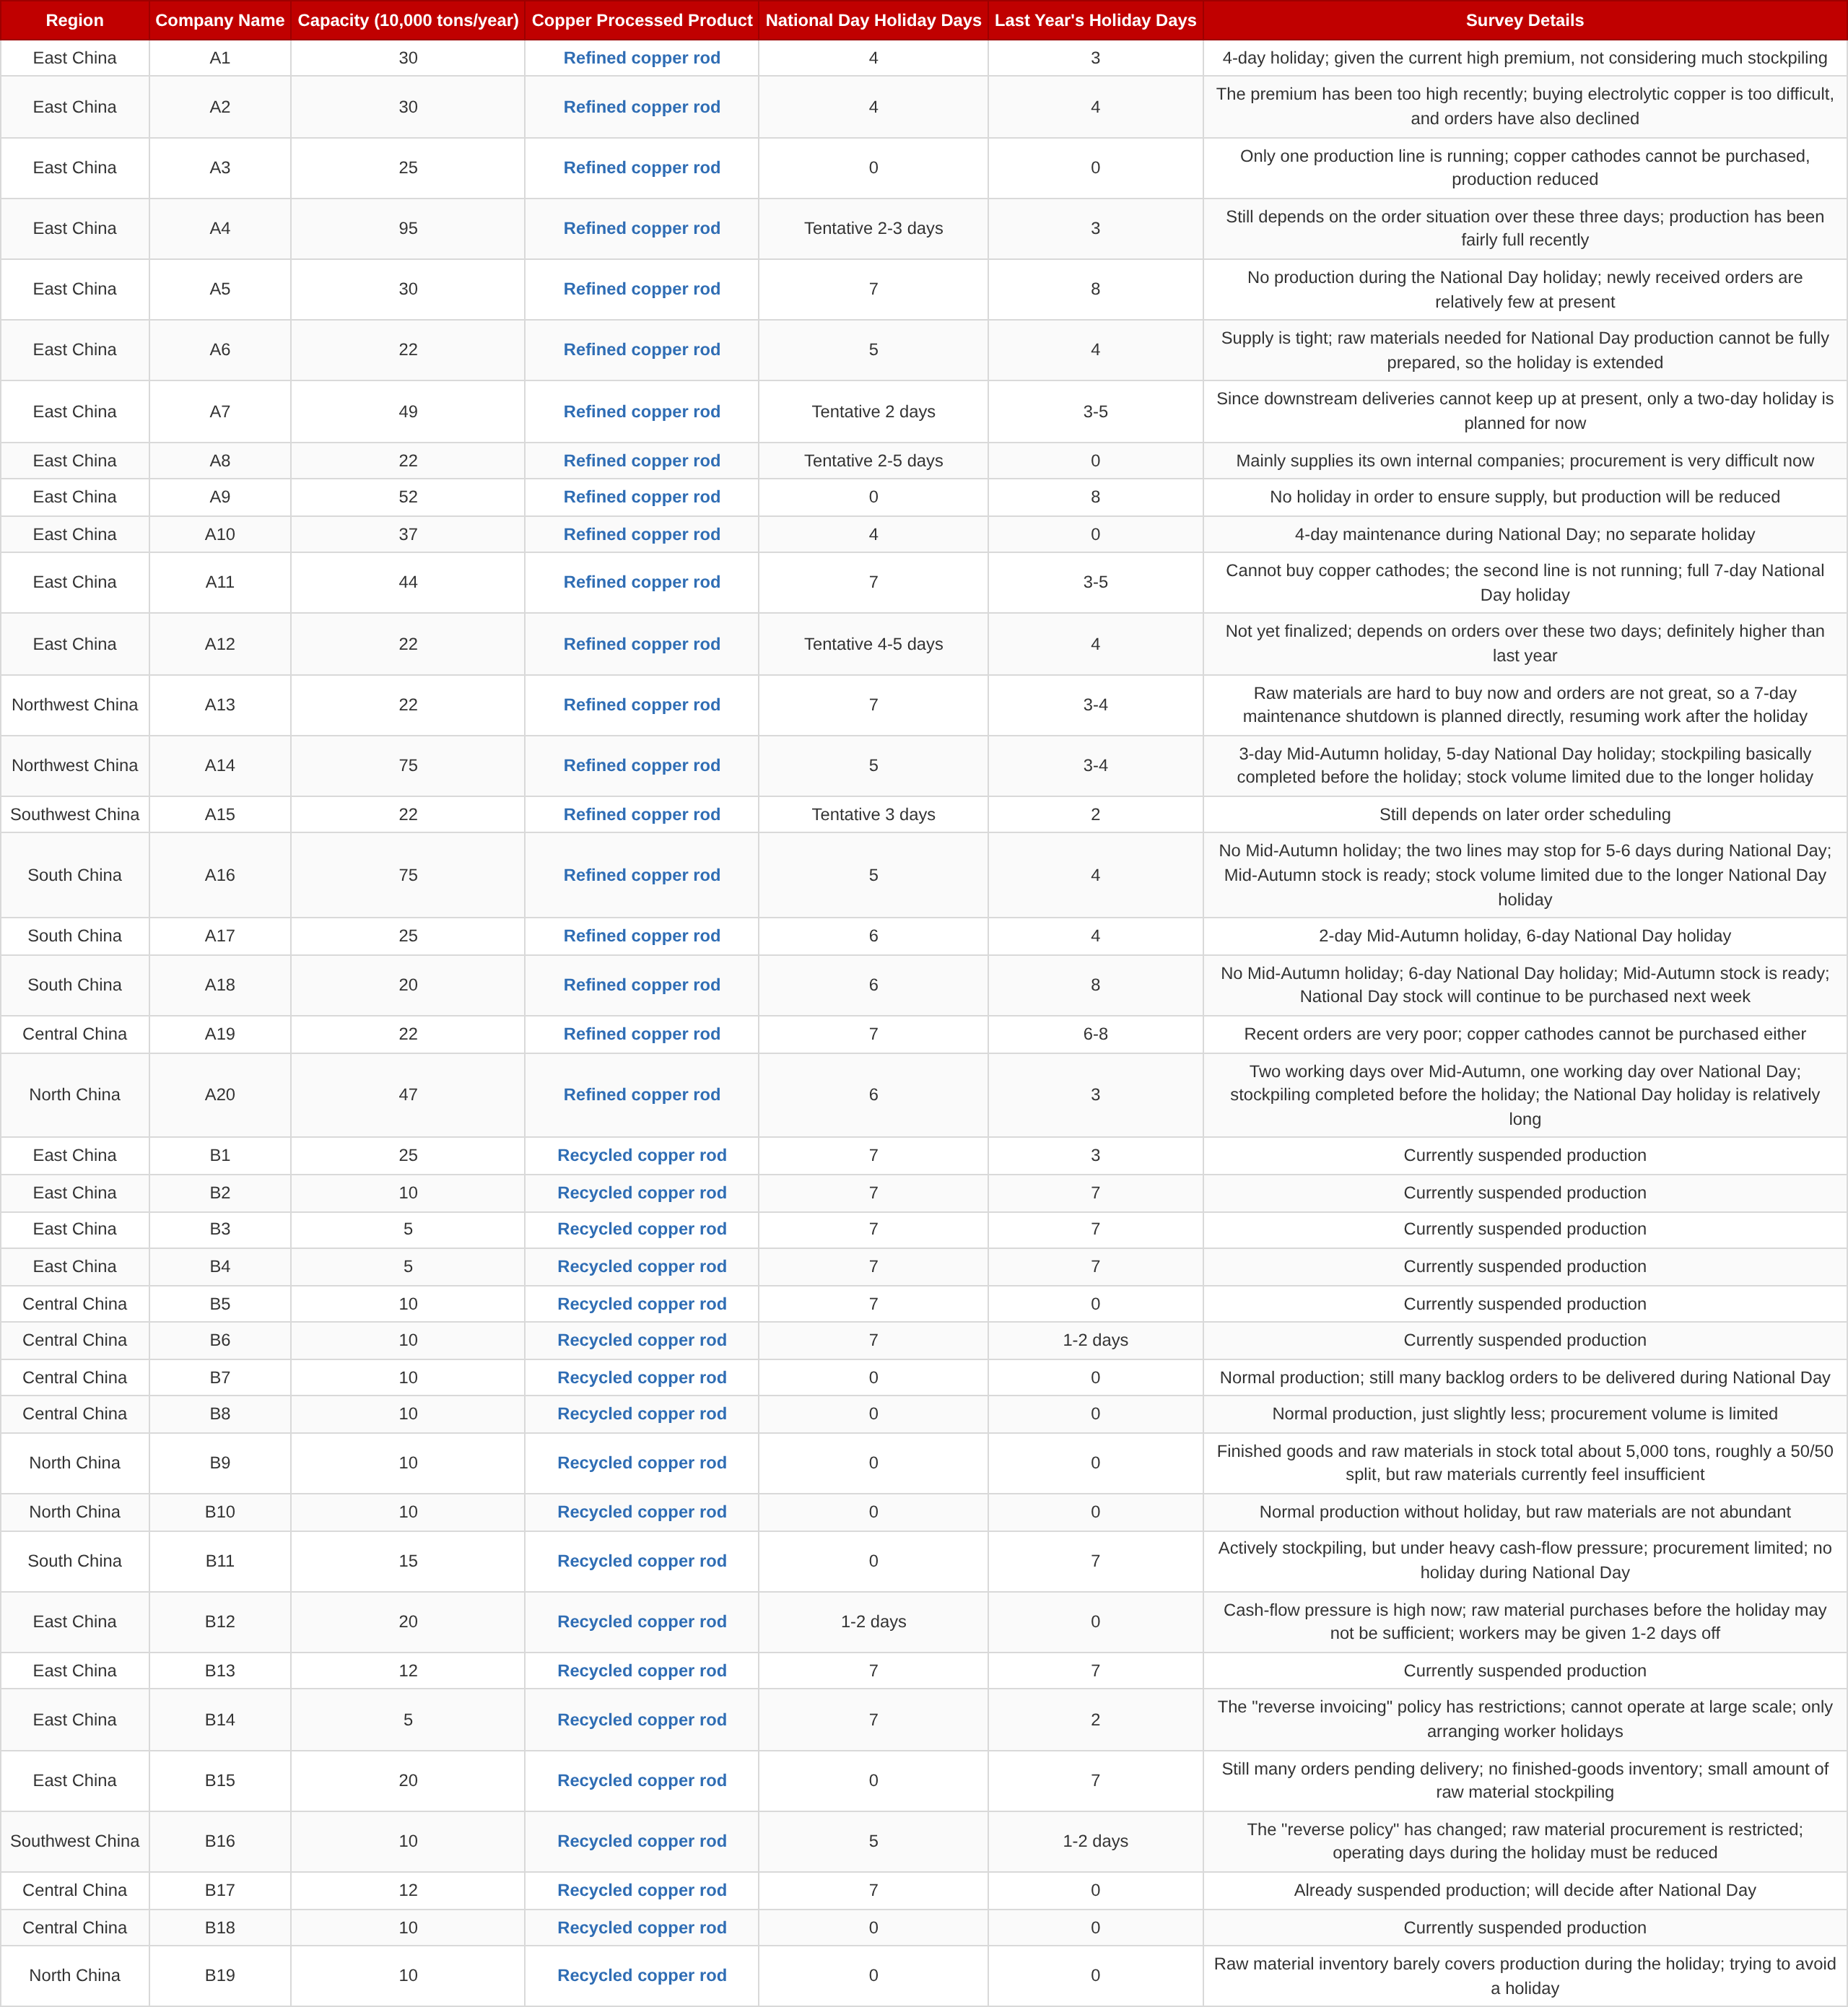
Copper cathode rod: Domestic copper cathode rod enterprises had an average National Day holiday of 4.4 days, up 0.35 days YoY.Copper prices fluctuating at highs in the earlier period suppressed downstream purchasing. Near the holiday, a pullback in copper prices drove a brief release of orders, but as the holiday approached, spot copper cathode supply tightened and spot premiums rose, making raw material procurement more difficult. Downstream wire & cable and enamelled wire enterprises saw a notable weakening in stockpiling sentiment, and new orders before the holiday remained scarce.With high copper prices and no clear recovery in downstream demand, SMM expects the operating rate of the copper cathode rod industry in October to decline MoM and fall below the level of the same period last year.
Secondary copper rod: The scope of production halts at secondary copper rod enterprises expanded, with the National Day holiday generally extended to 7 days. The industry showed a stark divide, with nearly half of the sampled capacity in a state of production suspension.Under the triple pressure of the reverse invoicing policy, financial constraints, and weak new terminal orders, enterprises were generally cautious about stockpiling before the holiday. Most enterprises had zero raw material stockpiling, finished product inventories were generally low, and most adopted strategies of producing based on sales and operating at low inventory levels.Looking ahead to October, the industry operating rate is expected to remain roughly flat MoM and under pressure YoY, with only enterprises in a few regions expecting YoY growth. Going forward, close attention should be paid to the implementation standards of the policy and the recovery of copper scrap raw material supply.
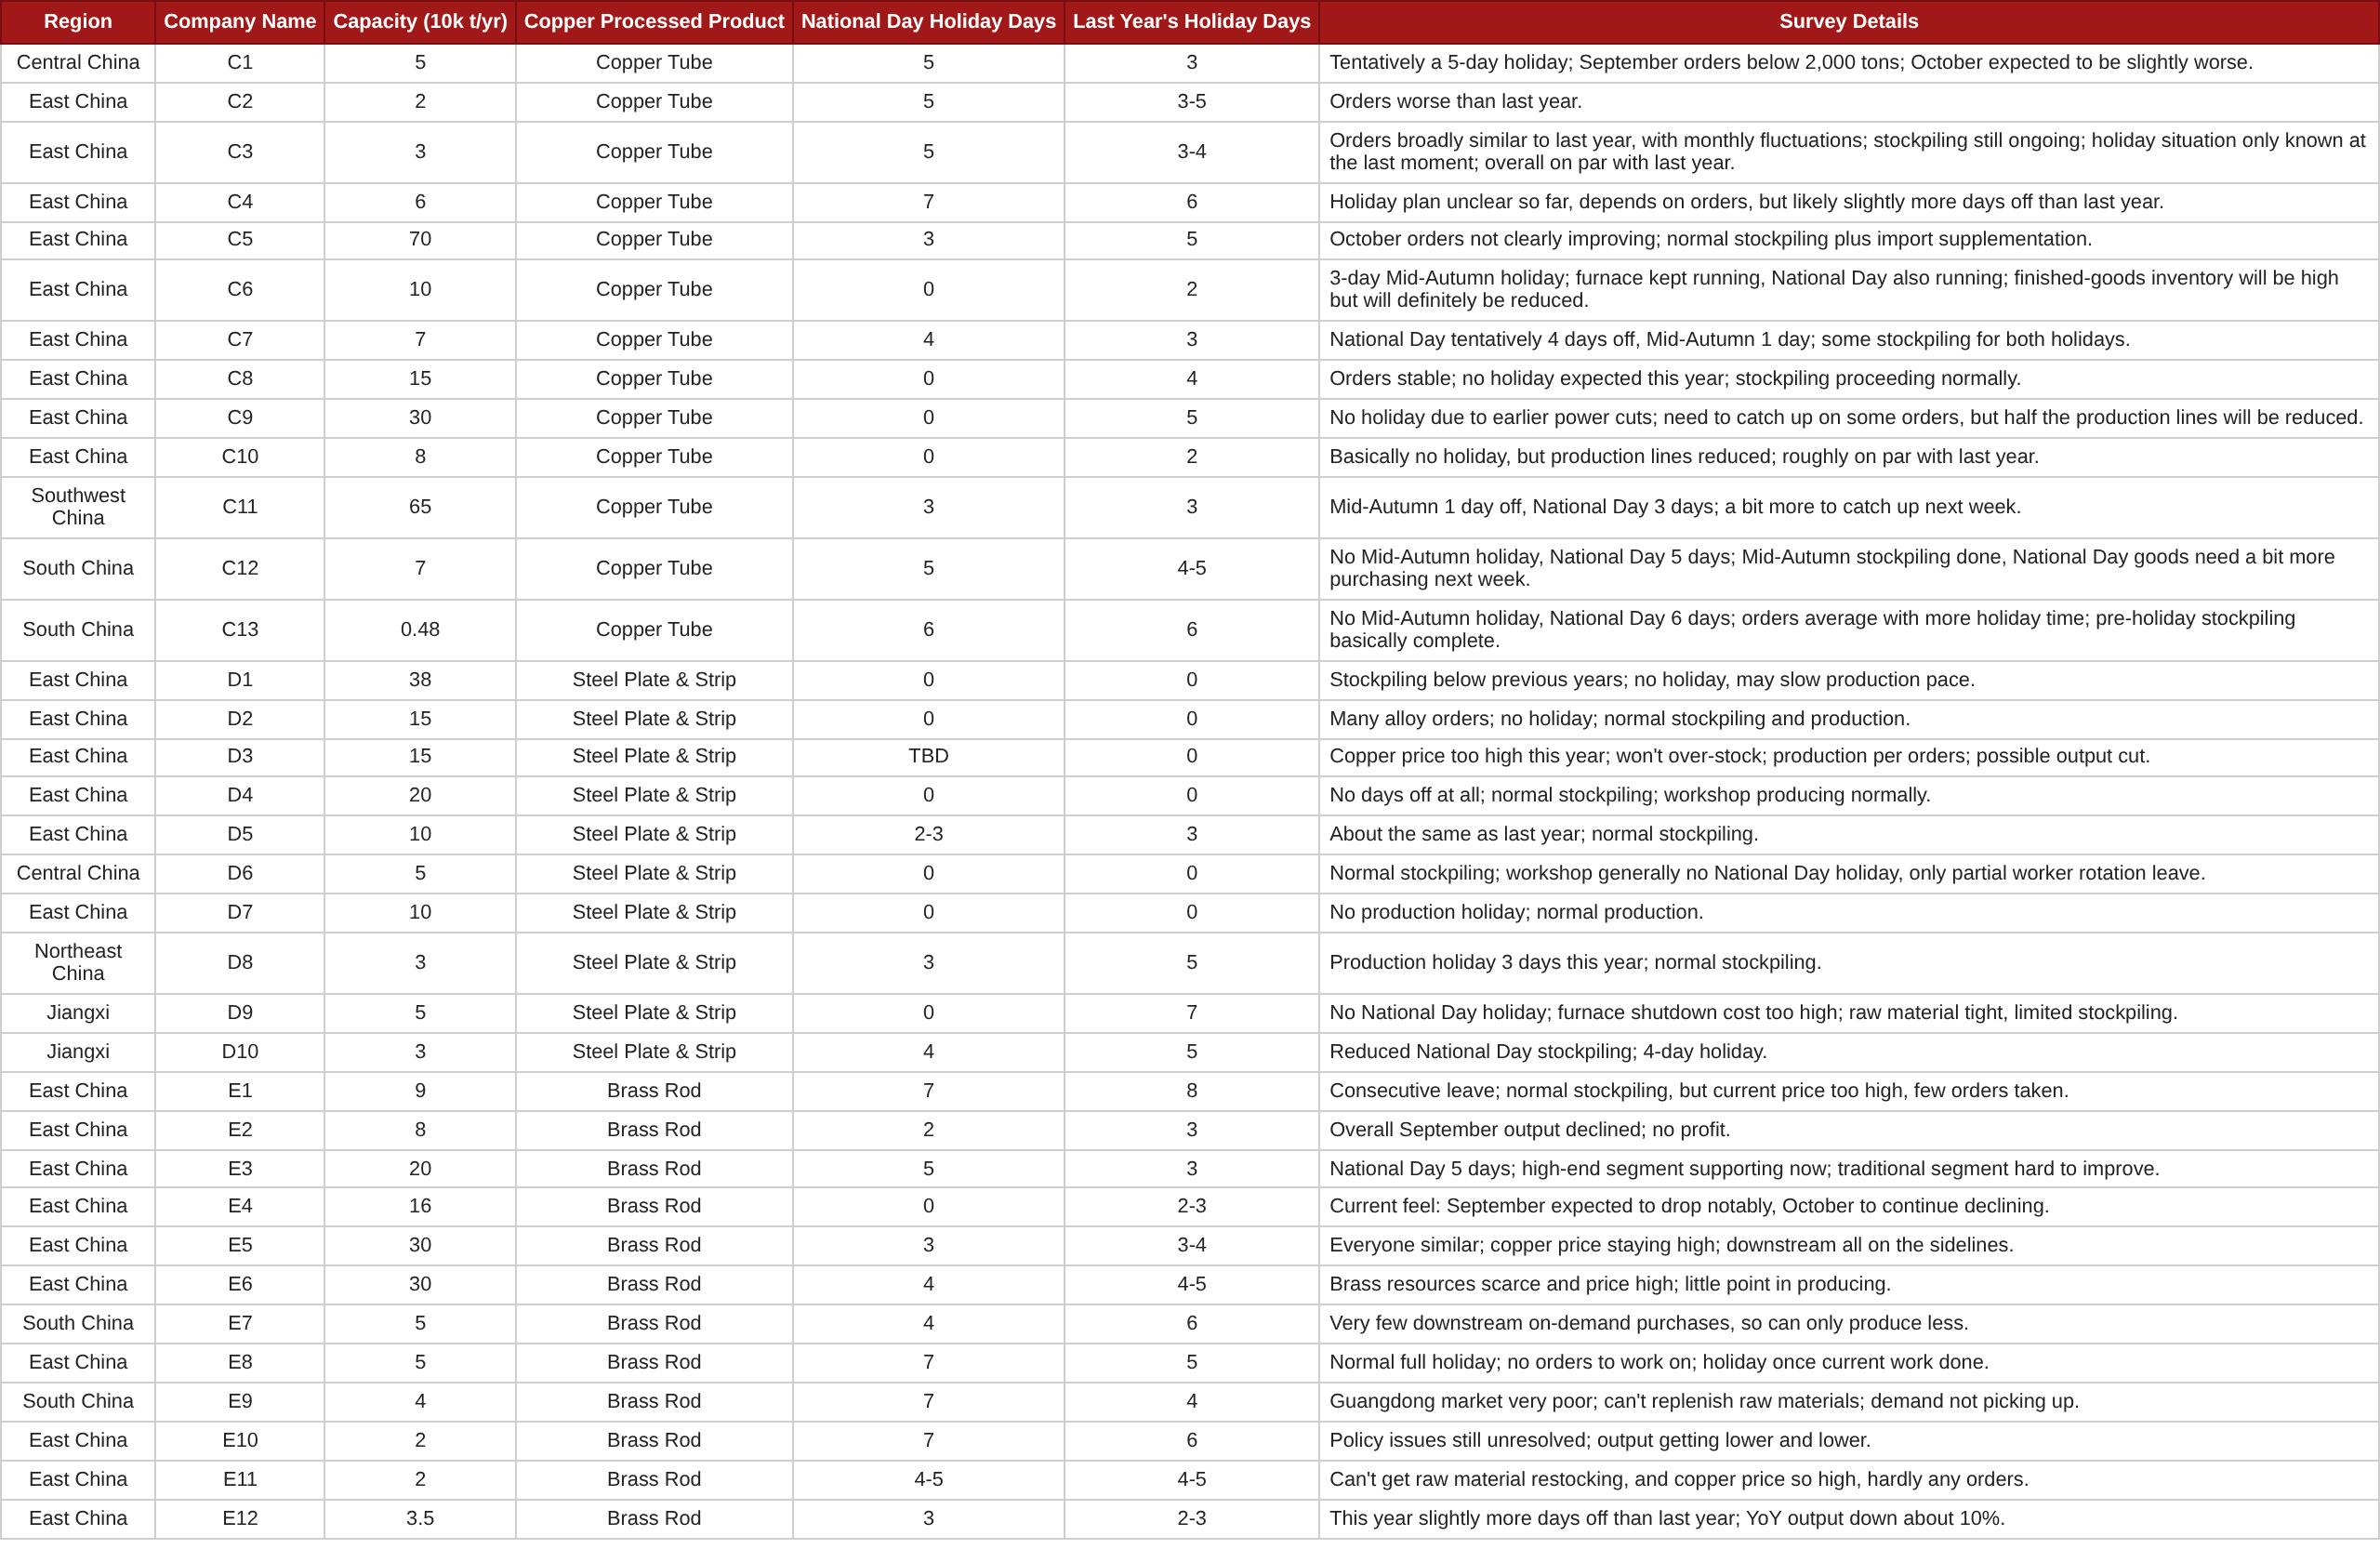
Copper pipe & tube: Holiday arrangements at copper pipe & tube enterprises tightened compared with last year, with the sample average holiday at about 3.3 days, 0.6 days shorter than last year. Some enterprises in east China maintained production during the National Day holiday without shutting down furnaces but reduced production lines. Before the holiday, copper prices were at historical highs, raising the capital cost of stockpiling. Enterprises were generally cautious in stockpiling, focusing mainly on rigid order demand. Large enterprises relied on long-term contracts and imported goods to replenish inventory, while small and medium-sized enterprises restocked small amounts as needed. As the decline in air conditioner production schedules narrowed and October production schedules turned positive YoY, the industry operating rate stabilized MoM and the YoY decline narrowed significantly. However, orders have not yet shown substantial improvement,and the recovery strength of the "October peak season" is expected to be mild, with the industry closer to weak stabilization than a strong rebound.
Copper plate/sheet and strip: The National Day holiday duration for copper plate/sheet and strip enterprises was generally shorter than last year. Large and medium-sized enterprises mostly maintained continuous production, while only a few small and medium-sized enterprises arranged short breaks of 2-4 days based on order conditions, and no enterprises had long-term production shutdowns for the holiday. Enterprises mostly carried out pre-holiday stockpiling in line with orders on hand, with most maintaining a normal stockpiling pace. However, affected by capital risks arising from high copper prices and high premiums, some enterprises adopted a more cautious stockpiling strategy and proactively controlled the scale of raw material stockpiling. October is the traditional peak season for the copper plate/sheet and strip industry, and the market expects end-use demand to continue recovering . Although high-priced raw materials will still limit the release of demand, ample orders on hand provide strong support, and the industry maintains a cautiously optimistic judgment on the peak season materializing.
Brass billet: Workers at sample enterprises generally had 4-5 days off during the National Day holiday, with the average holiday duration basically flat YoY, edging up by 0.08 days. Affected by both copper prices staying high and tightening supply of recycled brass raw materials, downstream stocking enthusiasm for brass billet was relatively weak, and the scale of pre-holiday stockpiling was notably lower than the same period last year. SMM expects actual brass billet production in September to be lower than in August. With copper prices fluctuating at highs, enterprises remained cautious about the market outlook and expect little notable improvement on the demand side in October.
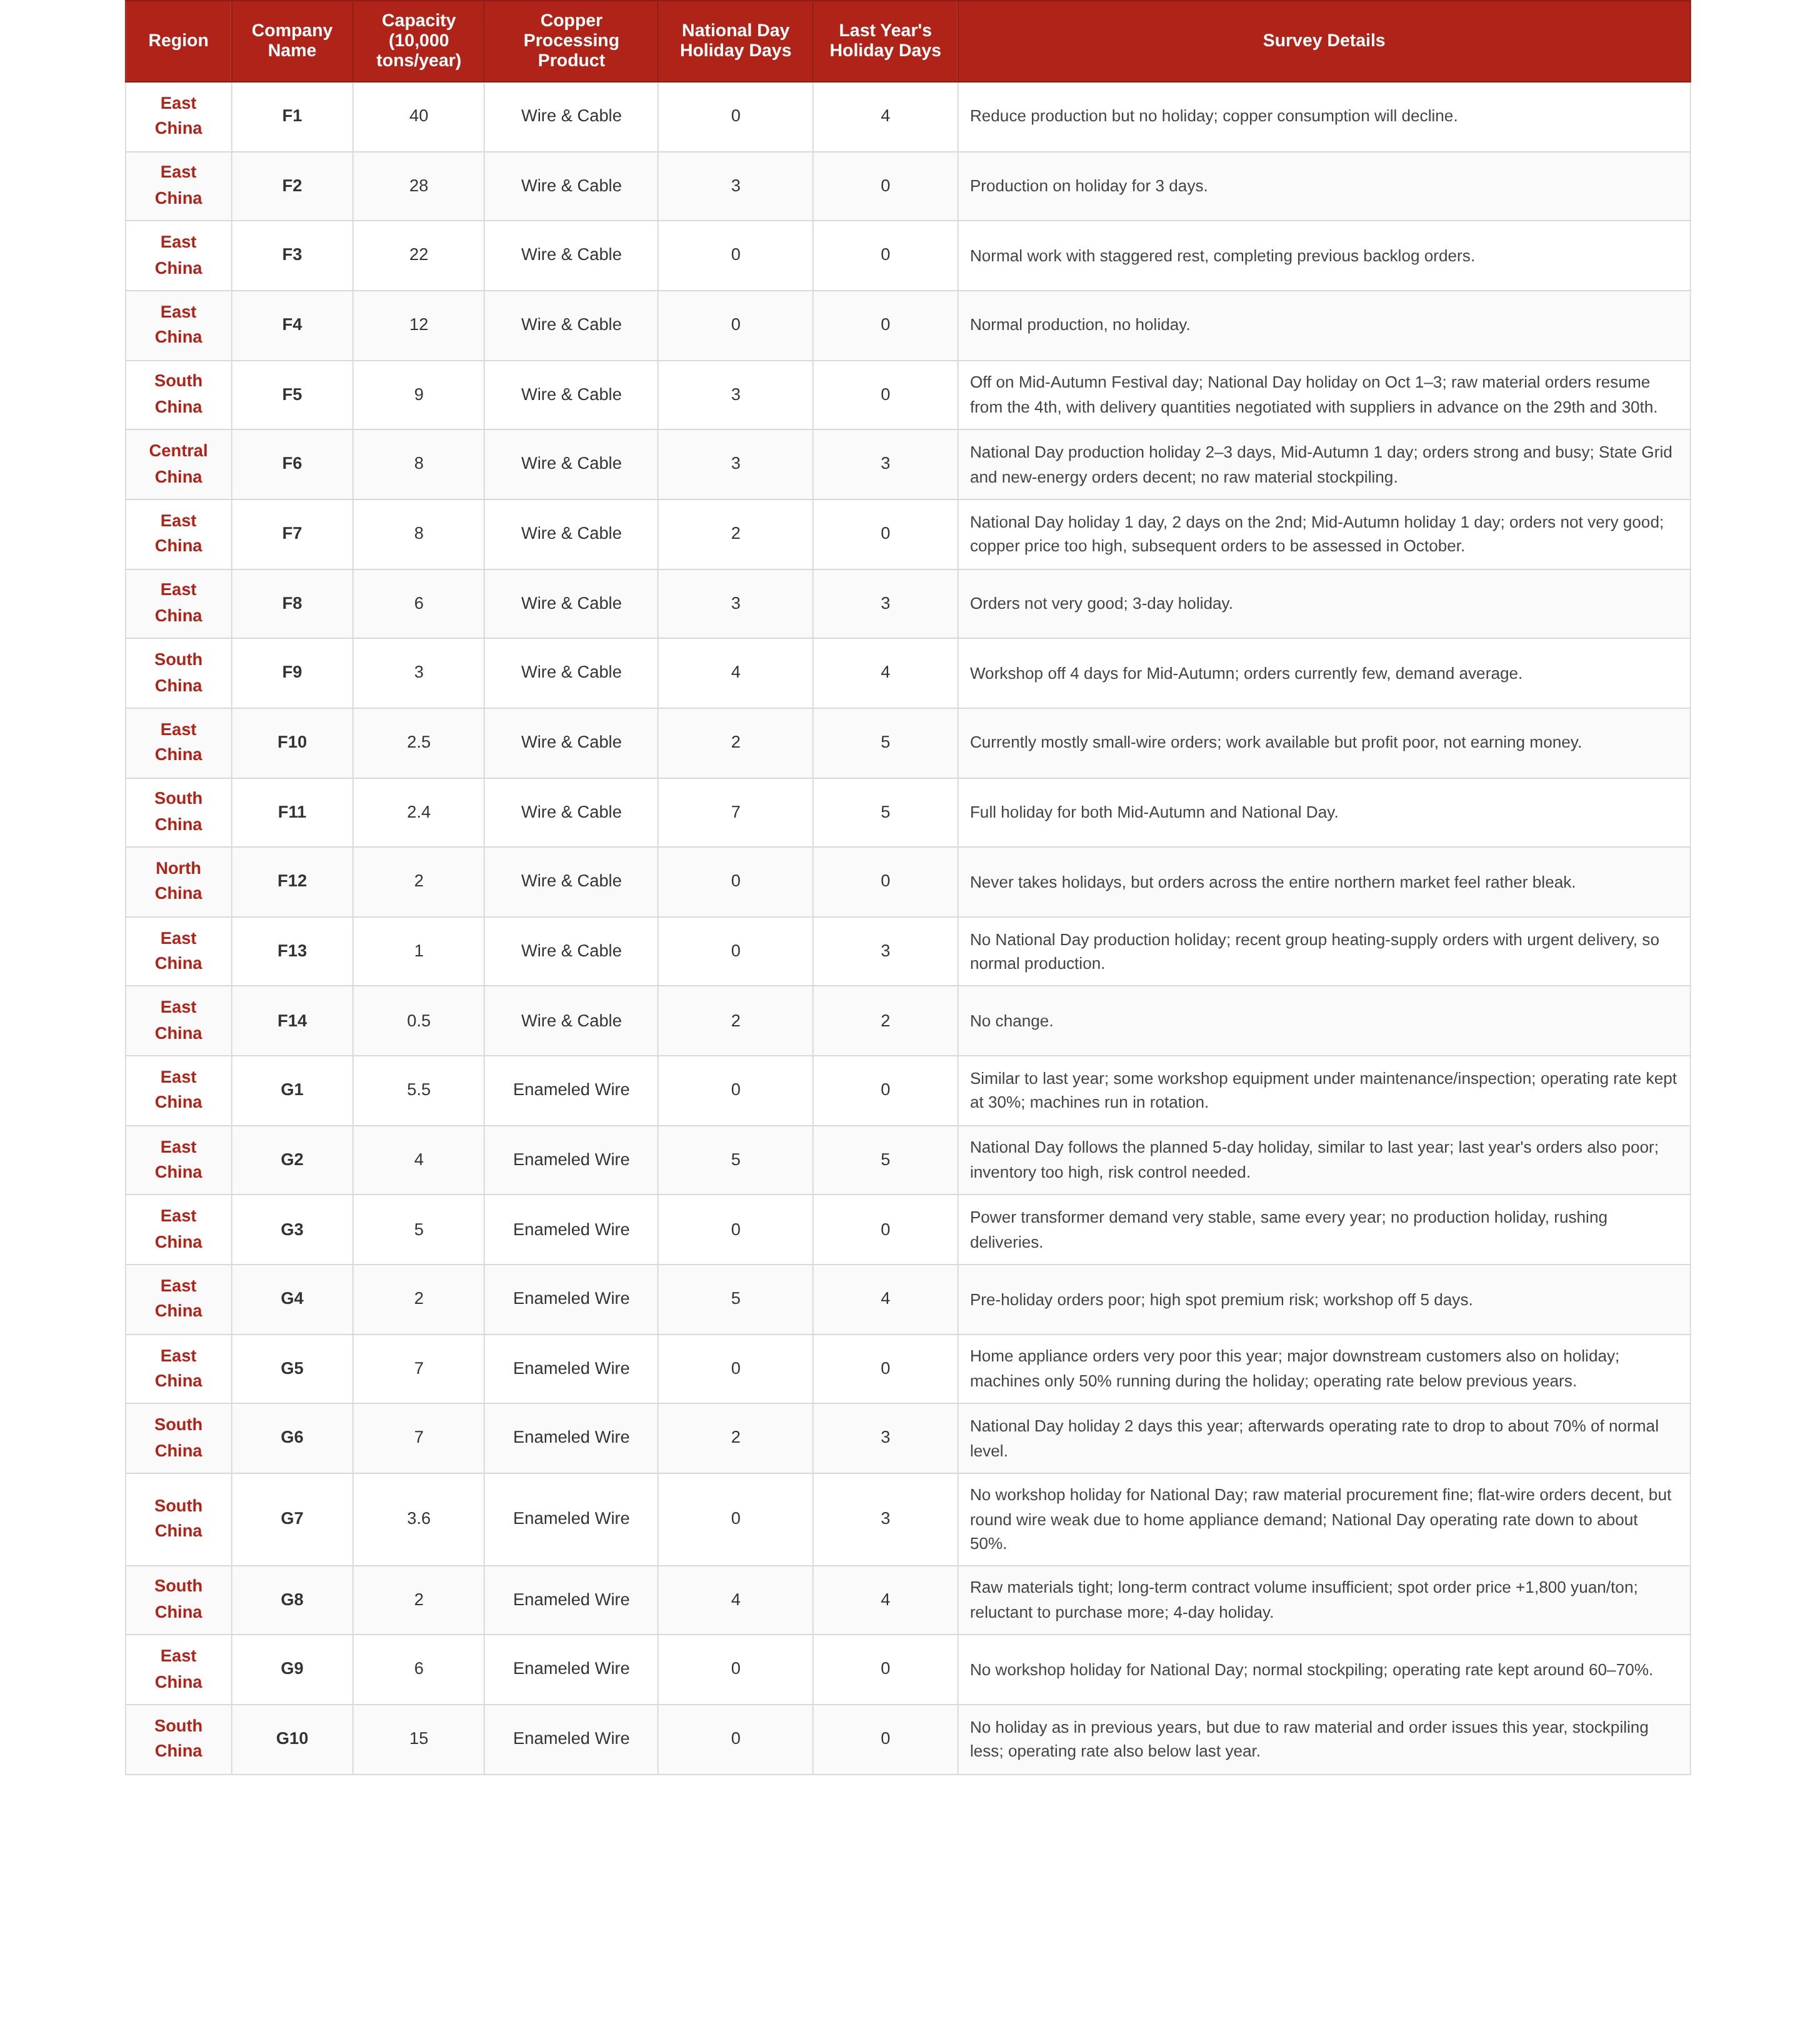
Wire and cable: Domestic wire and cable sample enterprises had an average holiday of 2.07 days, flat compared with last year . However, last year featured an 8-day consecutive break for National Day and Mid-Autumn Festival, while this year's National Day holiday was 7 days, meaning the statistical baseline was reduced by 1 day, indicating that the relative duration of actual production stoppages increased. Constrained by high copper prices and high premiums, compounded by weak end-use demand, enterprises showed weak willingness to stockpile before the holiday, mostly purchasing as needed and reducing advance stockpiling to avoid inventory depreciation risks. Leading wire and cable enterprises mostly did not halt production or made small production cuts to ensure delivery, while small and medium-sized plants flexibly adjusted production based on order conditions. Although the power sector is underpinned by rigid grid orders and demand in the new energy sector still shows resilience, end-user orders have not seen a substantive recovery in the traditional peak season. The market has concerns about the pace of procurement releases by State Grid and China Southern Power Grid in October, and underperformance in the peak season may become the mainstream judgment . If copper prices pull back, orders are expected to see marginal recovery.
Enamelled wire: The overall National Day holiday arrangements for enamelled wire enterprises changed little compared with last year, but production plans diverged notably among enterprises. Most enterprises kept their workshops running without shutdowns, adopting rotating shifts and reduced-load production to ensure delivery of orders on hand. Home appliance-related enterprises, due to weak demand, implemented holiday shutdowns and production cuts that exceeded expectations, and some enterprises under order pressure took concentrated breaks of 2-5 days. Affected by high copper prices and high premiums before the holiday, coupled with tight regional copper rod supply, enterprises remained cautious overall in raw material stockpiling and proactively managed inventory risks. Home appliance end-use demand recovery remained weak, and the industry held cautious expectations for October demand, with attention on post-holiday copper price performance and end-use demand recovery.
During the 2026 National Day holiday, the holiday schedules across copper processing sub-sectors diverged significantly. Among them, secondary copper rod production halts expanded notably in scope and extended in duration, while copper cathode rod and brass billet holidays were slightly lengthened. In contrast, copper pipe & tube, copper plate/sheet and strip, wire and cable, and enamelled wire enterprises mostly maintained production without full stoppages, opting for rotating shifts and reduced loads, resulting in relatively shorter actual downtime.High copper prices and high premiums before the holiday, combined with weak end-use demand in some segments, tight raw material supply, and policy and capital pressures, suppressed enterprises' stockpiling enthusiasm. Most enterprises avoided inventory risks and maintained restocking only for essential needs. Overall, the peak-season recovery in the copper processing industry in October remained limited, with operating rates in most sub-sectors under pressure YoY and weaker MoM. Only rigid demand from the power grid and new energy sectors, along with some peak-season segments, provided modest support, leaving the industry in a cautious, wait-and-see, weak-recovery operating pattern overall.