RKEF NPI plants at Indonesia’s Morowali Industrial Park began cutting production on September 22 because of water shortages, according to SMM’s survey. Operating loads are expected to decline by approximately 30–40% from previous levels. If sustained for half a month, the cuts would affect an estimated 50–70 kt of physical NPI output, equivalent to 5.5–7.7 kt of contained nickel at an 11% grade. If water shortages and reduced operating loads persist for longer, cumulative NPI production losses are expected to exceed 100 kt of physical material, equivalent to more than 11 kt of contained nickel.
The supply reduction comes as Chinese stainless steel demand remains weak. Subdued downstream buying and pressure on mill margins are driving lower production plans, with October 300-series output expected to decline by more than 100 kt month on month. NPI consumption would fall alongside it.
IMIP’s production cuts strengthen supply-side support for NPI prices, while lower Chinese stainless output weakens demand-side acceptance. The balance will depend on how long Indonesia’s water constraints persist and when Chinese stainless demand can support a recovery in production and procurement.
1. Weak demand and margins are driving lower Chinese production
October’s expected stainless production cuts need to be understood in the context of demand and profitability.
Subdued downstream buying reduces mills’ incentive to maintain high output. Producing more into a weak sales market increases inventory and working-capital pressure, encouraging mills to control production and adjust raw-material purchases.
SMM’s modelled margin for 304 cold-rolled stainless steel stood at minus 1.13% on September 22. Limited profitability restricts mills’ ability to absorb higher feedstock costs. The IMIP cuts may encourage NPI sellers to defend prices, while higher offers gaining acceptance will depend on improving stainless orders and selling prices.
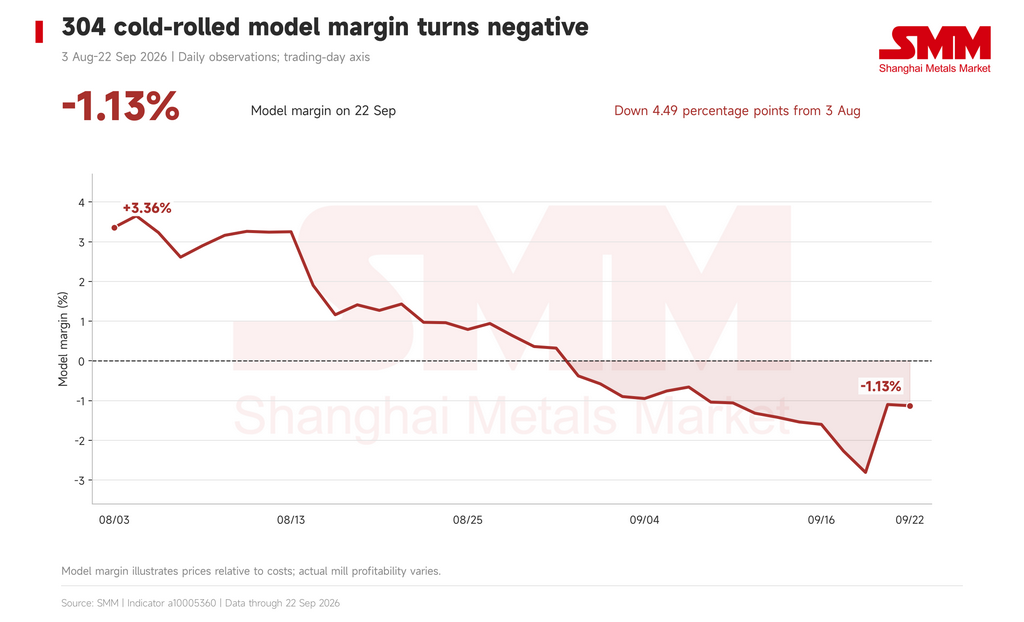
Figure 1 | The modelled 304 cold-rolled margin fell from 3.36% on 3 August to minus 1.13% on 22 September.
Lower production directly reduces raw-material consumption. Weak demand also affects mills’ willingness to rebuild inventories, making procurement volumes and timing more dependent on actual orders.
The October outlook therefore depends on both the scale of production cuts and their duration. A slow recovery in stainless demand could prolong cautious purchasing and delay a rebound in NPI consumption.
2. The initial supply and demand reductions are comparable
Using a 100 kt reduction in Chinese 300-series output and an assumed average nickel content of 8%, contained nickel demand would decline by approximately 8 kt. If NPI supplies 60–80% of that requirement, the corresponding reduction in NPI demand would be around 4.8–6.4 kt of nickel.
That is comparable with the 5.5–7.7 kt of nickel supply loss estimated under the half-month IMIP production-cut scenario.
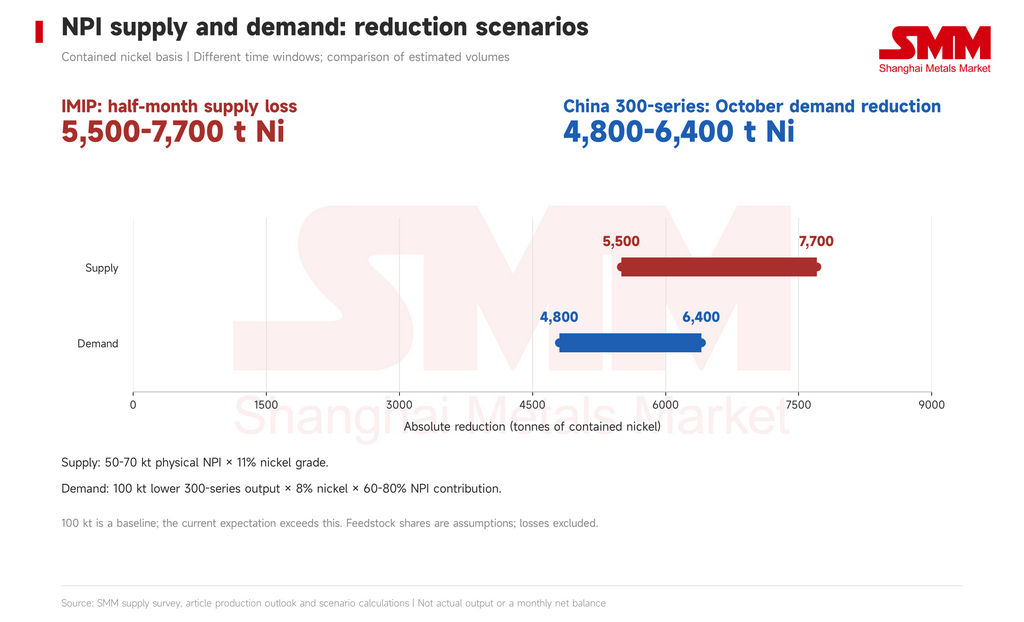
Figure 2 | Estimated NPI reductions use different time windows: half a month for IMIP supply and October for Chinese demand.
The Chinese calculation uses 100 kt as a comparison baseline; the current production-cut expectation exceeds that level. Nickel content and feedstock shares are scenario assumptions, with no separate adjustment for melting losses.
Lower Chinese output could therefore absorb a substantial share of the initial supply contraction. Production schedules, procurement, mill inventories and shipping arrangements will determine when those adjustments reach the physical market.
The immediate impact depends on the size of the cuts; their duration becomes increasingly important thereafter. A rapid improvement in IMIP’s water supply would leave weaker Chinese demand providing a substantial buffer. If the cuts persist for longer, cumulative NPI losses are expected to exceed 100 kt of physical material, or more than 11 kt of nickel at an 11% grade. That would exceed the estimated reduction in Chinese NPI demand for October outlined above, increasing supply pressure and reliance on existing inventories to cover the shortfall.
3. RKEF production needs reliable make-up water
RKEF production uses water to cool equipment, while some plants also require water for slag handling and gas cleaning. Reliable cooling supports sustained furnace operation. From a process perspective, lower operating loads can reduce cooling requirements when water supply becomes constrained.
Recycling saves water, while continued production still requires replenishment. Evaporation and other losses need to be replaced. Prolonged dry conditions and reduced river flows can therefore affect production even where recycling systems are installed. The recovery outlook depends on a reliable make-up water supply being restored.
4. IMIP uses river water, making replenishment central to recovery
IMIP’s 2023 sustainability report describes rainwater recovery, water treatment and industrial water recycling at ferronickel and stainless steel plants. The government’s project profile also lists clean-water treatment infrastructure. These sources describe river abstraction, treatment and reuse; the capacity and operating status of seawater desalination facilities require further verification.
Provincial records published in August confirm IMIP’s use of the Makarti River under a permit held since 2024. The maximum permitted abstraction rate is 1.5 m³/s, equivalent to 129,600 m³/day at continuous operation. Pump-house and intake infrastructure are also documented. Actual dry-season availability depends on river flows and operating conditions.
Rainfall evidence illustrates the pressure. Nickel Industries reported less than 4 mm of August rainfall at nearby Hengjaya Mine, against a historical August average of 222 mm. That observation applies to the mine location. BMKG forecasts predominantly low rainfall across Morowali for September 21–30, in the 0–50 mm range.
Recovery consequently depends on sustained rainfall translating into reliable inflows. The half-month estimate is a production-loss scenario; actual recovery will follow water availability. Catchment rainfall, river flows and plant operating rates are the relevant indicators, while current abstraction and stored-water volumes remain unavailable in the public material reviewed.
5. Lower river levels are also affecting coal logistics
Dry conditions are extending into raw-material transport.
Indonesia’s coke industry association, APUKN, reported in early September that lower water levels on the Barito River were forcing some barges carrying coking coal from Kalimantan to reduce loads or adjust sailing schedules.
For buyers using these routes, lower barge loads reduce the volume moved per voyage, while schedule changes can lengthen delivery times and increase logistics costs. Operators with limited raw-material inventories are more exposed to changes in arrivals.
Coking-coal transport has already been affected. The implications for individual IMIP operators depend on sourcing, inventories and transport arrangements. Coal logistics therefore warrant monitoring as an additional supply-chain exposure alongside water availability.
Industrial water supply and raw-material deliveries may recover at different speeds, potentially affecting the pace at which individual operations restore production.
6. Inventories cushion the disruption, while demand determines price acceptance
Chinese port NPI inventories had accumulated before the IMIP cuts.
SMM data put stocks at 53.8 kt of contained nickel on September 17, up from 35.3 kt on September 3. The increase of approximately 18.5 kt, or 52.5%, provides a buffer against a near-term reduction in arrivals and gives mills room to adjust procurement. Ownership, grade and the availability of material for sale will affect how quickly those stocks can meet demand.
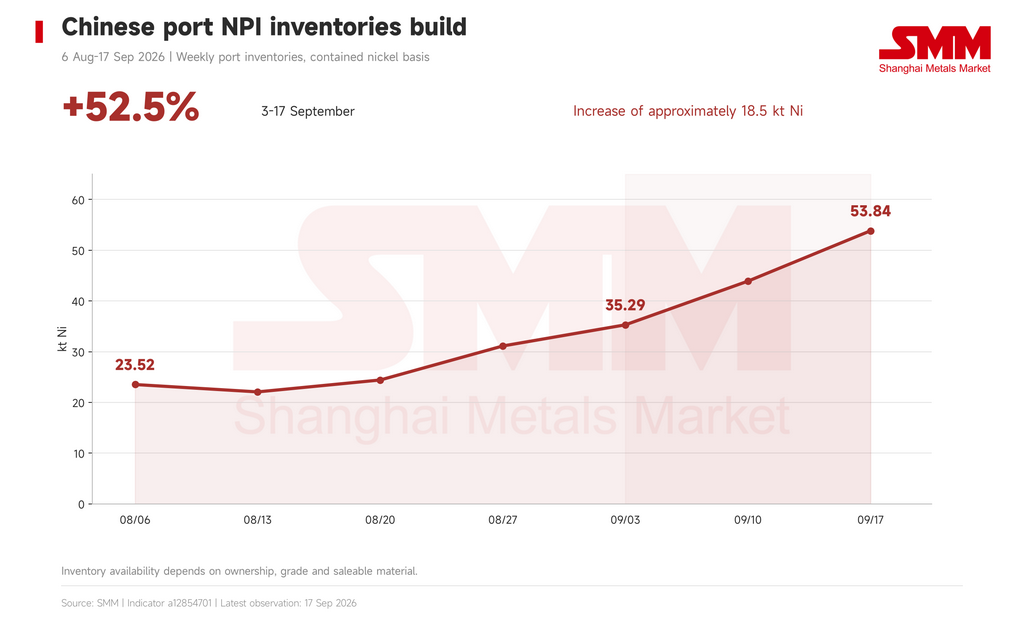
Figure 3 | Chinese port NPI inventories rose 52.5% between 3 and 17 September, reaching 53.8 kt Ni.
Prices also show the pressure preceding the disruption. SMM’s domestic high-grade NPI ex-works average fell from RMB 1,114/mtu at the end of August to RMB 1,039.5/mtu on September 22. The Indonesian NPI FOB average declined from USD 144.5/mtu to USD 135/mtu over the same period. An mtu represents 10 kg of contained nickel.
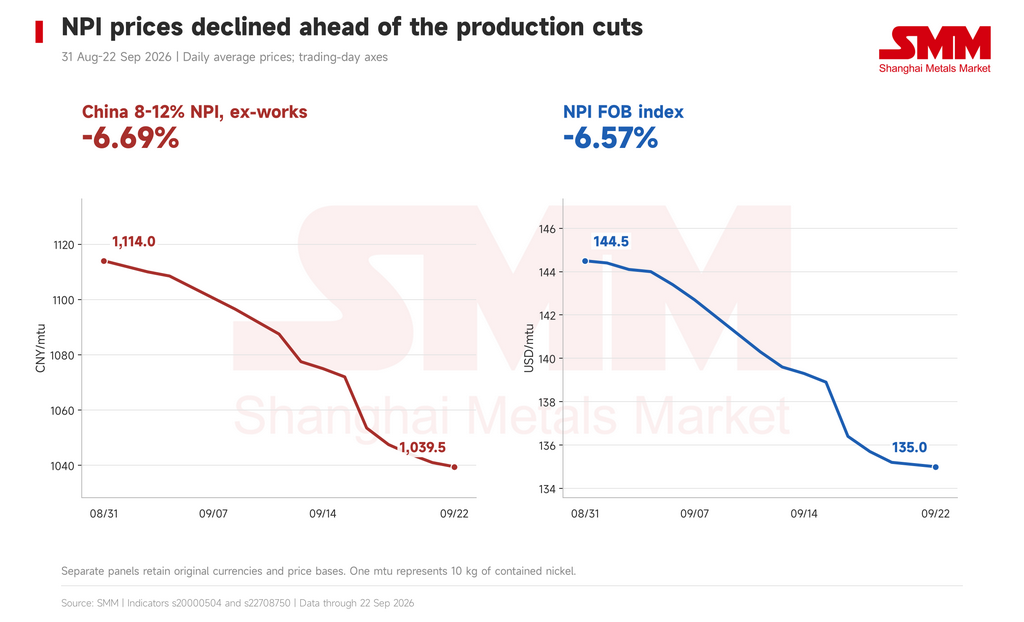
Figure 4 | From 31 August to 22 September, the Chinese ex-works NPI average fell 6.69% and the NPI FOB index fell 6.57%.
Production cuts strengthen sellers’ case for stabilising offers. Sustained price increases require purchasing support, however, and weak stainless demand leaves mills with limited capacity to absorb higher costs.
If water availability improves quickly, China’s October production cuts and existing port stocks could cushion the disruption. If reduced IMIP operating rates persist for longer and cumulative NPI losses exceed 100 kt of physical material, inventory drawdowns would gradually reduce the available buffer and strengthen supply-side price support. Continued weakness in Chinese stainless demand could nevertheless keep procurement cautious and constrain NPI price gains.
The key indicators are actual Chinese 300-series production, IMIP operating rates and Chinese port inventory changes. Persistent supply losses, inventory drawdowns and recovering mill purchases would together provide a stronger basis for sustained price support.
As Indonesia’s smelting industry expands, river availability, industrial make-up water and transport conditions are becoming increasingly important measures of effective capacity. Assessing reliable NPI supply requires those operating conditions to be considered alongside installed capacity.
Written by Bruce Chew
Nickel & Stainless Steel Analyst, Shanghai Metals Market
Email: bruce.chew@metal.com
Tel: +601167087088