SMM September 23 news:
In the metals market:
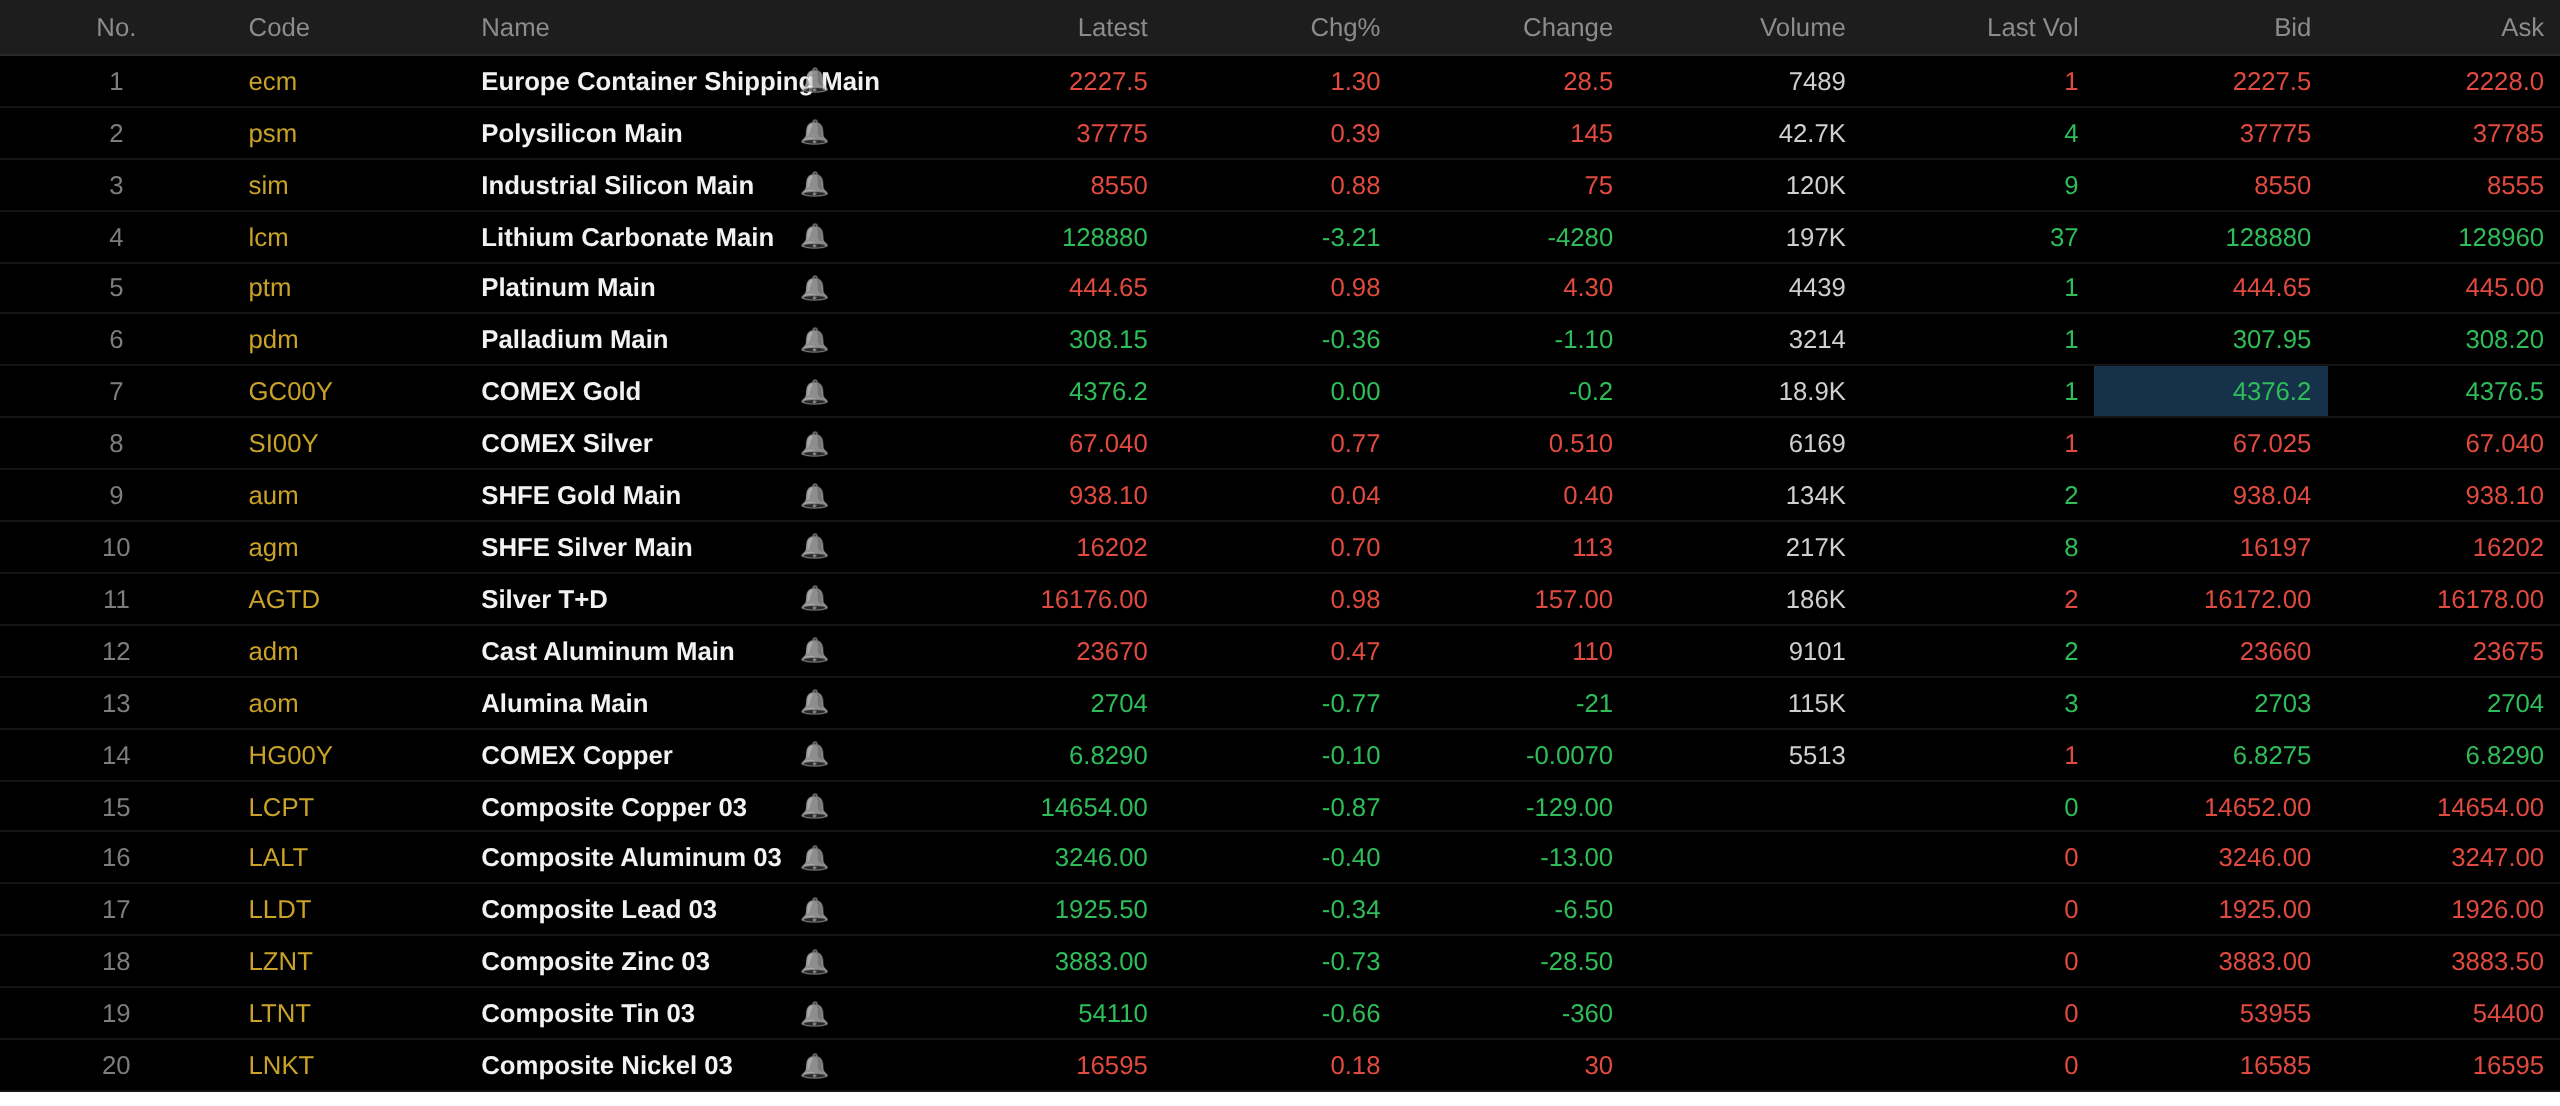
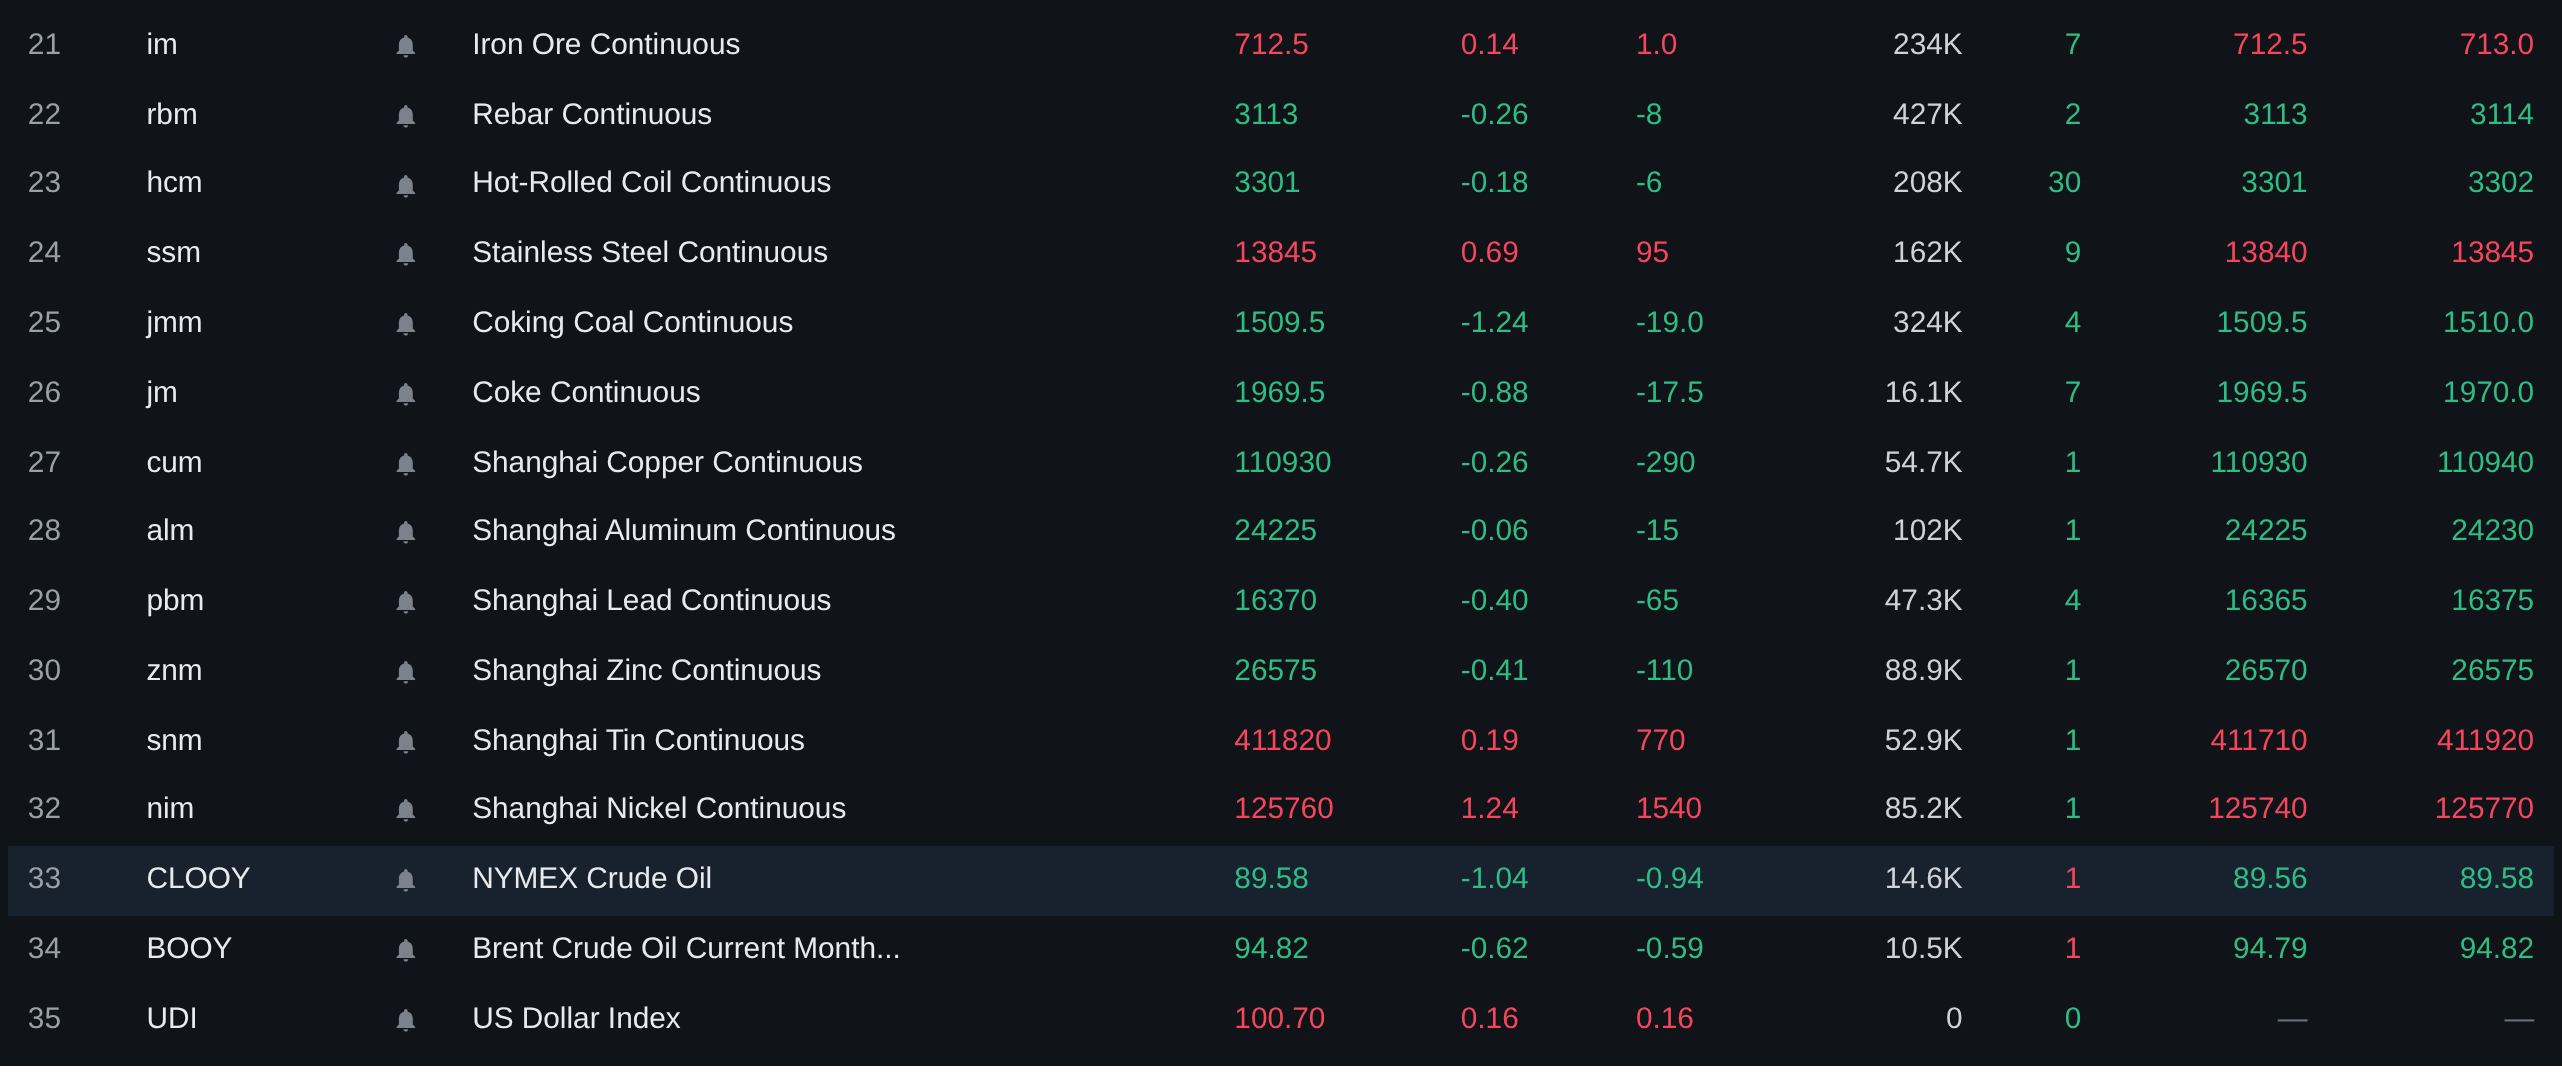
As of the midday close, base metals in the domestic market mostly fell. SHFE copper fell 0.26%. SHFE aluminum edged down. SHFE lead and SHFE zinc both fell within 0.5%. SHFE tin rose 0.19%, and SHFE nickel rose 1.24%.
In addition, the most-traded casting aluminum futures contract rose 0.47%, while the most-traded alumina contract fell 0.77%. The most-traded lithium carbonate contract fell 3.21%. The most-traded silicon metal contract rose 0.88%. The most-traded polysilicon futures contract rose 0.39%.
Ferrous metals mostly fell. Iron ore rose 0.14%, rebar fell 0.26%, and hot-rolled coil fell 0.18%. Stainless steel rose 0.69%. In coking coal and coke: the most-traded coking coal contract fell 1.24%, and the most-traded coke contract fell 0.88%.
In overseas base metals, as of 11:41, LME metals were nearly all down. LME copper fell 0.87%, and LME aluminum fell 0.4%. LME lead fell 0.34%, and LME zinc fell 0.73%. LME tin fell 0.66%. LME nickel rose 0.18%.
In precious metals, as of 11:41, COMEX gold was flat at $4,376.2/oz, and COMEX silver rose 0.77%. In domestic precious metals: SHFE gold rose 0.04%, and the most-traded SHFE silver contract rose 0.7%.
In addition, as of the midday close, the most-traded platinum futures contract rose 0.98%, and the most-traded palladium futures contract fell 0.36%.
As of the midday close, the most-traded European shipping futures contract rose 1.3% to 2,227.5 points.
As of 11:41 on September 23, midday quotes for some futures:
Spot and fundamentals
Copper: Today, Guangdong #1 copper cathode spot against the front-month contract: high-quality copper was quoted at a premium of 1,400 yuan/mt, up 100 yuan/mt from the previous trading day; standard-quality copper was quoted at a premium of 1,100 yuan/mt, up 100 yuan/mt from the previous trading day; SX-EW copper was quoted at a premium of 1,040 yuan/mt, up 100 yuan/mt from the previous trading day. The average price of Guangdong #1 copper cathode was 112,615 yuan/mt, up 380 yuan/mt from the previous trading day, and the average price of SX-EW copper was 112,405 yuan/mt, up 380 yuan/mt from the previous trading day. Spot market: Guangdong inventory continued to decline today, falling for two consecutive days, mainly due to reduced arrivals and increased warehouse withdrawals, with increased stockpiling ahead of the Mid-Autumn Festival...
Macro front
Domestic:
[National Energy Administration: As of end-August 2026, China's EV charging infrastructure (guns) totaled 24.223 million] On September 23, the National Energy Administration released national EV charging facility data for August 2026. According to data from the national charging facility monitoring service platform, as of end-August 2026, China's EV charging infrastructure (guns) totaled 24.223 million, up 39.6% YoY. Of this, public charging facilities (guns) totaled 5.16 million, up 19.5% YoY, with total rated power reaching 262 million kW and average power per gun at approximately 50.69 kW; private charging facilities (guns) totaled 19.063 million, up 46.3% YoY, with installed electricity capacity for private charging facilities reaching 163 million kVA. (Jinshi Data APP)
[Shanghai Gold Exchange: Notice on market risk control during the 2026 Mid-Autumn Festival and National Day holidays] The Shanghai Gold Exchange issued a notice on market risk control during the 2026 Mid-Autumn Festival and National Day holidays: During the Mid-Autumn Festival, the exchange's deferred contracts will maintain existing margin ratios and price limits unchanged; starting from the close of clearing on September 28, 2026 (Monday), margin ratios for Au (T+D), mAu (T+D), Au (T+N1), Au (T+N2), NYAuTN06, and NYAuTN12 contracts will be adjusted from 15% to 18%, and price limits will be adjusted from 14% to 17% from the next trading day; the margin ratio for the Ag (T+D) contract will be adjusted from 21% to 24%, and the price limit will be adjusted from 20% to 23% from the next trading day. (Shanghai Gold Exchange)
[PBOC reverse repo operations achieve a net withdrawal of 102 billion yuan on the day] The PBOC conducted 8 billion yuan of 7-day reverse repo operations today. With 110 billion yuan of 7-day reverse repos maturing today, a net withdrawal of 102 billion yuan was achieved on the day. (Jinshi Data APP)
US dollar:
As of 11:41, the US dollar index rose 0.16% to 100.7. According to CME "FedWatch": The probability of the Fed keeping rates unchanged at 3.75%-4.00% at the October meeting is 45.8%, and the probability of a 25 bp hike is 54.2%. The probability of the Fed keeping rates unchanged at 3.75%-4.00% by December is 10.8%, the probability of cumulative 25 bp hikes is 47.8%, and the probability of cumulative 50 bp hikes is 41.4%. (Jinshi Data APP)
Shenwan Hongyuan Research recently released a research report stating that the US dollar index is positively correlated with oil prices in the short term, and during supply shock phases, safe-haven demand and relative fundamental advantages often cause the dollar to strengthen alongside oil prices; if the US-Iran conflict expands, the US dollar index still faces upward pressure, and after easing, the core fluctuation range may return to 97-103. A trend strengthening of the US dollar index typically occurs during sustained Fed rate hike phases. The September hike has landed, but if future hikes are only sporadic rather than a trend tightening cycle, the risk of a trend appreciation in the dollar remains relatively controllable. Looking ahead to H2, the core fluctuation range for the 10-year US Treasury yield may be between 4.5% and 5%, with inflation expectations and oil price linkage being the most core variable for short-term rates; in an optimistic scenario, it may pull back to 4.3%, while in a pessimistic scenario, it may break above 5%. In the medium term, US Treasury term premiums are prone to rise and hard to fall, and US Treasury risks have escalated from cyclical fluctuations to concerns about US fiscal sustainability, the Fed's triple dilemma of "sticky inflation, weak employment, and automatic tightening from long-term debt," and the "gray rhino" of global savings cycle imbalances. Current US equity valuations are not low, and the stronger and longer-lasting the shock, the greater the damage to stock prices.
Fed's Williams on Tuesday defended the system through which the Fed implements monetary policy, while stating that the system can be adjusted and optimized as financial markets evolve. Williams said that using the current suite of tools to manage short-term rates and provide "ample" reserves to the financial system "has proven to be very effective in achieving interest rate control and supporting the smooth functioning of core financial markets." Williams' remarks that day did not touch on monetary policy or the rate outlook, and he was not scheduled to take questions after his speech. The New York Fed president said that while the Fed's rate control framework works well, it is not set in stone and can be adjusted as market conditions change. Williams said: "As markets continue to evolve, we must ensure that our policy tools can meet their objectives to fulfill their necessary functions. Simply put, the evolution of financial market structure will also drive the evolution of how we effectively implement monetary policy." (Jinshi Data APP)
Fed's Barkin warned that inflation shocks may take some time to ease, and there is a risk that inflation pressures stay high and become entrenched. Barkin said the Fed's rate hike last week will help slow inflation, but he did not explicitly say whether further tightening is needed. Instead, the Fed official emphasized that supply shocks are no longer just sporadic or temporary phenomena, but persistent price pressures affecting the entire economy. "These conditions may fade over time, but I expect it will still take some time," Barkin said. "During this period, the current high inflation levels may have an impact on future inflation." Barkin noted, "What do we do next? We are committed to sustainably bringing inflation down to the 2% target. Last week's rate hike will help with that. Do we need further hikes, and how many? We'll see." The Fed official also laid out two inflation scenarios: the first is that recent shocks gradually fade and price pressures cool rapidly; the second is that inflation pressures persist. "I am open to the possibility that inflation may come down soon. Some recent shocks may reverse," Barkin said, adding that consumers may "hit their limits," investment growth may slow, and employment may also "fluctuate." "On the other hand, inflation may be harder to suppress than expected. Temporary shocks may persist," he said. "New cost pressures may emerge. Stronger demand may feed through to prices, and the impact of today's inflation may do the same." (Jinshi Data APP)
Data:
Today will see the release of the US September S&P Global manufacturing PMI flash, US September S&P Global services PMI flash, France September manufacturing PMI flash, Germany September manufacturing PMI flash, Eurozone September manufacturing PMI flash, UK September manufacturing PMI flash, UK September services PMI flash, and other data.
In addition, watch for: President Xi Jinping's state visit to the US from September 23 to 25. 2027 FOMC voter and Richmond Fed President Barkin will speak, and Fed Governor Barr will speak on the theme of "housing." In France, the OECD will release its interim Global Economic Outlook report. Vice Premier He Lifeng will lead a delegation to the US from September 19-23 for economic and trade consultations with the US side, and Iranian President Pezeshkian will speak at the UN General Assembly. Due to contract rollover, the NYMEX New York October crude oil futures will complete their final floor trading at 2:30 on September 23 and final electronic trading at 5:00 am. Please pay attention to exchange notices on contract expiration and rollover for risk control. In addition, some trading platforms' US oil contract expiration times are typically one day earlier than the official NYMEX date, so please pay close attention.
Crude oil:
As of 11:41, oil prices in both markets extended declines from the previous five trading days, with US oil falling 1.04% and Brent falling 0.62%.
According to Iran's Fars News Agency, Iranian sources said that reports from Reuters and Kyodo News about the opening of the Strait of Hormuz are unreliable and untrue. Positive news about Iran-US negotiations and the possible reopening of the Strait of Hormuz had earlier emerged simultaneously, once again affecting the oil market and pushing oil prices lower. (Jinshi Data APP)
According to three people familiar with the matter, Saudi Arabia has restarted operations of its east-west crude oil pipeline and may resume oil exports from the Red Sea port of Yanbu later on Tuesday. Two of the sources said the pipeline is currently operating at low throughput. (Jinshi Data APP)
Preliminary shipping data showed that three commodity vessels passed through the Strait of Hormuz on Tuesday, down from four a day earlier and below the 10-day moving average of about 15. According to shipping tracking firm Kpler, the three vessels, including one Panamax tanker, were all exiting the strait. However, according to the data, an empty LNG tanker, Al Mafyar, reappeared in the strait on Tuesday after last being seen outside the waterway on September 19. Meanwhile, 22 commodity vessels passed through the Bab el-Mandeb Strait on Tuesday. Data showed that 14 of them were heading toward the Red Sea and 8 toward the Gulf of Aden. They included 5 Panamax tankers, 6 Supramax vessels, 4 Aframax tankers, 1 Suezmax tanker, and 1 very large crude carrier. This figure was down from the 10-day average of 26 vessels. (Jinshi Data APP)
Spot market overview:
►
►
Midday comments on other metals spot will be updated later, please refresh to view~