Imports Down, Exports Up: China's Net Copper Cathode Imports Fell in August 2026 [SMM Analysis]

Published: Sep 22, 2026 13:46 (GMT+8)
SMM Analysis: According to data from the General Administration of Customs, China imported 210,200 mt of copper cathode in August 2026, down 14.24% MoM and down 20.48% YoY...

SMM September 22 News:

According to data from the General Administration of Customs, China imported 210,200 mt of copper cathode in August 2026, down 14.24% MoM and down 20.48% YoY. Cumulative imports from January to August totaled 1.8837 million mt, down 15.22% YoY.
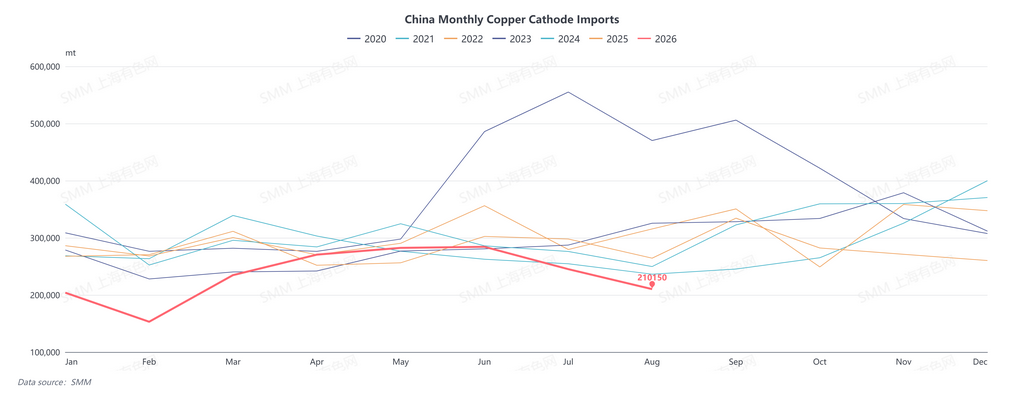
China's copper cathode imports remained at a low level in August, with the core reason still being the siphoning effect of the US.

By source country, in August, China imported 69,300 mt of copper cathode from the DRC, its largest source country, down 27.66% MoM and down 41.45% YoY. Imports from Chile totaled 10,800 mt, down 28.92% MoM and down 30.86% YoY. As market expectations for US tariffs had been building earlier, the COMEX-LME price spread widened, and global copper resources once again concentrated in North America. In August, copper cathode imports from Asian regions showed growth, with imports from China totaling 47,000 mt, up 309.14% MoM and up 2,603.96% YoY. This was mainly because import arbitrage opportunities emerged intermittently in mid-July, prompting some cargoes to be imported from LME warehouses into China.
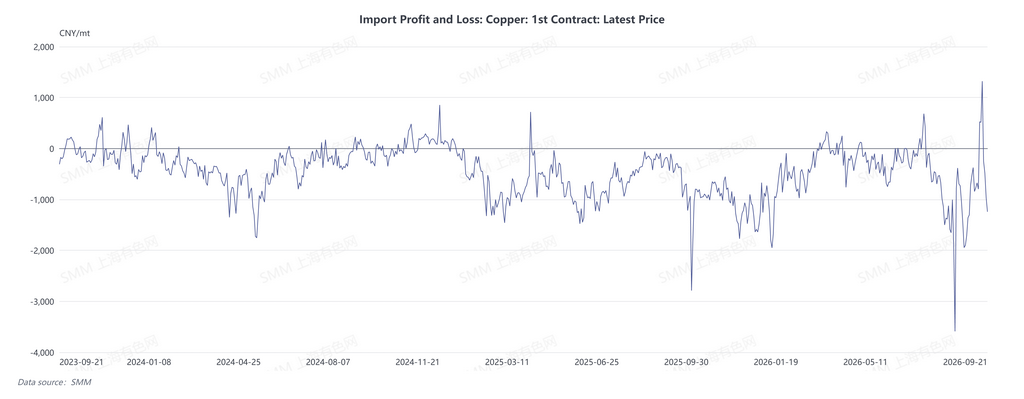
In addition, typhoon weather in August caused persistent port congestion across multiple regions in China, leading to delays in some import arrivals.

On the export side, apart from re-exports to the US, from late July through August, import arbitrage remained persistently inverted, LME maintained a high backwardation structure, and the export window opened intermittently on multiple occasions, driving growth in China's copper cathode exports in August.

In August 2026, China exported 50,400 mt of copper cathode, up 44.67% MoM and up 37.02% YoY. Cumulative exports from January to August totaled 409,000 mt, down 10.57% YoY.
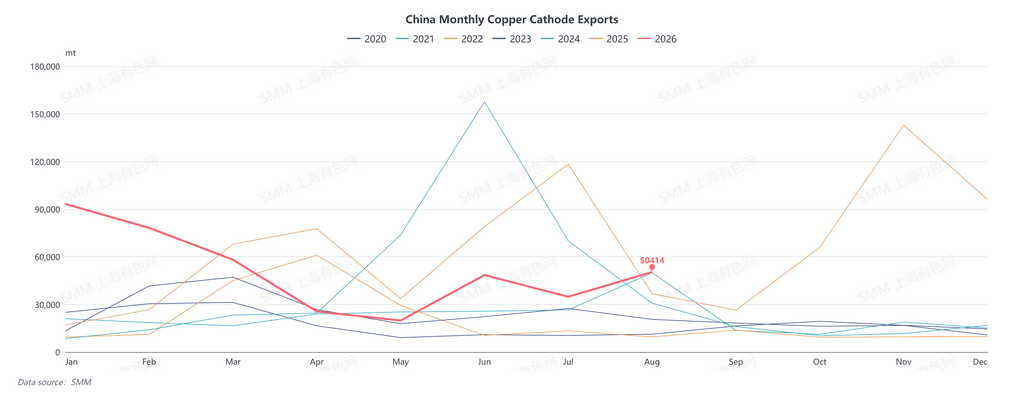
Looking ahead, the LC price spread narrowed in September, weakening re-export momentum. With China's copper cathode social inventory at low levels and downstream rigid demand during the peak consumption season, coupled with the arrival of some cargoes delayed by earlier port congestion, imports are expected to rebound in September. However, given the overall unfavorable import arbitrage from August to September, the room for import growth is expected to be limited. On the export side, the export window opened intermittently again in late September. However, with domestic spot premiums for copper cathode surging sharply and low copper cathode inventories leaving smelters with tight supply, China's copper cathode exports are expected to decline MoM in September.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Tight available supply drives premiums sharply higher; caution needed over weakening downstream acceptance amid high prices and high backwardation [SMM Shanghai Spot Copper]
8 mins ago
Tight available supply drives premiums sharply higher; caution needed over weakening downstream acceptance amid high prices and high backwardation [SMM Shanghai Spot Copper]
Read More
Tight available supply drives premiums sharply higher; caution needed over weakening downstream acceptance amid high prices and high backwardation [SMM Shanghai Spot Copper]
Looking ahead to tomorrow, available supply in the Shanghai region is expected to remain tight, and with some downstream processing enterprises still having pre-holiday stockpiling demand, spot premiums continue to receive strong support. Although a small amount of imported copper locked in at favorable SHFE/LME price ratios after the import window opened earlier is gradually arriving, the overall volume is limited, and its supplementary effect on market supply is expected to be relatively modest in the short term, making it difficult to significantly ease the current supply tightness. Therefore, spot premiums are expected to have further room to rise tomorrow. However, copper prices are already at elevated levels, the backwardation between prompt and forward months has widened simultaneously, and spot premiums have climbed rapidly, leading to a notable increase in procurement costs for downstream and end-user enterprises, which may gradually reduce their acceptance of high premiums. If premiums continue to rise rapidly, some downstream buyers may turn to a wait-and-see stance, just-in-time procurement may decrease, and market trading activity may pull back. Market participants are advised to monitor the risk of negative feedback on the demand side amid the combined effects of high copper prices, high backwardation, and high premiums.
8 mins ago
Tight available supply drives premiums sharply higher; caution needed over weakening downstream acceptance amid high prices and high backwardation [SMM Shanghai Spot Copper]
9 mins ago
Tight available supply drives premiums sharply higher; caution needed over weakening downstream acceptance amid high prices and high backwardation [SMM Shanghai Spot Copper]
Read More
Tight available supply drives premiums sharply higher; caution needed over weakening downstream acceptance amid high prices and high backwardation [SMM Shanghai Spot Copper]
[SMM Shanghai Spot Copper] Looking ahead to tomorrow, available supply in the Shanghai region is expected to remain tight. Coupled with the persistent pre-holiday stockpiling demand from some downstream processing enterprises, this continues to provide strong support for spot premiums. Although some imported copper locked in at favorable SHFE/LME price ratios after the import window opened earlier is gradually arriving, the overall volume is limited. The supplementary effect on market supply is expected to be relatively modest in the short term, making it difficult to significantly ease the current supply tightness. As a result, spot premiums are expected to have further room to rise tomorrow. However, copper prices are already at elevated levels, and the backwardation spread between futures contracts has widened simultaneously. Combined with the rapid climb in spot premiums, procurement costs for downstream and end-user enterprises have increased markedly, and their acceptance of high premiums may gradually decline. If premiums continue to rise rapidly, some downstream buyers may turn to a wait-and-see stance, reducing just-in-time procurement, and market trading activity may pull back. Market participants are advised to monitor the risk of negative feedback on the demand side amid the combined effects of high copper prices, deep backwardation, and elevated premiums.
9 mins ago
Capstone Copper to sell Cozamin mine to Luca Mining for up to US$385 million
29 mins ago
Capstone Copper to sell Cozamin mine to Luca Mining for up to US$385 million
Read More
Capstone Copper to sell Cozamin mine to Luca Mining for up to US$385 million
Capstone Copper Corp. (TSX: CS; ASX: CSC) agreed on 21 September 2026 to sell its Cozamin copper-silver-zinc-lead underground mine in Zacatecas, Mexico, to Luca Mining Corp. (TSXV: LUCA) for total consideration of up to US$385 million. The package comprises US$275 million upfront cash, US$15 million in Luca shares, US$35 million deferred to the first anniversary, and up to US$60 million in contingent cash tied to annual average copper prices. Cozamin is forecast to average 20,000 tonnes of copper and 1.3 million ounces of silver annually between 2023 and 2030 at C1 costs of about US$1.51 per payable pound. Closing is targeted for the fourth quarter of 2026, requires no shareholder vote, and strengthens Capstone's balance sheet for growth projects in Chile and the United States.
29 mins ago
Imports Down, Exports Up: China's Net Copper Cathode Imports Fell in August 2026 [SMM Analysis] - Shanghai Metals Market (SMM)