SMM September 16 news: Today, the Shanghai lead 2610 contract continued to fluctuate weakly, with the intraday low dipping to 15,750 yuan/ton, hitting a near one-month low. In stark contrast to the weak Shanghai lead futures, the domestic lead spot market has quietly changed. Lead ingot supply has contracted, coupled with a seasonal recovery in demand, spot supply has tightened, and the price spread has turned from discount to premium. Currently, Shanghai lead is under pressure mainly due to overseas macro expectations of Fed rate hikes. Once the macro bearish news is fully digested, lead prices are expected to return to fundamental-driven trading and stage a rebound.
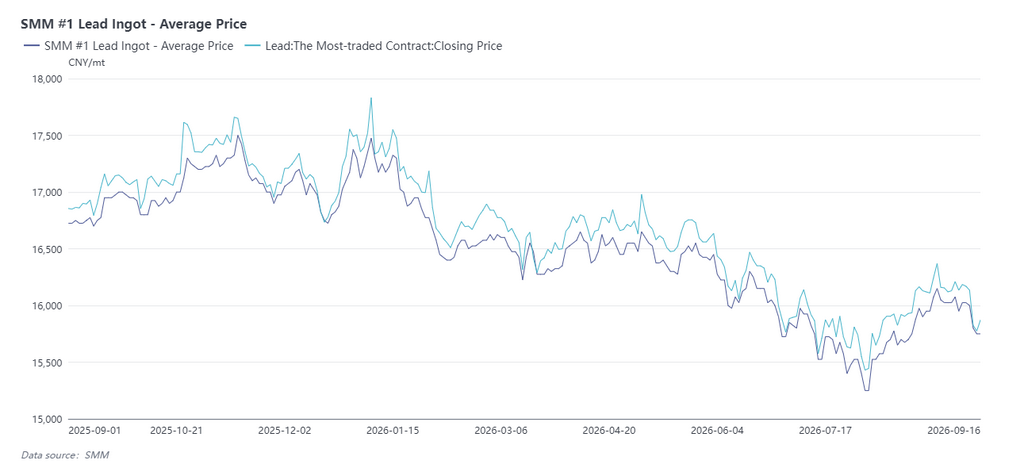
Futures Review: Macro Expectations Suppress Nonferrous Metals, Shanghai Lead Dips to 15,750 Yuan/Ton Low
After a sharp drop in lead prices on Monday, Shanghai lead has maintained weak fluctuations in recent days. Last night, the Shanghai lead 2610 contract dipped further to 15,750 yuan/ton, refreshing a more than one-month low, with macro factors becoming an important disturbance suppressing lead prices. The current market focus is on the Fed's September FOMC meeting. The meeting will be held on September 15-16 US Eastern Time, with the interest rate decision and related policy information to be released in the early morning of September 17 Beijing time. According to the CME "FedWatch" on September 16: the probability of the Fed keeping rates unchanged in September is 7.6%, and the cumulative probability of a 25-basis-point rate hike is 92.4%.
Supply side: Concentrated maintenance at primary lead smelters brings notable output cuts; secondary lead resumption falls short of expectations
In September, domestic primary lead smelters entered a concentrated maintenance cycle, with total supply reduction exceeding 20,000 tons. For secondary lead, smelter resumption progress fell short of expectations. In addition, continued lead price declines widened losses in secondary lead production, weakening smelters' willingness to sell, with a widespread reluctance to sell at low prices.
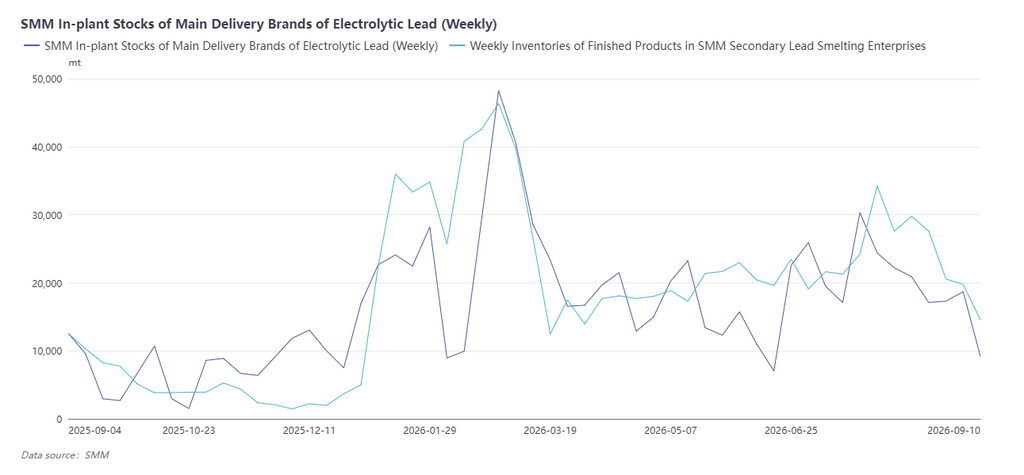
Inventory at both primary and secondary lead smelters declined, and market-available lead ingot supply gradually decreased. In mainstream production areas such as Henan, Hunan, and Yunnan, primary lead smelter inventories were drawn down rapidly. Some smelters have sold out their spot supply and started pre-sales. As of September 16, the farthest pre-sale orders at primary lead smelters were scheduled for October 25.
Demand side: Traditional peak season for lead-acid batteries materializes; downstream pre-holiday stockpiling begins
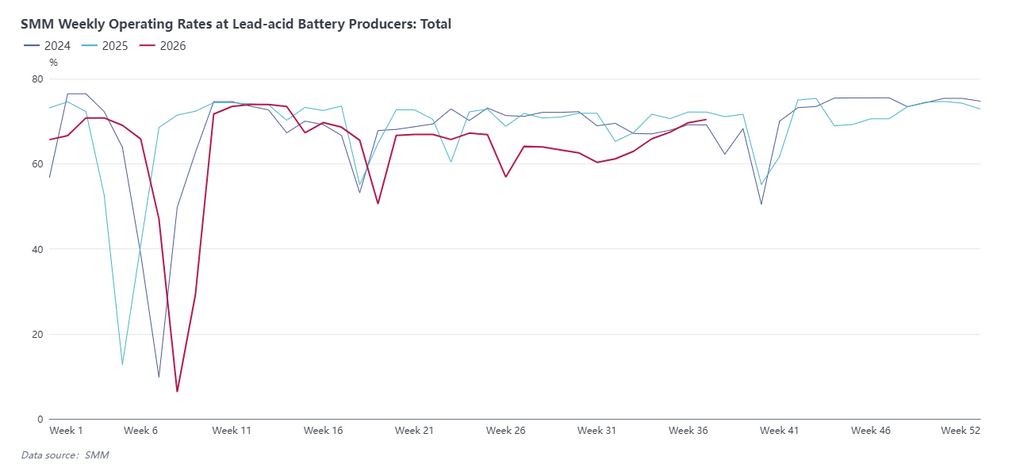
In Q3, the lead-acid battery market saw a seasonal improvement, with demand for electric bicycle and automotive batteries improving in tandem. Combined with aggressive promotions by battery companies in August, distributors took in large quantities of goods. To deliver earlier orders, battery companies generally ramped up production to varying degrees in September. Additionally, with the traditional stockpiling period for the Mid-Autumn Festival and National Day holidays, downstream lead ingot procurement demand was released. In particular, after lead prices fell below 16,000 yuan/ton this week, downstream enthusiasm for buying on dips rose significantly, with just-in-demand centralized restocking further consuming spot circulating inventory and tightening the spot market.
Spot Lead Price Spread Reversal: Discounts Narrow Rapidly, Multiple Regions Return to Premium Trading
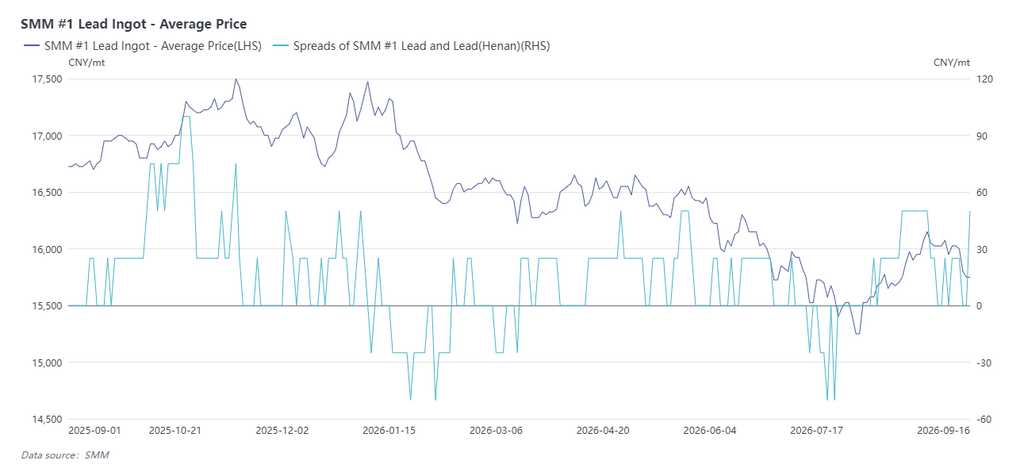
The shift in supply-demand dynamics is directly reflected in the futures-spot spread. Domestic lead spot discounts narrowed rapidly from earlier levels and turned into premium transactions. In Henan, primary lead ex-works quotes changed from a discount of 100-150 yuan/ton against the Shanghai lead 2610 contract last week to flat ex-works pricing today (September 16). In Hunan, primary lead transactions rose from flat pricing against the SMM 1# lead average price last week to a premium of 100-120 yuan/ton ex-works. The spot premium pattern confirms tight spot supply in the market, with trading activity among upstream and downstream enterprises increasing.
Outlook: After Macro Headwinds Fade, Lead Prices Will Return to Fundamentals
Currently, strong rate-hike expectations are suppressing risk appetite across the nonferrous metals sector. Shanghai lead followed the weak nonferrous sentiment and remained in low-level consolidation, showing a divergence pattern of "strong spot, weak futures." It is expected that once the Fed's interest rate decision is delivered and macro disturbance factors are fully priced in, the trading focus for lead prices will shift back to domestic supply-demand fundamentals. Supported by supply reductions, downstream stockpiling, and tight spot supply, lead prices are highly likely to stop falling and rebound.
Data Source Disclaimer: Except for publicly available information, all other data are derived from public information, market communications, and SMM's internal database models, processed by SMM, and are provided for reference only, not constituting decision-making advice.