SMM Sep 14 News:
According to SMM data, sulfuric acid prices for smelters have shifted from high levels into a downward trend since the third quarter, with prices in major domestic regions currently falling to RMB 1,100–1,800/mt. At the same time, zinc concentrate treatment charges (TCs) continued to decline rapidly in Q3. As of September 11, the average domestic zinc concentrate TC had fallen to -RMB 2,100/metal mt, while the import zinc concentrate index had declined to -$112.91/dmt. With both sulfuric acid prices and zinc concentrate TCs declining, zinc smelter margins are being squeezed from both sides. Why is this happening, and what can be expected in Q4?
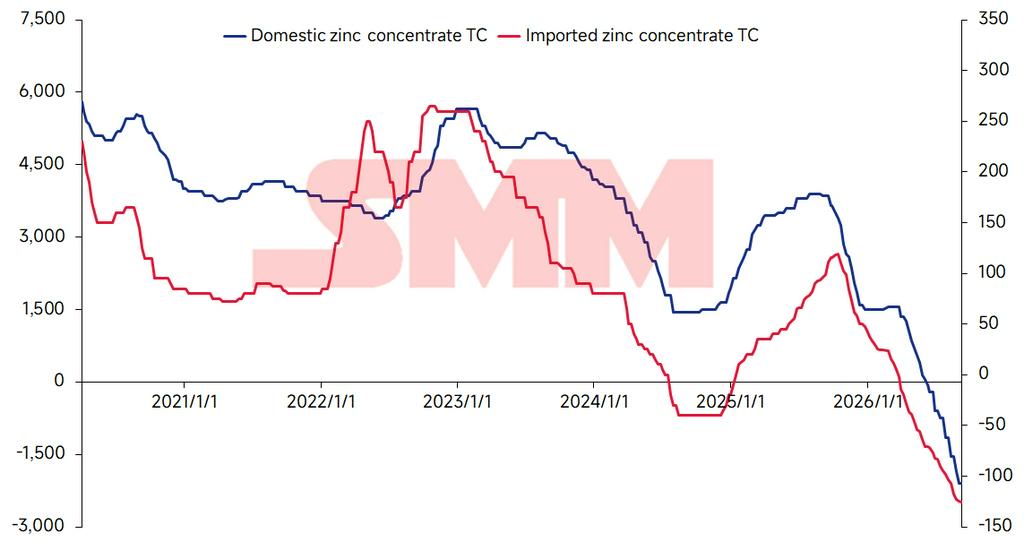
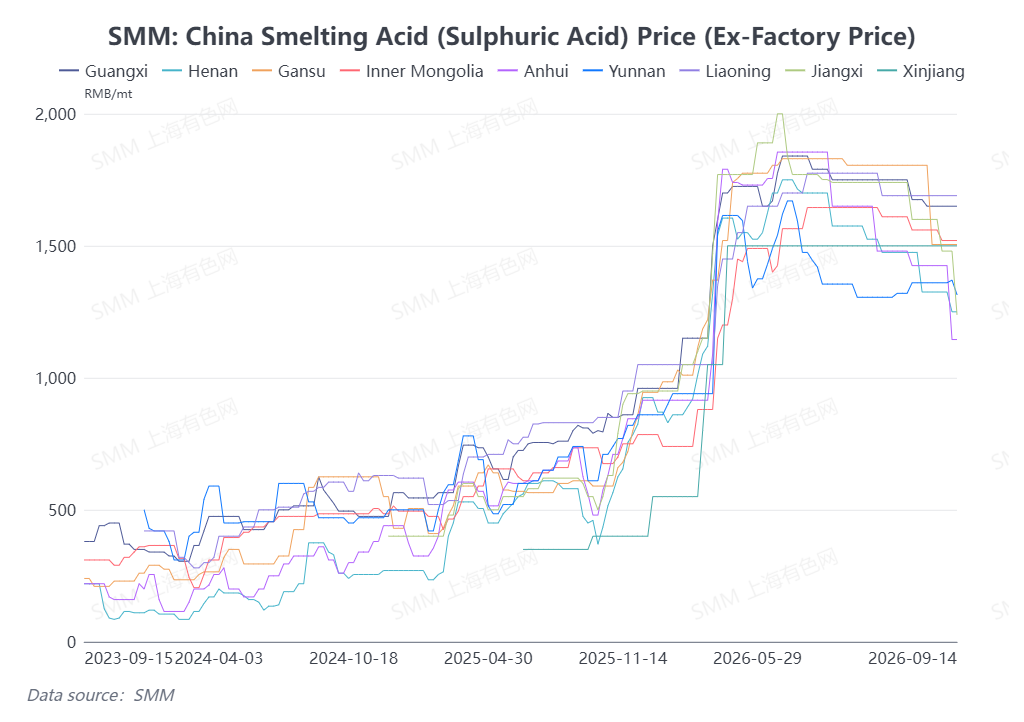
SMM believes that against the backdrop of falling sulfuric acid prices, the rapid decline in Chinese zinc concentrate TCs in Q3 was mainly driven by increasingly significant supply disruptions.
Domestic Zinc Concentrate Market
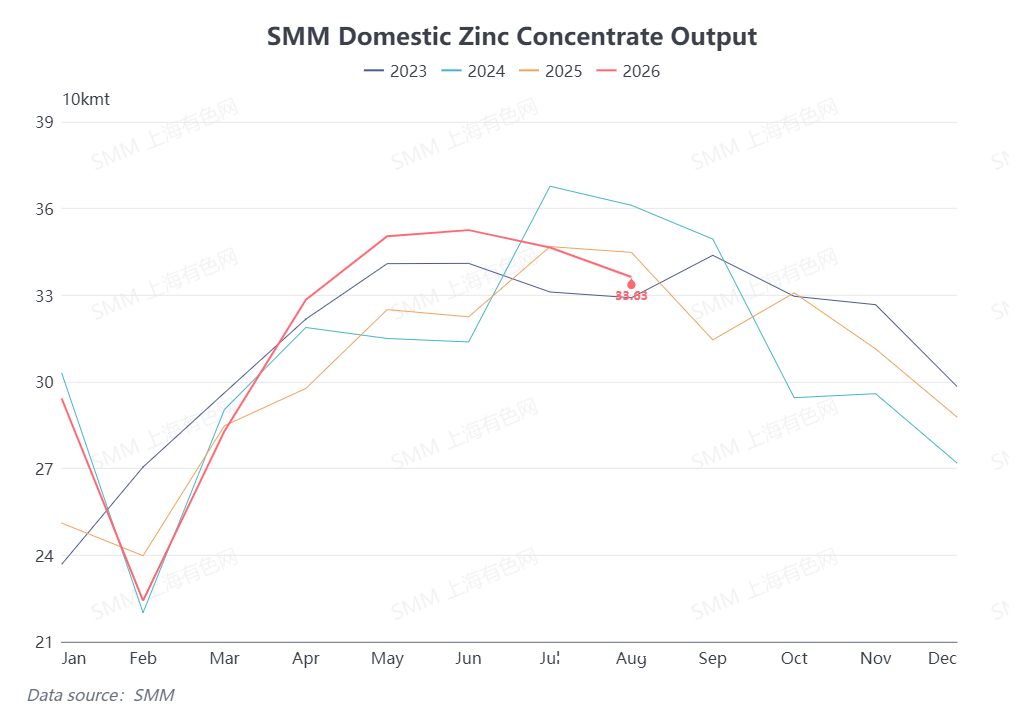
Based on the production patterns of previous years, Q3 is typically the peak production season for domestic zinc concentrate, with output generally reaching its annual high. However, this pattern has not been observed this year.
On the one hand, since the beginning of Q3, unexpected incidents have led to temporary production suspensions at some lead-zinc mines in Inner Mongolia, Guangdong and other provinces, resulting in some supply losses. Meanwhile, these incidents have triggered tighter nationwide safety inspections, affecting lead-zinc mines in multiple provinces, with some temporarily reducing or suspending production.
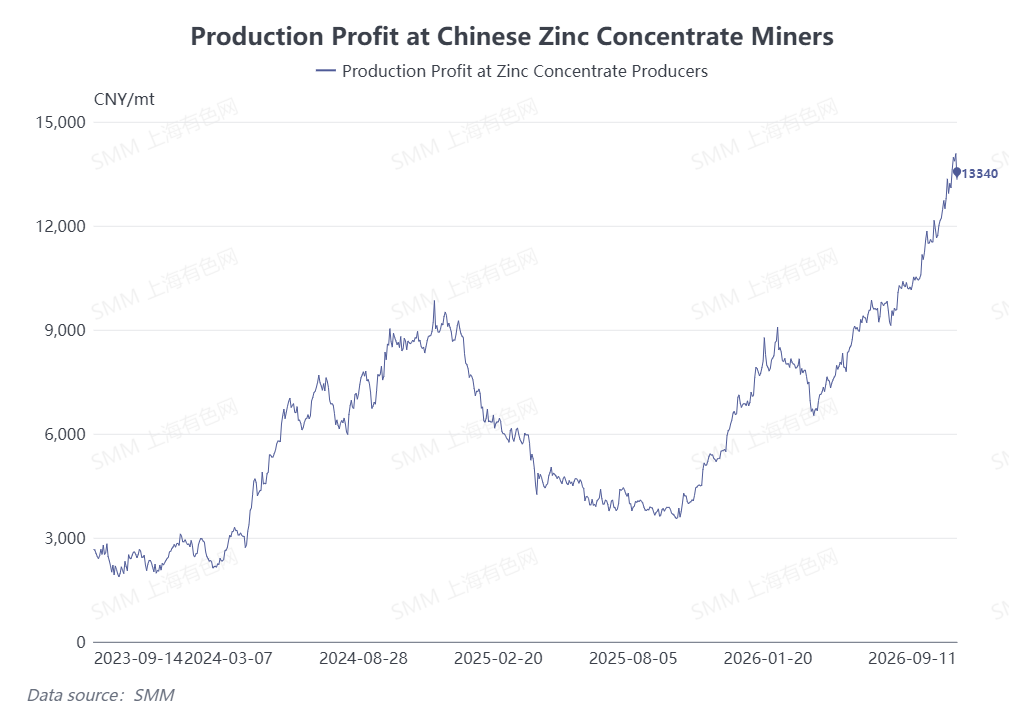
On the other hand, as zinc concentrate TCs have continued to decline, mine profitability has improved significantly. Some mines have already achieved their annual profit targets ahead of schedule, weakening their production incentives. Some have therefore planned production cuts and maintenance in H2, further contributing to supply losses.
Taken together, these disruptions led to a significant quarter-on-quarter decline in domestic zinc concentrate production in Q3.
Imported Zinc Concentrate Market
SMM tracked the production performance of 17 major overseas mining companies. Based on their reported production data, total zinc mine output from the 17 companies amounted to 2.4578 million metal mt in H1 2026, down 8.9% YoY, indicating a significant decline in overseas zinc concentrate production during the first half of the year.
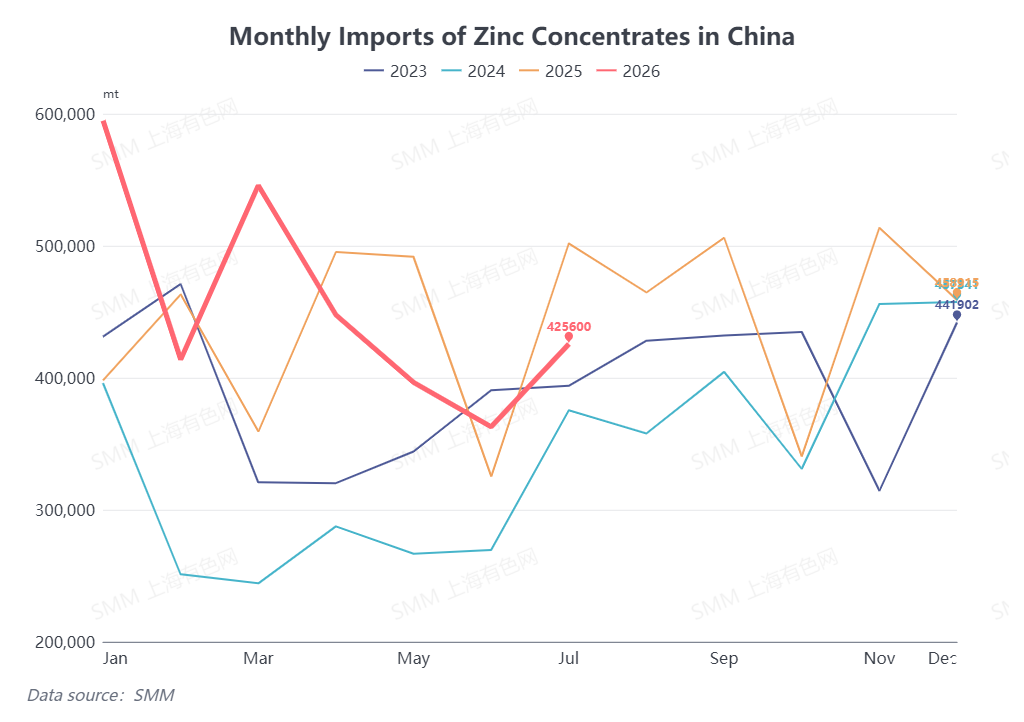
The decline in overseas mine output has affected the inflow of imported zinc concentrate into China. According to import data, China's zinc concentrate imports fell significantly in Q2 compared with Q1, while overall import volumes are also expected to see limited growth in Q3.
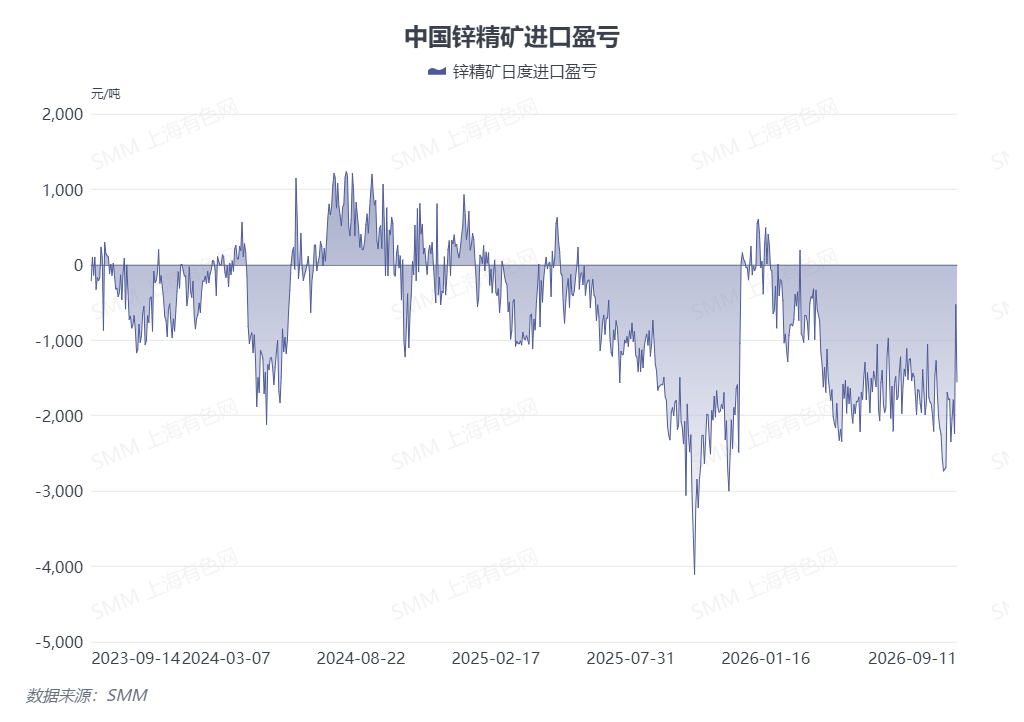
From a pricing perspective, the zinc import arbitrage ratio has continued to weaken since the beginning of the year. Since April, losses on zinc concentrate imports into China have widened to around RMB 2,000/metal mt and remained at this level through Q3. As domestic ore has become more economically competitive, smelters have actively increased their purchases of domestic zinc concentrate in Q2 and Q3.
Against the backdrop of reduced concentrate supply, although Q3 is also the traditional maintenance season for domestic zinc smelters and refined zinc production consequently declined, the overall tightness in the concentrate market showed no significant improvement amid simultaneous declines in both supply and demand. This drove zinc concentrate TCs lower consecutively throughout the quarter.
Outlook for Q4
According to SMM, although mines that previously suspended or reduced production are expected to gradually resume operations in Q4, the fourth quarter is also a traditional maintenance season for domestic mines. Overall domestic zinc concentrate supply is therefore expected to show no significant quarter-on-quarter improvement.
Although declining profitability is weakening production incentives among domestic zinc smelters, demand for winter inventory replenishment remains. As a result, the overall supply-demand balance in the zinc concentrate market is unlikely to improve significantly, and zinc concentrate TCs are expected to remain at low levels in Q4.
(The above information is based on market collection and comprehensive evaluation by the SMM research team. The information provided in this article is for reference only. This article does not constitute direct advice for investment research and decision-making. Customers should make cautious decisions and should not replace their independent judgment with this information. Any decisions made by customers are not related to SMM.)