According to SMM statistics, China's energy storage battery cell production in H1 2024 was 114.7 GWh, up 27% YoY from 90.2 GWh in H1 2023. In terms of shipments, H1 2024 energy storage battery cell shipments were approximately 111 GWh.
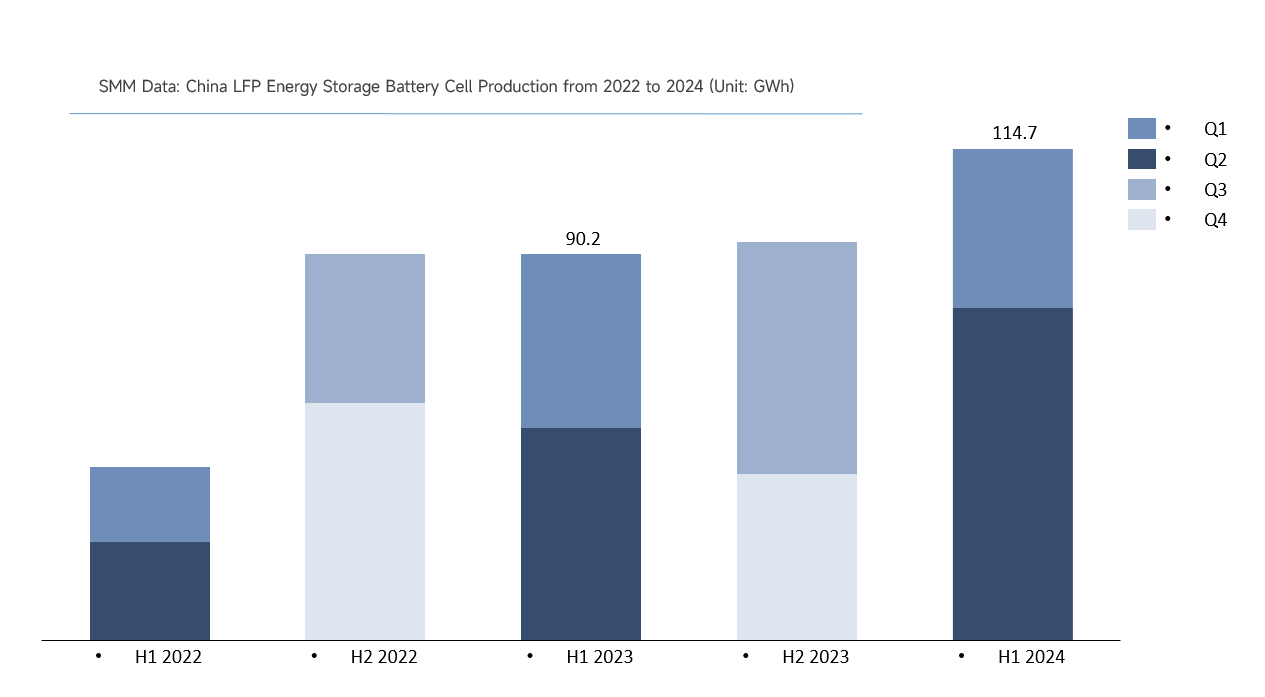
Breaking down H1 production:
In Q1 2024, domestically, due to high inventory levels of energy storage battery cells at the end of 2023 and the project planning phase following the concentrated grid connection at the end of 2023, orders for energy storage battery cells saw a slight decline. Overseas, Q1 was winter, with low temperatures and low operating rates for installation workers. Overall, the European market was still digesting inventory, the U.S. market's installation progress was delayed, and other emerging markets contributed limited demand, leading to overall weak overseas energy storage demand. These factors affected the production end of energy storage battery cells, resulting in reduced actual orders and a need for destocking. Consequently, Q1 energy storage battery cell production was only 37.16 GWh, down 4% MoM and 8% YoY.
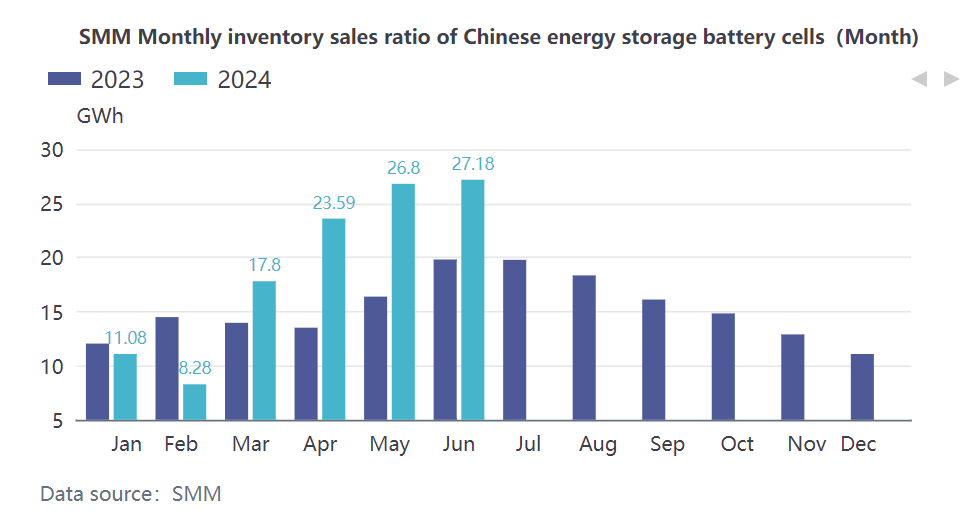
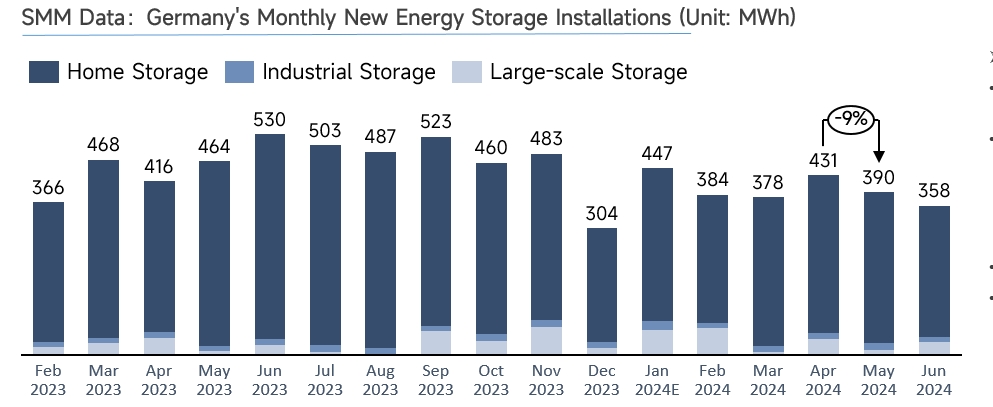
In Q2 2024, the domestic energy storage market performed strongly. Reflecting on 2023, the energy storage market's tender volume exceeded expectations, indicating that the mid-2024 grid connection process would drive significant demand for energy storage battery cells, leading to a rapid increase in domestic energy storage orders in Q2. Additionally, the decline in energy storage battery cell prices and the implementation of subsidies for industrial, commercial, and independent energy storage across various regions also contributed to the steady increase in orders in H1 2024. In the overseas market, according to SMM observations, the U.S. saw a significant increase in new installations from late Q1 to early Q2, mainly benefiting from optimized grid connection processes, allowing some previously delayed projects to connect to the grid. SMM statistics show that the cumulative grid-connected capacity in the first five months of 2024 reached 2.83 GW, up 269.7% YoY. In Europe, household energy storage demand rebounded in Q2 after a destocking phase, although some regions still faced challenges from gradually canceled subsidies and low electricity prices, keeping household energy storage demand relatively stable without significant policy support. Overall, the surge in energy storage demand in Q2 led to a record high in energy storage battery cell production.
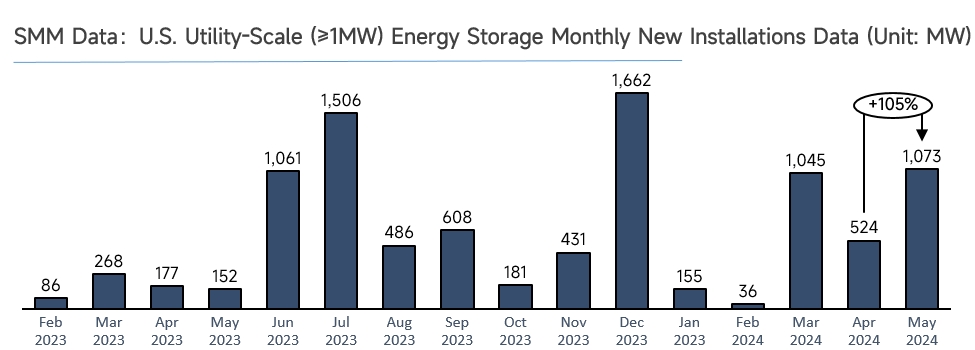

In H2 2024, domestic tender volume is expected to remain high. According to SMM statistics, in H1 2024, China's cumulative awarded energy storage project capacity reached 59.56 GWh, up 93% YoY. The industrial, commercial, and independent energy storage markets will benefit from the decline in energy storage battery cell prices and the implementation of subsidy policies, significantly improving economic viability. In the overseas market, the U.S. grid connection delays are expected to ease, and with the impact of the upcoming election, the U.S. energy storage installation volume in H2 may exceed expectations. Overall, driven by demand, China's energy storage battery cell production is expected to continue growing.
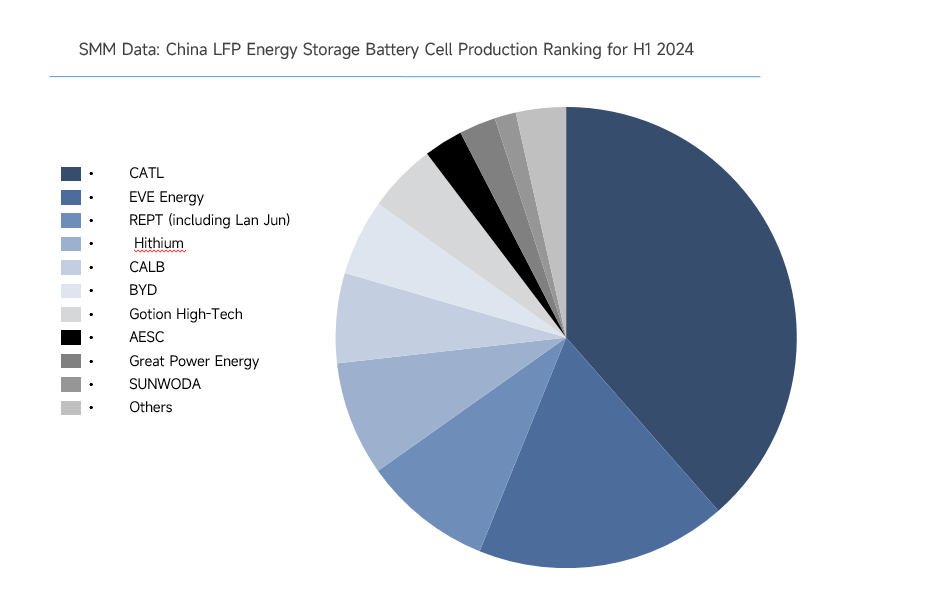
According to SMM tracking data, in H1 2024, CATL remained the leader in China's energy storage battery cell production, with nearly 40 GWh. EVE Energy and Xiamen Hithium ranked second and third, respectively, while BYD's ranking fell to sixth. Analyzing the ranking changes, CATL continued to lead the market with its stable customer structure, early brand layout, and diverse product matrix. EVE Energy, relying on its product advantages, saw rapid growth in H1, surpassing BYD to take the second spot. Other second- and third-tier companies also gradually improved in the volatile energy storage market. Despite being a new entrant, Sunwoda achieved significant results in H1 due to its battery cell technology reserves and increased investment. BYD's performance in the energy storage sector was relatively weaker, but its frequent announcements of overseas expansion plans may bring impressive results in H2.
Looking ahead, SMM believes that current energy storage battery cell prices are nearing the bottom, and industry consolidation is accelerating. The iteration process of large battery cells is also speeding up, with the widespread adoption of 314Ah cells becoming inevitable. Battery cell companies with mass production capabilities and stable customer relationships are expected to increase their market share and profits by raising the shipment proportion of 314Ah cells. Additionally, SMM believes that the future success of energy storage companies will depend on their ability to establish extensive sales channels, build brand image, and improve product quality. SMM believes that with the advancement of the global green energy transition, the future of energy storage will become clearer. Although the current path is still shrouded in uncertainty, the industry will eventually overcome obstacles and reach a bright future, with a thriving energy storage market and a grand vision for green energy.