SHANGHAI, Oct 14 (SMM) - This is a roundup of China's metals weekly inventory as of October 14.
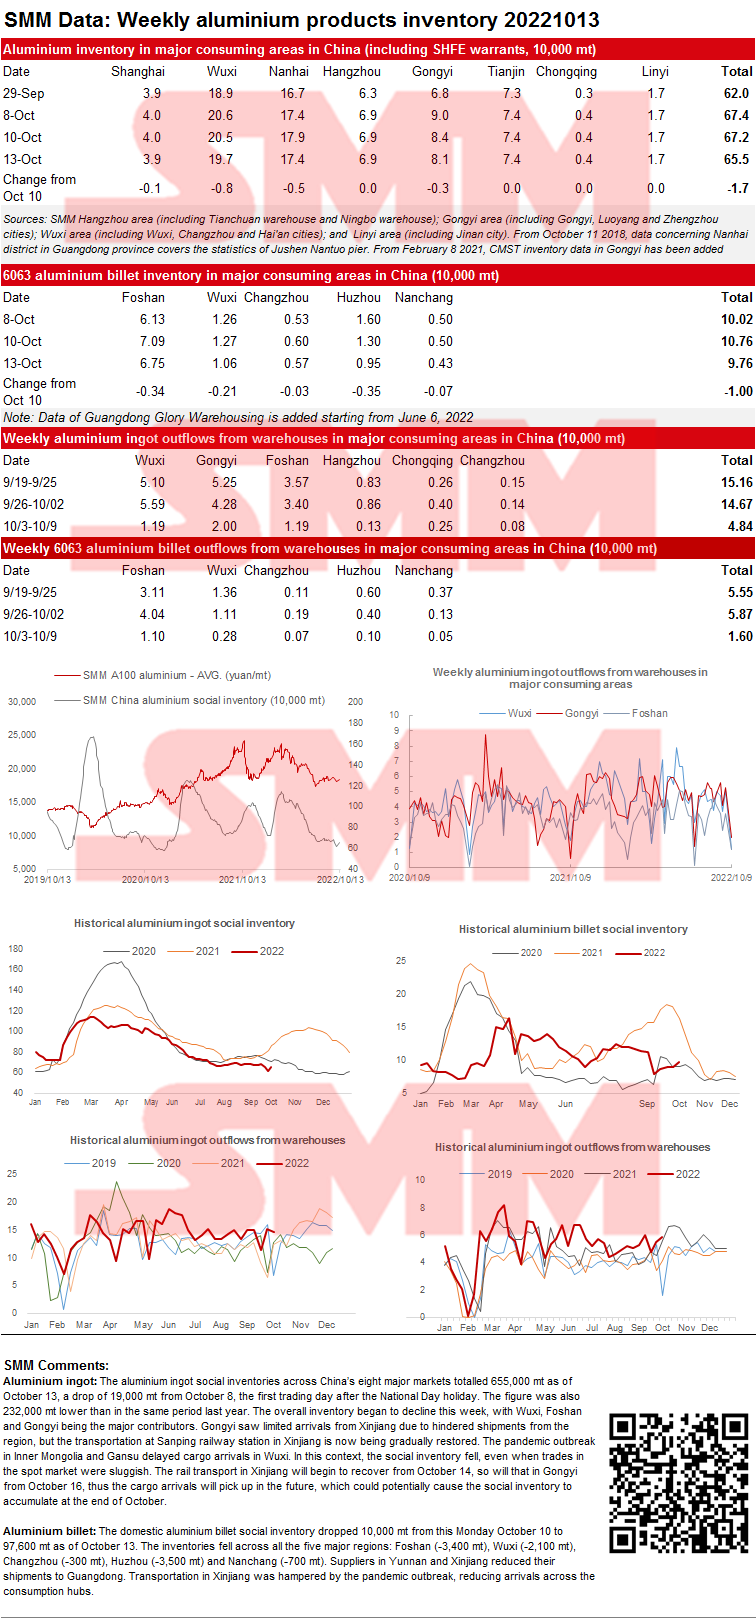
SMM’s Latest Update on China Social Inventory of Aluminium Ingots and Billets as of October 13
Aluminium ingot: The aluminium ingot social inventories across China’s eight major markets totalled 655,000 mt as of October 13, a drop of 19,000 mt from October 8, the first trading day after the National Day holiday. The figure was also 232,000 mt lower than in the same period last year. The overall inventory began to decline this week, with Wuxi, Foshan and Gongyi being the major contributors. Gongyi saw limited arrivals from Xinjiang due to hindered shipments from the region, but the transportation at Sanping railway station in Xinjiang is now being gradually restored. The pandemic outbreak in Inner Mongolia and Gansu delayed cargo arrivals in Wuxi. In this context, the social inventory fell, even when trades in the spot market were sluggish. The rail transport in Xinjiang will begin to recover from October 14, so will that in Gongyi from October 16, thus the cargo arrivals will pick up in the future, which could potentially cause the social inventory to accumulate at the end of October.
Aluminium billet: The domestic aluminium billet social inventory dropped 10,000 mt from this Monday October 10 to 97,600 mt as of October 13. The inventories fell across all the five major regions: Foshan (-3,400 mt), Wuxi (-2,100 mt), Changzhou (-300 mt), Huzhou (-3,500 mt) and Nanchang (-700 mt). Suppliers in Yunnan and Xinjiang reduced their shipments to Guangdong. Transportation in Xinjiang was hampered by the pandemic outbreak, reducing arrivals across the consumption hubs.
SMM Zinc Ingot Social Inventories Added 4,000 mt from Monday
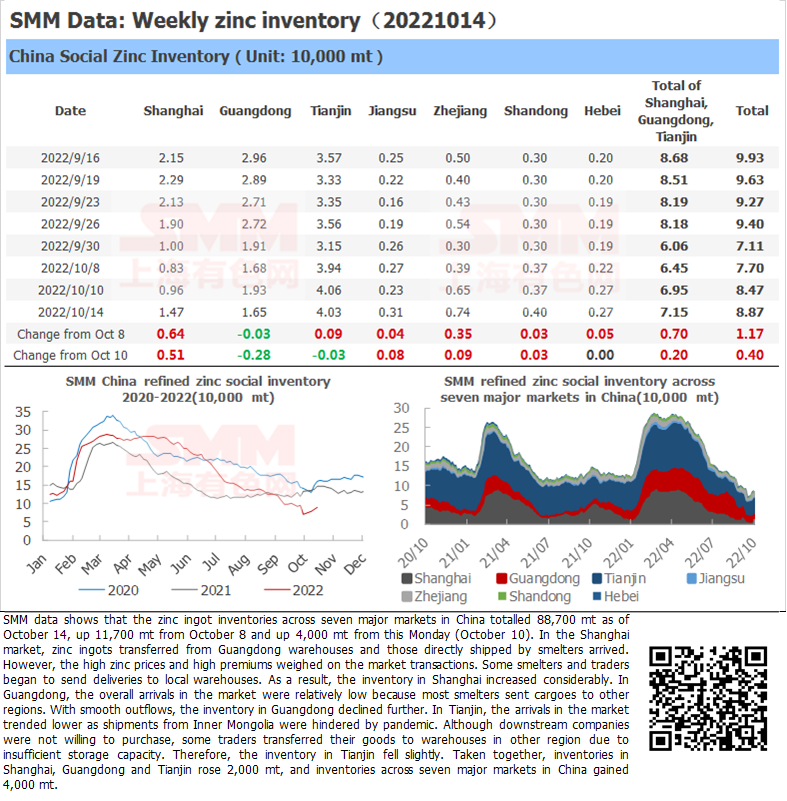
SMM data shows that the zinc ingot inventories across seven major markets in China totalled 88,700 mt as of October 14, up 11,700 mt from October 8 and up 4,000 mt from this Monday (October 10). In the Shanghai market, zinc ingots transferred from Guangdong warehouses and those directly shipped by smelters arrived. However, the high zinc prices and high premiums weighed on the market transactions. Some smelters and traders began to send deliveries to local warehouses. As a result, the inventory in Shanghai increased considerably. In Guangdong, the overall arrivals in the market were relatively low because most smelters sent cargoes to other regions. With smooth outflows, the inventory in Guangdong declined further. In Tianjin, the arrivals in the market trended lower as shipments from Inner Mongolia were hindered by pandemic. Although downstream companies were not willing to purchase, some traders transferred their goods to warehouses in other region due to insufficient storage capacity. Therefore, the inventory in Tianjin fell slightly. Taken together, inventories in Shanghai, Guangdong and Tianjin rose 2,000 mt, and inventories across seven major markets in China gained 4,000 mt.
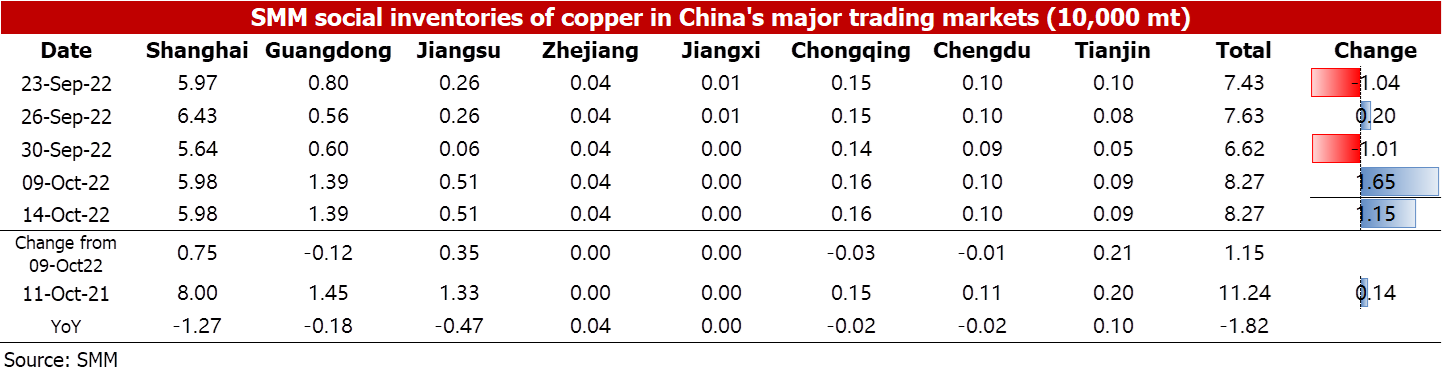
SMM Copper Inventory across Major Chinese Markets Added 11,500 mt from October 9
As of Friday October 14, SMM copper inventory across major Chinese markets stood at 94,200 mt, up 11,500 mt from October 9, but down 11,000 mt from the same period last year when the inventory dipped 5,800 mt to 105,200 mt. In detail, the inventory in Shanghai added 7,500 mt to 67,300 mt, the inventory in Guangdong dipped 1,200 mt to 12,700 mt, the inventory in Jiangsu and Tianjin rose by 3,500 mt and 2,100 mt respectively, and the inventory in Chongqing and Chengdu dropped slightly.
The overall inventory was on the rise, but the change in inventory in south China and east China was completely different. In south China, the inventory fell slightly due to the limited increase in imported copper after the National Day holiday. Most downstream companies held a wait-and-see sentiment amid the spread between the front-month and next-month SHFE contracts of 1,400-1,800 yuan/mt in the backwardation structure after the holiday, suppressing the consumption, thus the spot prices in China were quoted at discounts.
Looking forward, domestic copper inventories this week are expected to drop slightly because, after the delivery of the SHFE 2210 copper contract, downstream companies will make some restocking. However, the destocking will be limited by the continuous inflow of imported copper amid the opening import window and the higher proportion of LME cancelled warrants.
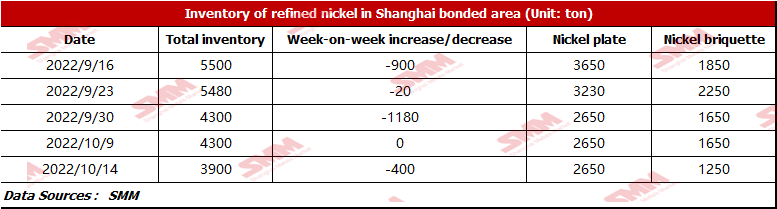
Nickel Inventories in Domestic Bonded Zones Dropped 400 mt from October 9
SMM research showed that the bonded zone inventory of nickel dipped 400 mt to 3,900 mt this week. The inventory of nickel briquette was 1,250 mt, and that of nickel plate was 2,650 mt. Although the RMB exchange rate has depreciated, the imports of spot pure nickel still gained some profits. The rigid demand for nickel briquettes still existed this week because of the expected increase in nickel sulphate output and the bullish stainless steel market in October.
Copper Inventories in Domestic Bonded Zones Dipped 13,600 mt from October 9
Copper inventories in domestic bonded zones fell 13,600 mt from October 9 to 38,100 mt as of October 14, according to the SMM survey. Inventory in the Shanghai bonded zone dipped 11,600 mt to 30,100 mt, and that in the Guangdong bonded zone dropped 2,000 mt to 8,000 mt. The bonded zone warehouses resumed the normal operations this week and the import profits stood at nearly 1,000 yuan/mt, boosting the demand for customs declaration, hence the bonded zone inventory dropped.

Social Inventory of Lead Ingots Increased as Cargo Holders were More Willing to Ship
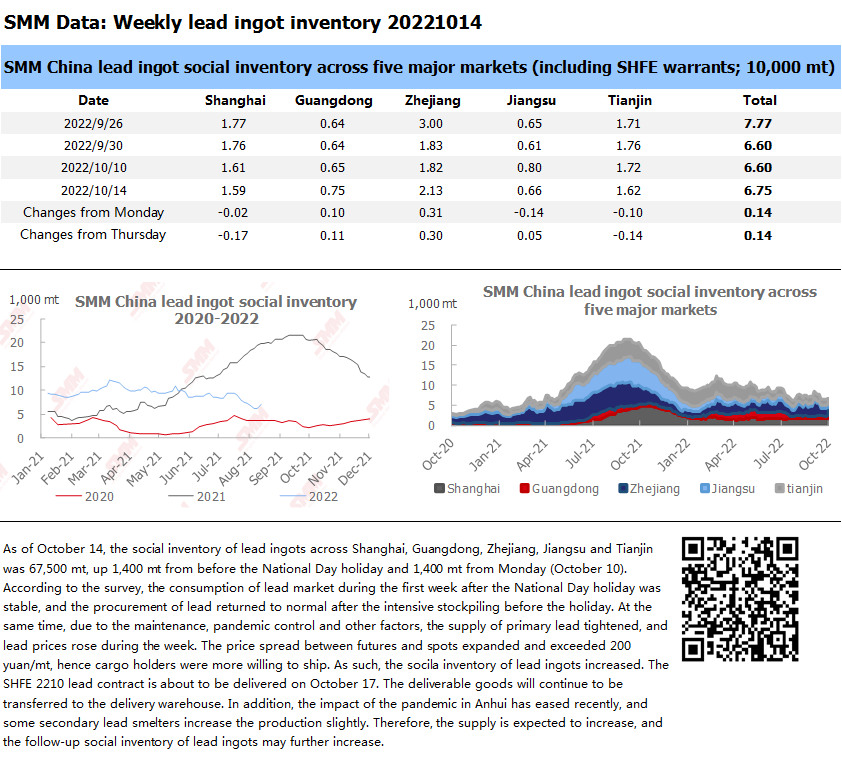
As of October 14, the social inventory of lead ingots across Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin was 67,500 mt, up 1,400 mt from before the National Day holiday and 1,400 mt from Monday (October 10).
According to the survey, the consumption of lead market during the first week after the National Day holiday was stable, and the procurement of lead returned to normal after the intensive stockpiling before the holiday. At the same time, due to the maintenance, pandemic control and other factors, the supply of primary lead tightened, and lead prices rose during the week. The price spread between futures and spots expanded and exceeded 200 yuan/mt, hence cargo holders were more willing to ship. As such, the socila inventory of lead ingots increased. The SHFE 2210 lead contract is about to be delivered on October 17. The deliverable goods will continue to be transferred to the delivery warehouse. In addition, the impact of the pandemic in Anhui has eased recently, and some secondary lead smelters increase the production slightly. Therefore, the supply is expected to increase, and the follow-up social inventory of lead ingots may further increase.
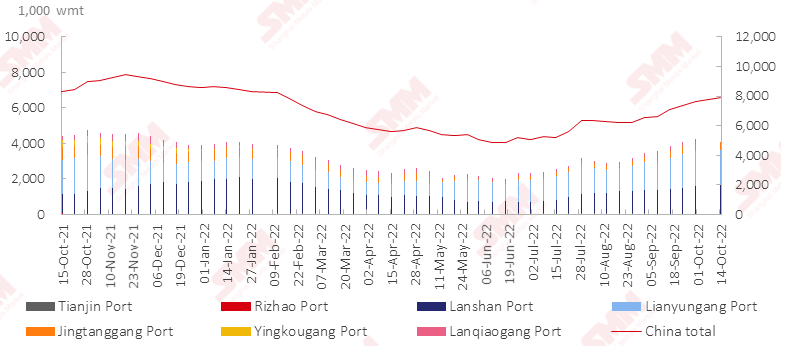
Port Inventories of Nickel Ore Added 321,000 wmt Compared with those before the National Day Holiday
As of October 14, port inventories of nickel ore in China added 321,000 wmt to 7.94 million wmt compared with those before the National Day holiday. The total Ni content stood at 62,000 mt. Inventory across seven major Chinese ports stood at 4.35 million wmt, 141,000 wmt higher than the pre-holiday level. In the first half of October, the prices of nickel ore fluctuated upwards. As the NPI market gradually warmed up, the downstream became more willing to purchase nickel ore. Besides, due to the rainy season in the Philippines, NPI plants’ demand for nickel ore increased sharply, and the delivered goods gradually arrived at ports. The nickel ore inventory will gradually rise next week, which may reach more than 8 million wmt, and the inventory will begin to fall after the Philippines has fully entered the rainy season.

Social Inventories of Silicon Metal Fell Slightly and the Overall Shipment Flow at Ports was Less Active
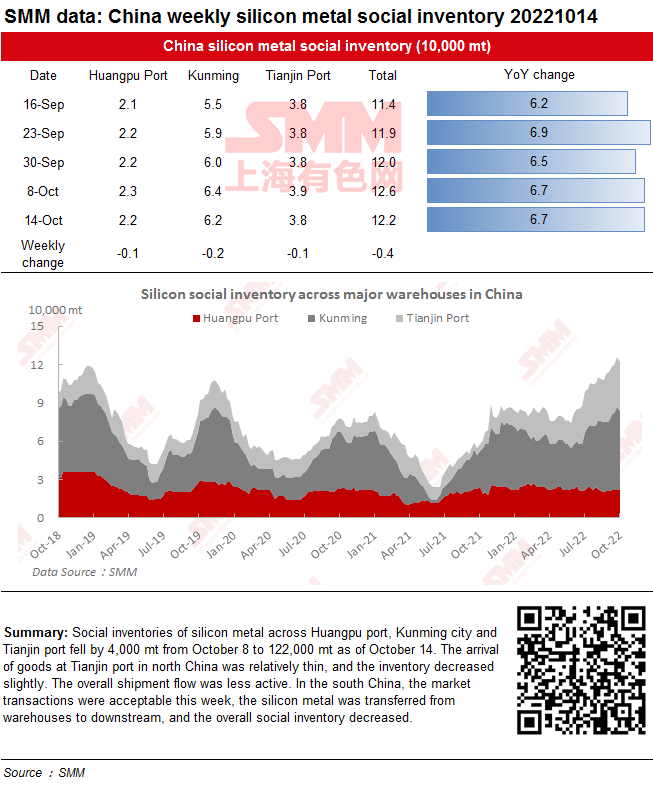
Social inventories of silicon metal across Huangpu port, Kunming city and Tianjin port fell by 4,000 mt from October 8 to 122,000 mt as of October 14. The arrival of goods at Tianjin port in north China was relatively thin, and the inventory decreased slightly. The overall shipment flow was less active. In the south China, the market transactions were acceptable this week, the silicon metal was transferred from warehouses to downstream, and the overall social inventory decreased.