China Weekly Inventory Summary and Data Wrap (Dec 24)

Đã xuất bản: Dec 24, 2021 20:00
This is a roundup of China's metals weekly inventory as of December 24.

SHANGHAI, Dec 24 (SMM) - This is a roundup of China's metals weekly inventory as of December 24.

Aluminium Social Inventories Dropped 46,000 mt on Week

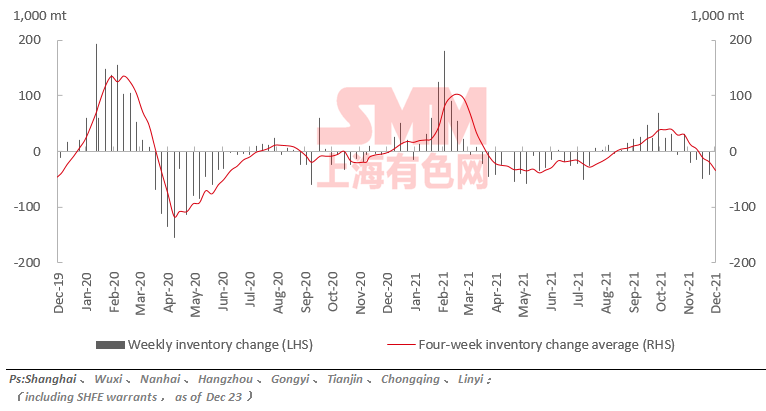
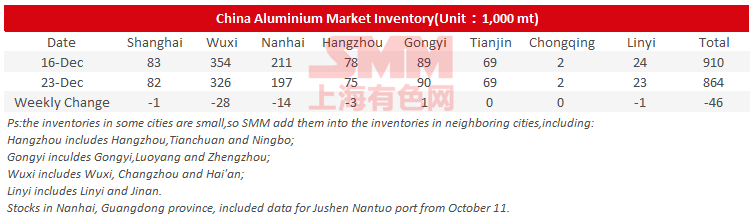
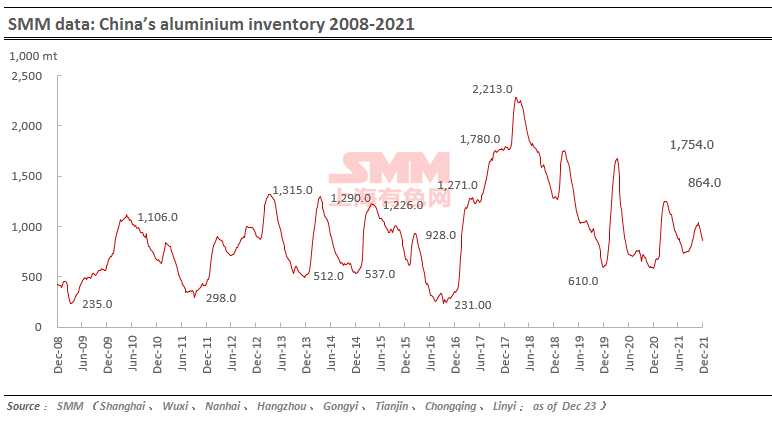
SMM data showed that China's social inventories of aluminium across eight consumption areas dropped 46,000 mt on the week to 864,000 mt as of December 23, mainly contributed by Wuxi and Nanhai. The inventory in Gongyi rose slightly on the week.

The social inventories dropped 27,000 mt from Monday December 20 mainly owing to the declining arrivals in Wuxi.
Aluminium Billet Inventories Down 900 mt on Week

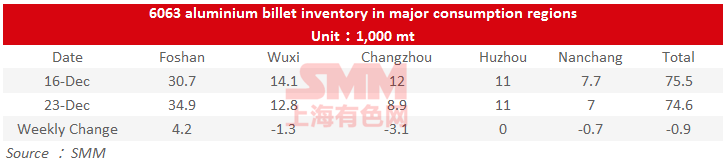
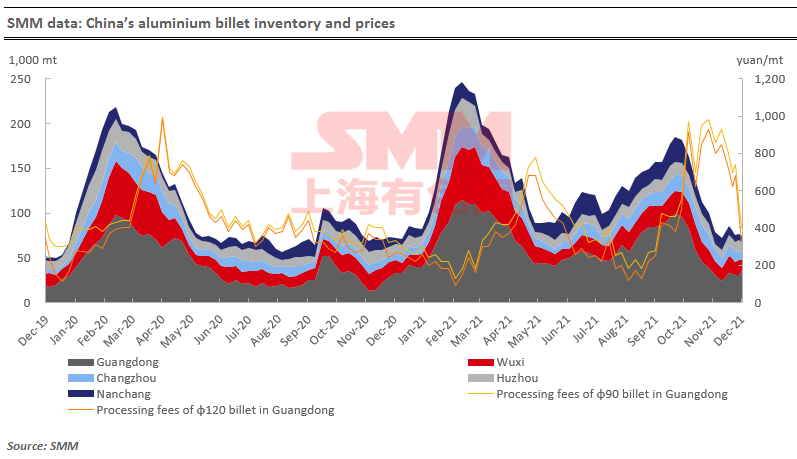
The stocks of aluminium billet in five major consumption areas dropped 900 mt to 74,600 mt on December 23 from a week ago, a decrease of 1.19%.

Only the inventory in Foshan rose on the week by 4,200 mt or 13.68%, and the inventories in Wuxi, Changzhou and Nanchang all declined, with Changzhou (down 3,100 mt or 25.83%) contributing most of the decreases. According to the warehouses, the weekly arrivals of aluminium billet were still at a low level as the manufacturers were less interest in making shipments amid falling RCs. Some aluminium billet manufacturers even planned to reduce their production.

Looking into next week, the downstream market was muted in demand by the year-end. Hence there is a higher possibility that the weekly social inventory of aluminium billet will rise.
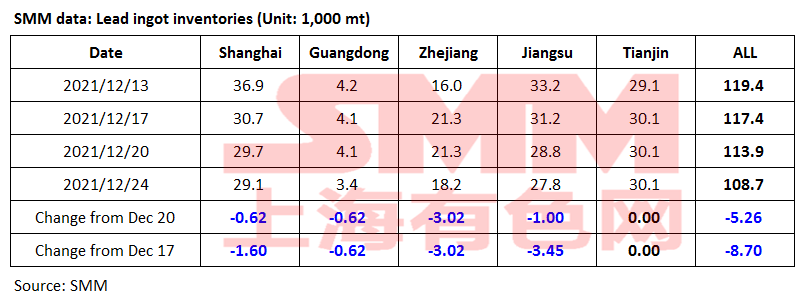
Lead Ingot Social Inventory Dropped 5,300 mt on Week

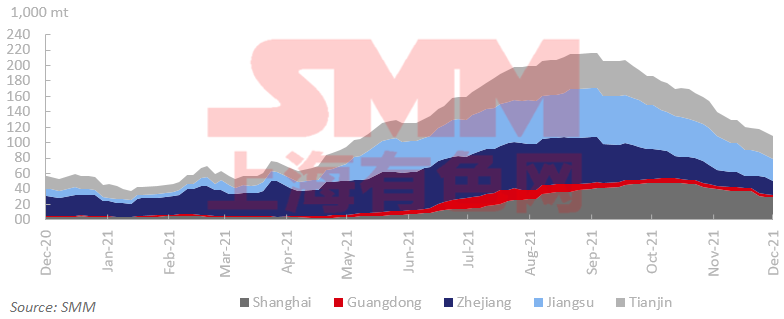
The social inventory of lead ingots across Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin decreased 8,700 mt from December 17 and 5,300 mt from December 20 to 108,700 mt as of December 24.

The enterprises from the lead industry chain are collecting funds more actively in late December. The smelters and traders increased shipments. The traders mostly shipped goods at discounts to reduce the product inventories. The quotations of lead ingots in Jiangsu, Zhejiang, and Shanghai stood at discounts of 70-0 yuan/mt over SHFE 2201 lead contract. The discounts of goods from smelters expanded to 200-250 yuan/mt. The smelters quoted for small orders at discounts of 150-0 yuan/mt over the average price of SMM 1# lead, and the downstream users purchased on demand. Some downstream enterprises advanced their purchases for restocking as they would close for settlement this week.

The primary lead smelters will further resume the production after maintenance next week, and the lead ingot social inventory may drop more significantly as the enterprises may close the trade.
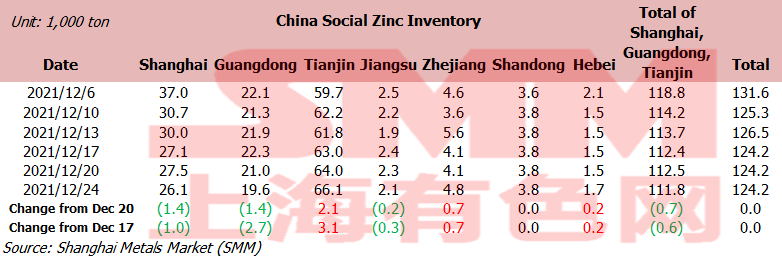
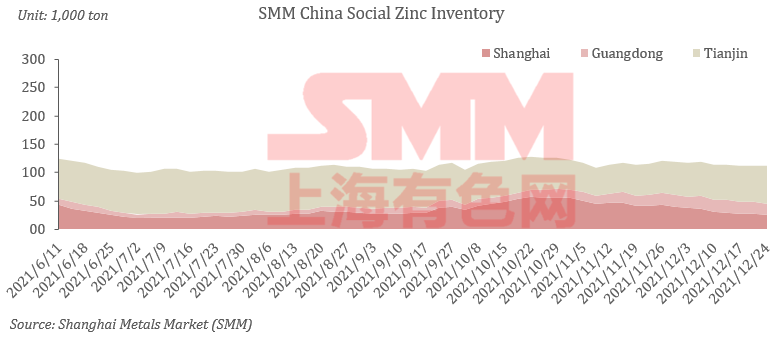
Zinc Social Inventories Flat on Week

Total zinc inventories across seven Chinese markets stood at 124,200 mt as of December 24, flat from December 20 and December 17.

The inventory in Shanghai declined as the imported zinc available in the market thinned and some leading producers reduced the production. Stocks in Guangdong continued to decline as the arrivals of goods declined after the price spread between Shanghai and Guangdong widening. The inventory in Tianjin continued to accumulate amid stable arrivals of goods at smelters and falling demand from downstream producers. Inventories in Shanghai, Guangdong and Tianjin fell 600 mt, and inventories across seven Chinese markets were flat.
Imports of Spot Nickel Saw Slight Profits

The SHFE/LME nickel price ratio stood at 7.44 this week, and the import profits stood at 250 yuan/mt. Traders continued to move cargoes into the domestic market from bonded zone inventories. But the inventory growth in Shanghai was not significant as some of the cargoes had been presold and delivered to the downstream buyers.

The domestic pure nickel inventory will remain at a low level next week. And the low inventory will not improve fundamentally until large volumes of imported cargoes arrive. The shipments arrivals are expected to stand at 1,500-2,000 mt next week, which is not large. The SHFE/LME nickel price ratio is expected to remain high.
Nickel Ore Inventories at Chinese Ports Fell 118,000 wmt

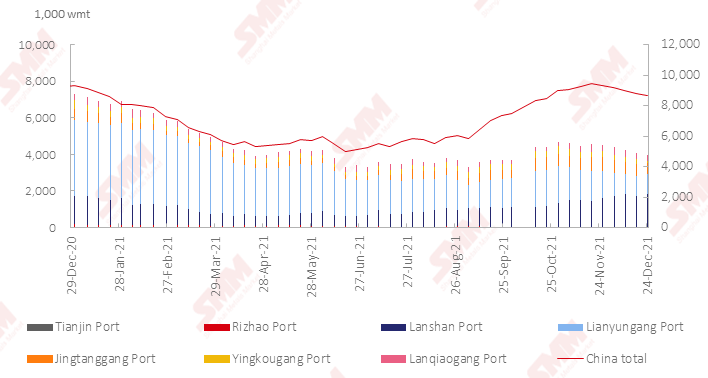
The nickel ore inventory at Chinese ports dipped 118,000 wmt from a week earlier to 8.66 million wmt as of December 24. Total Ni content stood at 68,000 mt. The total inventory at seven major ports stood at around 3.96 million wmt, a drop of 108,000 wmt from a week earlier.

The nickel ore inventories have fallen for five consecutive weeks since the end of November as the imports have decreased significantly. However, the downstream demand is also relatively weak due to the current high costs and the impact of environmental protection and production restrictions in some areas. Hence the inventory decline was not noticeable.

It is expected that the production situation of downstream plants will remain unchanged before the Chinese New Year, and the decline of nickel ore port inventory will continue.
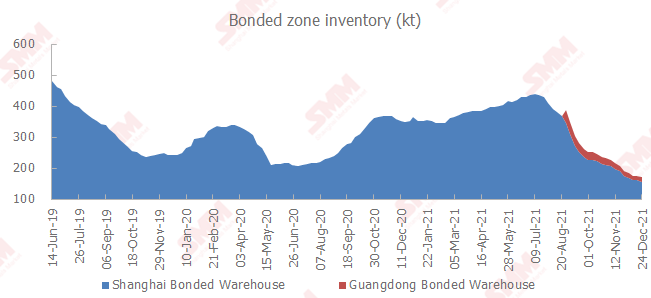
Copper Inventory in Domestic Bonded Zone Declined 2,200 mt on Week

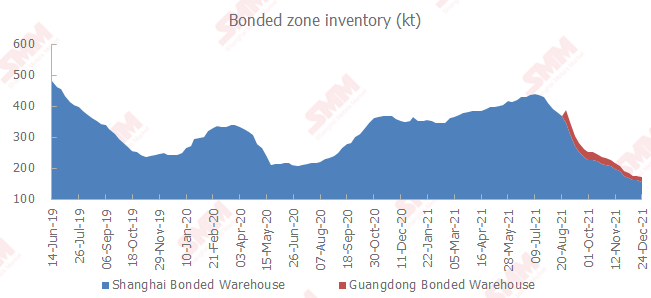
The copper inventories in the domestic bonded zones decreased 2,200 mt from December 17 to 171,700 mt as of December 24, falling for 11 consecutive weeks, according to SMM survey.

The inventory in the Shanghai bonded zone dipped 3,700 mt to 156,800 mt, and the inventory in the Guangdong bonded zone grew 1,500 mt to 14,900 mt. The spot trades are sluggish at the year-end. The import losses exceeded 500 yuan/mt due to the poor SHFE/LME copper price ratio, weakening the demand for customs declaration.

As far as SMM understood, there were concentrated arriving shipments this week and those cargoes are expected to go to the bonded zone next week. The bonded zone inventories will thus grow.
Copper Inventory in Major Chinese Markets Dipped 3,600 mt on Week

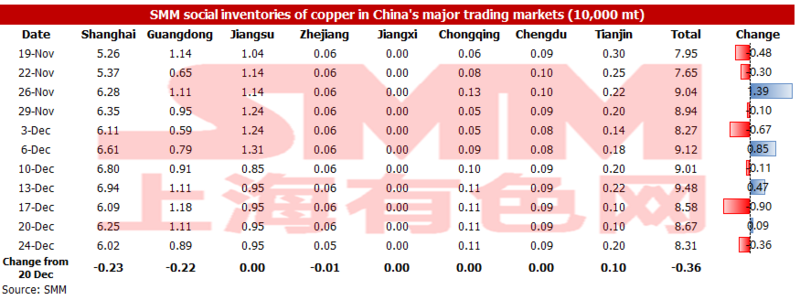
As of Friday December 24, copper inventory across major Chinese markets fell 3,600 mt from Monday to 83,100 mt. The inventory decline was milder than the previous week. The inventory in Tianjin increased slightly by 1,000 mt, while the inventory decreased across Shanghai, Guangdong and Zhejiang. And there was little change in the inventories in other regions.

Specifically, the inventory in Shanghai decreased by 2,300 mt to 60,200 mt, the inventory in Guangdong dipped 2,200 mt to 8,900 mt, and the inventory in Zhejiang fell 100 mt to 500 mt. The consumption was weak in various regions this week. And lower arriving shipments drove the inventory decline. The shipments arrivals of imported copper decreased due to the tax control issues. And the logistics efficiency for domestic copper decreased noticeably due to the COVID-19 pandemic in various regions.

Consumption is expected to weaken further in the last week of the year. The market shall pay attention to whether the shipments arrivals will increase next week. SMM expects the shipments arrivals of imported copper will increase next week, and the delivery volume from smelters will also increase at the end of the year. Therefore, SMM expects that domestic inventories will increase slightly next week.

Tuyên bố về Nguồn Dữ liệu: Ngoại trừ thông tin công khai, tất cả dữ liệu khác được SMM xử lý dựa trên thông tin công khai, giao tiếp thị trường và dựa trên mô hình cơ sở dữ liệu nội bộ của SMM. Chúng chỉ mang tính chất tham khảo và không cấu thành khuyến nghị ra quyết định.

Để biết thêm thông tin hoặc có thắc mắc gì, vui lòng liên hệ: lemonzhao@smm.cn
Để biết thêm thông tin về cách truy cập báo cáo nghiên cứu, vui lòng liên hệ:service.en@smm.cn
Tin Liên Quan
[SMM Tin tức Crom] Transnet lần đầu có lãi sau bốn năm khi sản lượng đường sắt tăng 4,9% lên 167,9 triệu tấn
3 giờ trước
[SMM Tin tức Crom] Transnet lần đầu có lãi sau bốn năm khi sản lượng đường sắt tăng 4,9% lên 167,9 triệu tấn
Đọc thêm
[SMM Tin tức Crom] Transnet lần đầu có lãi sau bốn năm khi sản lượng đường sắt tăng 4,9% lên 167,9 triệu tấn
[SMM Tin tức Crom] Transnet lần đầu có lãi sau bốn năm khi sản lượng đường sắt tăng 4,9% lên 167,9 triệu tấn
Tập đoàn logistics vận tải hàng hóa quốc doanh Nam Phi Transnet báo cáo lợi nhuận 4,6 tỷ rand cho năm tài chính kết thúc ngày 31/3/2026, đánh dấu lợi nhuận năm đầu tiên sau bốn năm, đảo ngược khoản lỗ 1,9 tỷ rand của năm trước. Doanh thu tăng 7,1% lên 88,6 tỷ rand, nhờ sản lượng đường sắt và đường ống tăng cùng với mức tăng giá cước bình quân gia quyền. Sản lượng đường sắt, do bộ phận vận hành lớn nhất của Transnet quản lý, tăng 4,9% lên 167,9 triệu tấn từ 160,1 triệu tấn một năm trước đó, trong khi sản lượng đường ống tăng 6,9% lên 14,3 tỷ lít. EBITDA tăng 0,7% lên 30,9 tỷ rand, với biên EBITDA thu hẹp 2,2 điểm phần trăm xuống 34,8%, và chi phí hoạt động ròng tăng 10,8% lên 57,7 tỷ rand. Một phần đáng kể lợi nhuận đến từ một giao dịch một lần thay vì từ hoạt động kinh doanh. Transnet đã chuyển nhượng 49,999% lợi ích tại Cảng Gateway Durban cho International Container Terminal Services Inc. với giá 10,5 tỷ rand, có hiệu lực từ ngày 1/1/2026, tạo ra khoản lãi 12,5 tỷ rand từ việc chuyển nhượng bao gồm cả điều chỉnh giá trị hợp lý liên quan. Tổng giám đốc điều hành tập đoàn Michelle Phillips cho biết công ty vẫn còn chặng đường dài trong quá trình phục hồi, lưu ý rằng sản lượng đường sắt vẫn thấp hơn mục tiêu 180 triệu tấn đã công bố trước đó, mà bà mô tả là điều kiện tiên quyết để hoạt động kinh doanh cốt lõi hòa vốn. Nợ vay tăng lên 150,7 tỷ rand, và tổng vốn đầu tư đạt 23,3 tỷ rand trong năm, với kế hoạch đầu tư thêm 129,1 tỷ rand trong năm năm tới. Kết quả này có ý nghĩa liên quan đến ngành crôm của Nam Phi, vốn phụ thuộc vào mạng lưới đường sắt và cảng của Transnet để vận chuyển khối lượng xuất khẩu quặng crôm kỷ lục, và nơi mà các hạn chế về hậu cần đường sắt và cảng đã nhiều lần bị các tổ chức ngành nghề chỉ ra là lực cản cơ cấu đối với khả năng cạnh tranh của hợp kim sắt, buộc phải phụ thuộc nhiều hơn vào vận tải đường bộ đắt đỏ hơn. Transnet cũng báo cáo tiến triển trong việc mở mạng lưới đường sắt cho các nhà khai thác bên thứ ba, đã ký kết Thỏa thuận tiếp cận đường sắt với 11 công ty vận hành tàu, với các dịch vụ đầu tiên dự kiến bắt đầu trong năm tài chính 2026/27. Kết quả của Transnet không công bố sản lượng cụ thể của quặng crôm hoặc hợp kim sắt trong số liệu đường sắt hoặc cảng, khiến mức độ cải thiện trong hiệu suất hậu cần cụ thể cho crôm vẫn chưa được định lượng.
3 giờ trước
[SMM Tin nhanh Crom] Outokumpu Ký Thỏa thuận Hỗ trợ Mặt đất Dài hạn cho Kemi, Mỏ Crom Đang Hoạt động Duy nhất của Châu Âu
3 giờ trước
[SMM Tin nhanh Crom] Outokumpu Ký Thỏa thuận Hỗ trợ Mặt đất Dài hạn cho Kemi, Mỏ Crom Đang Hoạt động Duy nhất của Châu Âu
Đọc thêm
[SMM Tin nhanh Crom] Outokumpu Ký Thỏa thuận Hỗ trợ Mặt đất Dài hạn cho Kemi, Mỏ Crom Đang Hoạt động Duy nhất của Châu Âu
[SMM Tin nhanh Crom] Outokumpu Ký Thỏa thuận Hỗ trợ Mặt đất Dài hạn cho Kemi, Mỏ Crom Đang Hoạt động Duy nhất của Châu Âu
Nhà cung cấp sản phẩm hạ tầng khai thác mỏ toàn cầu Jennmar đã ký kết quan hệ đối tác dài hạn với nhà sản xuất thép không gỉ Outokumpu Corporation để cung cấp các sản phẩm kiểm soát nền đất cho mỏ Kemi ở Phần Lan, mỏ hầm lò lớn nhất nước này và là mỏ crôm duy nhất đang hoạt động tại châu Âu. Jennmar đã thành lập một pháp nhân chuyên trách Jennmar Finland nhằm tinh gọn các giao dịch thương mại cho Outokumpu và các đội quản lý mỏ. Theo thỏa thuận kéo dài nhiều năm, Jennmar sẽ cung cấp đầy đủ các thiết bị gia cố nền đất phù hợp với điều kiện hầm lò của Kemi, bao gồm bu lông mái, bu lông cáp, lưới thép, phụ kiện thép và nhựa bơm. Công ty cho biết sẽ tận dụng chuỗi cung ứng toàn cầu và chuyên môn kỹ thuật của mình để hỗ trợ an toàn, ổn định và hiệu quả sản xuất tại mỏ, đồng thời sẽ phối hợp với đội quản lý mỏ Kemi và các đội kỹ thuật hầm lò thực hiện quy trình quản lý thay đổi có cấu trúc nhằm tối ưu hóa hoạt động khai thác. Chủ tịch Jennmar Europe Mike Petkovich mô tả Kemi là một trong những hoạt động khai thác lớn nhất và ấn tượng nhất châu Âu. Mỏ Kemi có công suất chế biến quặng 2,7 triệu tấn/năm và cung cấp crôm cho hoạt động sản xuất ferôcrôm và thép không gỉ của Outokumpu tại Tornio, miền bắc Phần Lan, khiến nơi đây trở thành ví dụ hiếm hoi về chuỗi giá trị crôm tích hợp hoàn toàn từ mỏ đến thép không gỉ hoạt động trong phạm vi châu Âu. Outokumpu vận hành các cơ sở sản xuất trên khắp Phần Lan, Đức, Thụy Điển, Hà Lan, Hoa Kỳ và Mexico. Thỏa thuận này nhấn mạnh việc tiếp tục đầu tư vào độ tin cậy vận hành của nguồn quặng crôm nội địa duy nhất của châu Âu trong bối cảnh các nhà sản xuất ferôcrôm trong khu vực phải đối mặt với sự cạnh tranh liên tục từ nguyên liệu nhập khẩu giá rẻ hơn.
3 giờ trước
[SMM Tin tức nhanh về Crom] Quặng crom là một trong hai ngành khai khoáng duy nhất của Nam Phi tăng trưởng trong tháng 7 khi sản lượng giảm 7,5%
4 giờ trước
[SMM Tin tức nhanh về Crom] Quặng crom là một trong hai ngành khai khoáng duy nhất của Nam Phi tăng trưởng trong tháng 7 khi sản lượng giảm 7,5%
Đọc thêm
[SMM Tin tức nhanh về Crom] Quặng crom là một trong hai ngành khai khoáng duy nhất của Nam Phi tăng trưởng trong tháng 7 khi sản lượng giảm 7,5%
[SMM Tin tức nhanh về Crom] Quặng crom là một trong hai ngành khai khoáng duy nhất của Nam Phi tăng trưởng trong tháng 7 khi sản lượng giảm 7,5%
Sản lượng khai khoáng của Nam Phi giảm 7,5% so với cùng kỳ năm trước vào tháng 7/2026, với 10 trong số 12 ngành khai khoáng của nước này ghi nhận sụt giảm, theo công bố mới nhất về Khai khoáng: Sản lượng và Doanh số của Cơ quan Thống kê Nam Phi. Quặng crôm là một trong hai ngành duy nhất tăng trưởng, tăng 13,7% so với cùng kỳ, cùng với quặng mangan tăng 4,9%. Kim loại nhóm bạch kim là tác nhân tiêu cực lớn nhất, với sản lượng giảm 13,5% và kéo giảm 3,2 điểm phần trăm khỏi con số tổng thể. Sản lượng than giảm 7,5%, đóng góp -2 điểm phần trăm, trong khi quặng sắt giảm 8,1%, tương ứng -1,3 điểm phần trăm. Kim cương ghi nhận mức giảm mạnh nhất ở mức 48,2%, niken giảm 18,8%, cùng với sản lượng vàng và đồng yếu hơn. Theo điều chỉnh theo mùa, sản lượng khai khoáng giảm 1,9% so với tháng trước trong tháng 7, sau mức tăng nhẹ 0,1% trong tháng 6 và mức giảm 5,6% trong tháng 5. Quặng crôm cũng nổi bật về mặt doanh số. Doanh số khoáng sản theo giá hiện hành giảm 5,6% so với cùng kỳ năm trước trong tháng 7, với vàng là tác nhân tiêu cực lớn nhất khi doanh số giảm 33,4%, kéo giảm 8,5 điểm phần trăm. Doanh số các khoáng sản phi kim loại khác giảm 26% và doanh số niken giảm 51,7%. Ngược lại, doanh số quặng crôm tăng 20%, đóng góp 1,6 điểm phần trăm và là tác nhân tích cực lớn nhất, cùng với doanh số than tăng 5%, thêm 1 điểm phần trăm. Doanh số khoáng sản theo giá hiện hành đã điều chỉnh theo mùa giảm 15,1% so với tháng trước trong tháng 7, sau mức tăng 2% trong tháng 6. Nhà thống kê khảo sát chính của Stats SA, Jean-Pierre Terblanche, nhận định tháng này là một sự sụt giảm đáng kể so với cùng kỳ năm trước đối với toàn ngành, với quặng crôm và mangan là các ngoại lệ trong bối cảnh suy giảm trên diện rộng.
4 giờ trước