

SHANGHAI, Oct 21 (SMM) -
China’s demand increases, and the lithium carbonate is mainly imported from Chile and Argentina
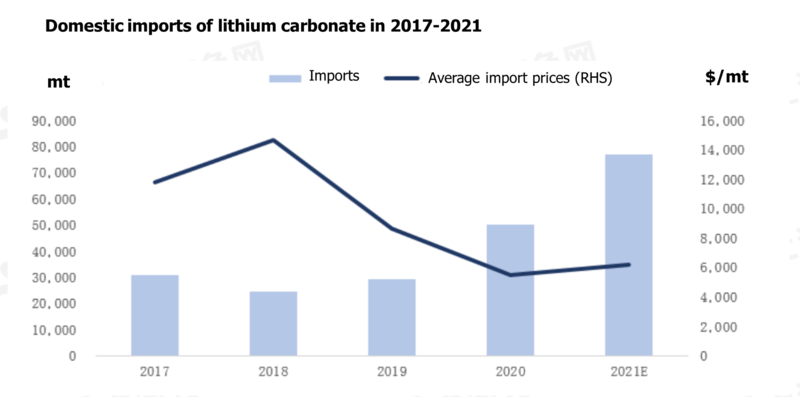
In 2018, with the concentrated release of lithium concentrate production capacity in Western Australia, China’s smelting companies such as Sichuan Zhiyuan Lithium doubled their lithium carbonate production capacity since July of the same year. Therefore, domestic smelting companies imported more lithium concentrates, while the imported lithium carbonates decreased, which dropped from 30,700 mt in 2017 to 24,500 mt in 2018.
With the decline in lithium prices, the profits of lithium mining companies in Western Australia reached a low level in 2019. The supply of lithium concentrate in Western Australia decreased, and domestic imports of lithium carbonate began to resume growth to 29,300 mt in the year. Since June 2019, with the end of domestic new energy subsidies, the downstream demand has rapidly weakened, and the domestic lithium carbonate prices have fallen rapidly. As such, more "default orders” existed in the overseas lithium carbonate markets, and a large number of lithium carbonate products have poured into the Chinese market. The industry’s inventory pressure increased sharply, and the prices of lithium carbonate fell.
From 2020 to 2021, as the overseas market was dominated by high-nickel car models, the demand for lithium hydroxide was much more than that for lithium carbonate. More overseas salt lake companies focused on lithium carbonate sales to the Chinese market. As the demand for new energy vehicles picked up after the COVID-19 pandemic, China's imports of lithium carbonate have increased significantly.
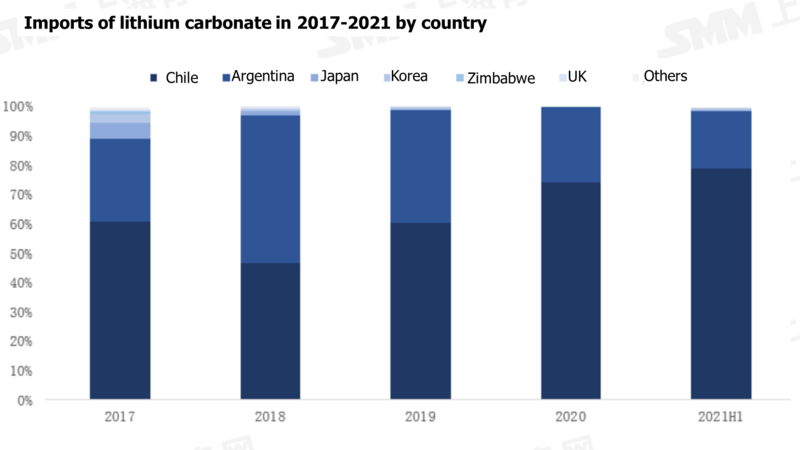
By countries, Chile and Argentina are the two largest exports of lithium carbonate to China, accounting for more than 99% of the total domestic imports. Japan, South Korea, Zimbabwe, and the United Kingdom have supplied some lithium carbonate to China, but accounting for a very low proportion.
 China's exports of lithium carbonate declined, with South Korea, Japan and the United States being the major destinations
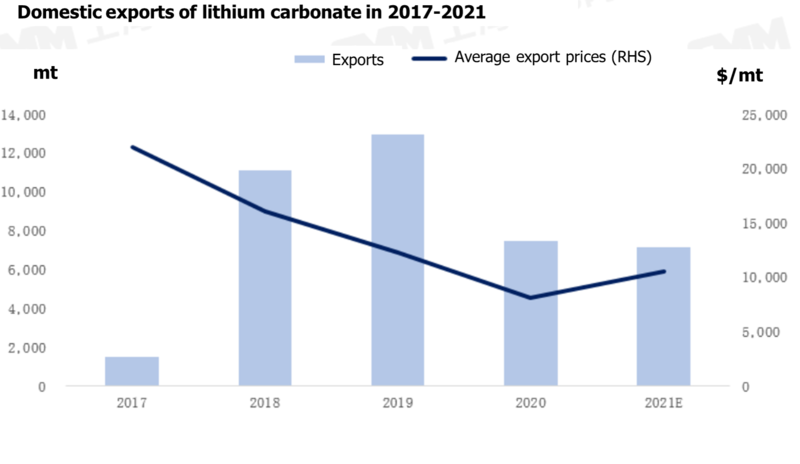
In 2017, China's lithium carbonate export volume was only 15,000 mt. Since 2018, China's lithium carbonate exports have grown rapidly, and became an important lithium carbonate exporter in addition to South America and Argentina. China's lithium carbonate exports grew rapidly to11,000 mt in 2018, and to 13,000 mt in 2019.
In 2020, the exports of lithium carbonate fell to 75,000 mt. On the one hand, due to the impact of the COVID-19 pandemic, the import and export trade was hindered. On the other hand, overseas automobile OEM manufacturers have built their own lithium salt smelters locally, reducing the demand for China’s lithium carbonate. In the first half of 2021, China’s export volume of lithium carbonate reached 3,800 mt, and the annual export volume is expected to be 7,200 mt, which is stable year-on-year.
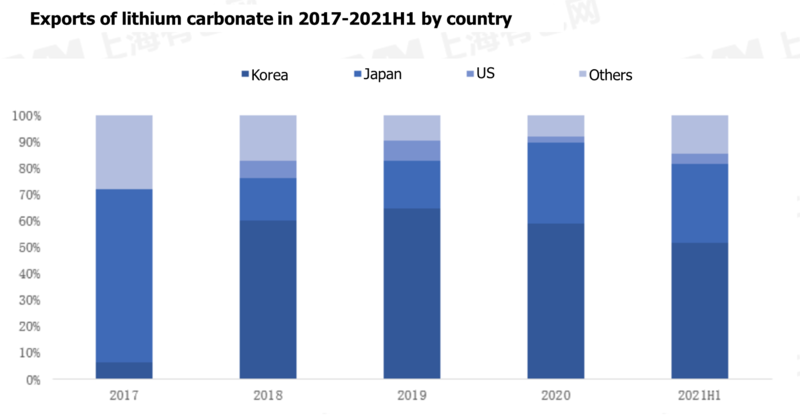
At present, China’s lithium carbonate is mainly exported to South Korea, Japan, and the United States. The total amount of lithium carbonate exported to these three countries accounted for about 85% of China’s total lithium carbonate exports. Among them, the lithium carbonate exported to South Korea, Japan and US in the first half of 2021 accounted for 52%, 30% and 3% of the total exports, respectively.
China’s lithium carbonate export structure has changed greatly in recent years. South Korea’s Samsung SDI, LG Chem, Ecopro, L&F, etc. have all expanded their NCM and NCA projects since 2018. And the NCM projects were focused on the 5 series and 6 series products. And the demand for lithium carbonate has increased. Therefore, since 2018, the proportion of China’s lithium carbonate exports to South Korea has increased significantly. In the later period, the NCM project gradually developed in the direction of high nickel 811. The demand for lithium hydroxide increased instead, and the demand for lithium carbonate decreased. So the exports of domestic of lithium carbonate also decreased.
China's lithium salt imports will mainly be industrial-grade lithium carbonate, and the lithium carbonate imports will continue to increase With the continuous production of new capacity of domestic lithium iron phosphate and ternary materials, China’s lithium iron phosphate will see expanded production capacity of1.22 million mt, and China’s ternary materials will see expanded production capacity of 730,000 mt. The demand for lithium carbonate is increasing year by year. China will continue to mainly import industrial grade lithium carbonate. With the substantial increase in domestic demand for lithium carbonate, the growth rate of lithium carbonate exports will gradually slow down.
Nearly 90% of the world’s lithium hydroxide production capacity is concentrated in China. The domestic dependence on lithium hydroxide imports is extremely low, and imports mainly come from Russia, Chile, etc.
In 2017-2018, the imports of lithium hydroxide were stable, and the annual import volume maintained between 1,200-1,300 mt/year. From 2019 to 2020, new domestic lithium hydroxide production capacity was put into production, the domestic dependence on overseas lithium hydroxide decreased further, and the import volume of lithium hydroxide will be reduced to 400-500 mt/year. In 2021, with the rapid increase in domestic demand for high-nickel ternary materials and effective domestic pandemic control, the domestic supply of quality lithium hydroxide has been unable to meet the domestic demand. The overseas lithium hydroxide imports increased. In the first half of 2021, the imports of lithium hydroxide reached 1,245 mt, and the total import volume will reach 2,000 mt throughout the year.
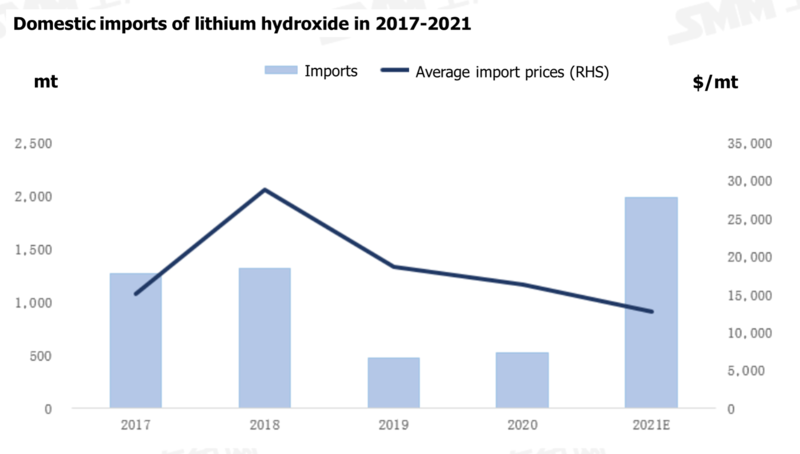
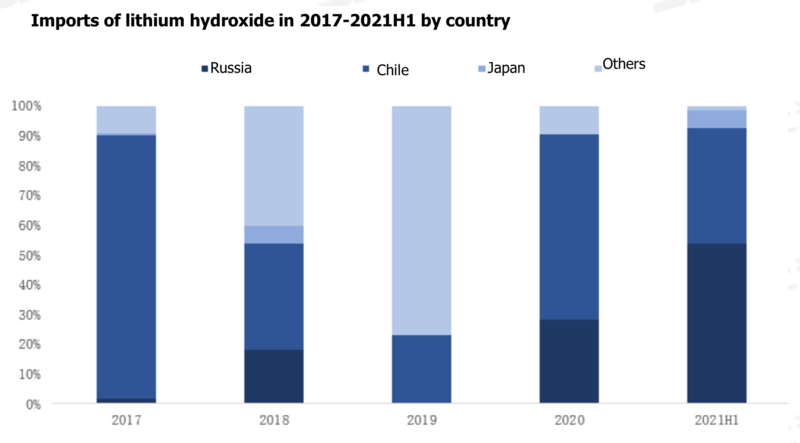
The structure of China's lithium hydroxide supplying countries has changed greatly. In 2017, nearly 89% of China's lithium hydroxide imports came from Chile. By 2019, the proportion of Chile's exports fell to 23%. In the first half of 2021, China’s imports of lithium hydroxide from Russia (54%), Chile (39%), and Japan (6%) accounted for 98% of total lithium hydroxide imports.
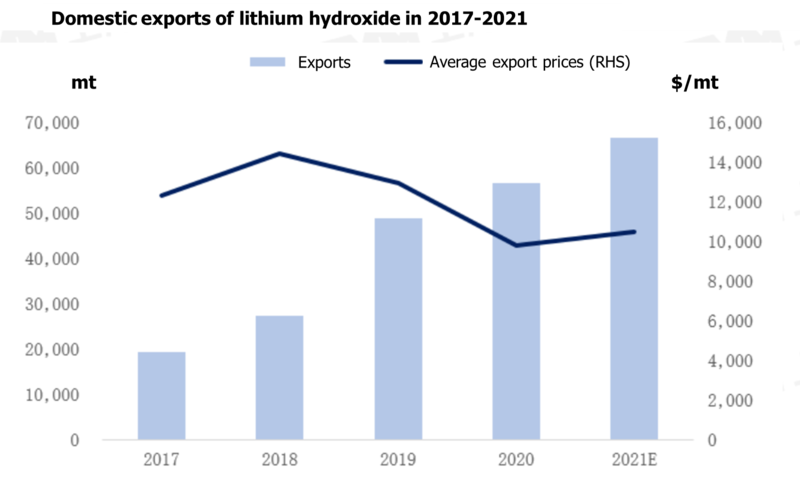
China is a major exporter of lithium hydroxide. With the expansion of overseas high nickel ternary materials production, the demand for lithium hydroxide continues to increase, with export mainly shipped to South Korea and Japan.
Since 2017, China's lithium hydroxide exports have increased from 19,000 mt in 2017 to 57,000 mt in 2020, mainly because the domestic lithium hydroxide smelting companies have started production. China has gradually become the major global supplier of lithium hydroxide. At present, more than 85% of the global production capacity is located in China, and the demand from the overseas markets is increasing. In the first half of 2021, China exported 35,000 mt of lithium hydroxide. Judging from various order plans and overseas high-nickel ternary material expansion expectations, it is estimated that in 2021, 66,000 mt of lithium hydroxide will be exported from China.
In terms of prices, the increase in the export prices of lithium hydroxide in 2017 was mainly driven by the increase in the prices of lithium carbonate. The main reason was that Tianqi Lithium announced the suspension of production for maintenance, which greatly reduced the supply of lithium carbonate in the market. While the export prices of lithium hydroxide have dropped all the way from 2018 to 2020. The development of high nickel is slow, and there is no obvious change on the demand side. But the lithium hydroxide supply side has seen low-priced goods as new entrants have been seizing the market.
Major domestic lithium hydroxide manufacturers such as Ganfeng Lithium, Tianqi Lithium, Yahua Group, Shengxin Lithium Energy, Ronghui Lithium, etc. have gradually entered the supply chain of overseas batteries and finished vehicles. The export volume of domestic lithium hydroxide will continue to increase due to the following reasons: 1) In terms of lithium hydroxide production technology, China's technology is more mature compared with Chile and other countries; 2) In terms of distance, compared with Chile and other South American countries, China is closer to Japan and South Korea, and the transportation costs are lower; 3) The technology for extracting lithium from spodumene is more mature than the technology for extracting lithium from salt lakes. Among them, China mostly uses spodumene lithium extraction technology, and Chile mostly uses salt lake lithium extraction technology.
China's lithium hydroxide is mainly exported to South Korea and Japan. According to data for H1, 2021, lithium hydroxide exported to South Korea (59%) and Japan (36%) accounted for 95% of total lithium hydroxide exports of China. In retrospect, starting from the second half of 2019, South Korean battery giants Samsung SDI, LG Chem, and SKI have been deploying in the sectors of high-nickel ternary materials and batteries. The demand for lithium hydroxide has begun to increase significantly, exceeding the demand from Japan. The further increase in China's lithium hydroxide exports also confirms the acceleration of the development of medium and high nickel materials such as NCM622, NCM811, and NCA in Japan and South Korea.
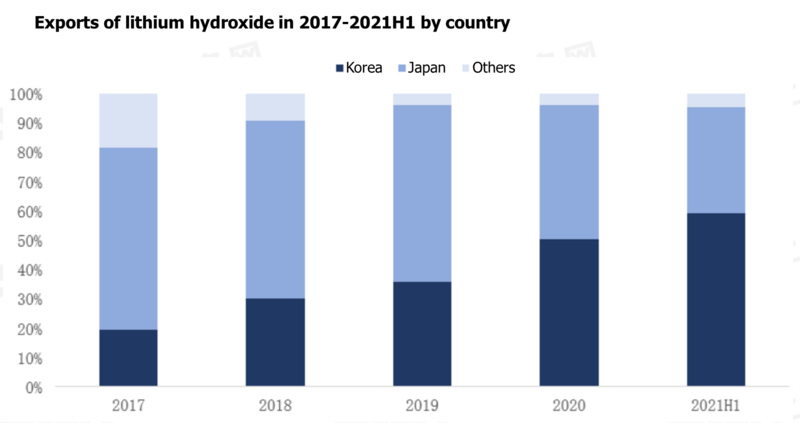
In the future, as China's leading lithium hydroxide suppliers enter the global high nickel supply chain, the proportion of lithium hydroxide exports will further increase in the future. Since 2018, Ganfeng Lithium has signed strategic cooperation agreements or long-term lithium salt supply agreements with global top-tier battery suppliers and auto OEMs such as LG Chem, Tesla, BMW, and Volkswagen.
With the gradual expansion of China's lithium hydroxide production capacity, the proportion of lithium hydroxide imports will be further reduced in the future. In 2021, China’s new lithium hydroxide production capacity will total 209,000 mt, of which Ganfeng Lithium’s new 50,000 mt lithium hydroxide project will start to ramp up production from Q1 in 2021, and Guangxi Tianyuan’s new 25,000 mt lithium hydroxide project will start production from 2021, and the others will be gradually be put into production in the second half of the year.



