Impact from high copper prices and secondary copper slowed recovery in copper rods produced with copper cathode

Đã xuất bản: Mar 23, 2021 10:27 (GMT+8)
Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues.

SHANGHAI, Mar 23 (SMM)—Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues. Cash flow issues are expected to intensify due to high tax payment in April. As such, factories and suppliers should liquidate stocks.
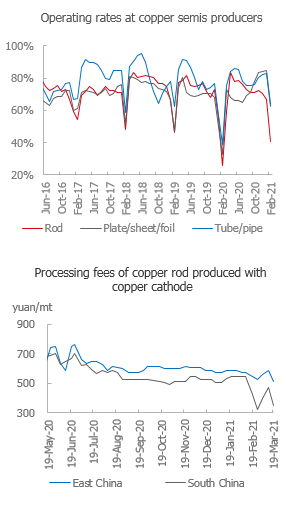
Operating rates at copper rod producers using secondary copper as raw material should return to a high level in March against accumulated orders, boosting secondary copper demand. However, decreased new orders at the end of last week and increased cash flow issues have limited the interest in purchasing. That combined with the demand for stock liquidation at suppliers, will keep normal supply and demand.

The average weekly price of #1 bare bright copper without invoice stood at 59,930 yuan/mt, an increase of 200 yuan/mt compared with the previous week, and the weekly average price difference between copper cathode and copper scrap stood at 2,217 yuan/mt, an increase of 385 yuan/mt. The average weekly discount of copper rod produced with secondary copper stood at 1,464 yuan/mt against the SHFE front-month copper contract, growing the advantage compared to copper rod produced with copper cathode.

For imported copper scrap, cif quotes for #1 copper scrap were Comex July copper less $0.21/lb, and offers for birch/cliff were Comex July copper less $0.36/lb. US brass was quoted at $5,650-5,850/mt. The coefficient for copper granules (98%) against LME copper stood at 93%, and the coefficient for bare bright copper against LME copper at 96-96.5%, on a cif basis.

Improved consumption of copper rod produced with secondary copper had significant impact on consumption of copper rod produced with copper cathode

Many producers of copper rod using secondary copper as feedstock have seen high orders, reporting strong supply and demand. The price spread between copper cathode and copper scrap has returned to above 2,000 yuan/mt, and discounts of copper rod produced with secondary copper reached a high of 1,550 yuan/mt against the SHFE front-month copper contract. Low-priced copper rods produced with secondary copper have been more desirable for downstream companies amid high copper prices, and this depressed consumption of copper rod produced with copper cathode which has been already weak. 

The impact of poor wire and cable demand and secondary copper rods has slowed recovery in the market of copper rod produced with copper cathode. Most of the producers are unlikely to return to normal production levels in March. As consumption picks up amid warmer weather, the market sentiment of the wire and cable industry should rise. Consumption of copper rods produced with copper cathode is expected to improve in April. However, the overly high copper price will depressed consumption. The current inventory of finished products at copper rod producers using copper cathode as feedstock stands at high levels. Producers will prioritise stock depletion and new orders at end users are unlikely to pass to copper rod plants using copper cathode as raw material any time soon. We believe that consumption of copper rods produced with copper cathode in April would hardly return to the peak season level of previous years.
Tuyên bố về Nguồn Dữ liệu: Ngoại trừ thông tin công khai, tất cả dữ liệu khác được SMM xử lý dựa trên thông tin công khai, giao tiếp thị trường và dựa trên mô hình cơ sở dữ liệu nội bộ của SMM. Chúng chỉ mang tính chất tham khảo và không cấu thành khuyến nghị ra quyết định.

Để biết thêm thông tin hoặc có thắc mắc gì, vui lòng liên hệ: lemonzhao@smm.cn
Để biết thêm thông tin về cách truy cập báo cáo nghiên cứu, vui lòng liên hệ:service.en@smm.cn
Tin Liên Quan
Dự án Vành đai Iberia phía Tây của Emerita theo PFS cho thấy NPV 776 triệu USD, tuổi thọ mỏ 21 năm
30 Oct 2026 22:39 (GMT+8)
Dự án Vành đai Iberia phía Tây của Emerita theo PFS cho thấy NPV 776 triệu USD, tuổi thọ mỏ 21 năm
Đọc thêm
Dự án Vành đai Iberia phía Tây của Emerita theo PFS cho thấy NPV 776 triệu USD, tuổi thọ mỏ 21 năm
Emerita công bố PFS cho dự án kẽm-chì-đồng Iberian Belt West: NPV 776 triệu USD, vòng đời 21 năm Emerita Resources (TSXV: EMO) ngày 29/10 đã công bố Nghiên cứu tiền khả thi (PFS) tích cực cho dự án đa kim Iberian Belt West (IBW) thuộc sở hữu 100% của công ty tại Vành đai Pyrite Iberia, Tây Ban Nha. Nghiên cứu cho thấy NPV sau thuế 776 triệu USD ở mức chiết khấu 8%, IRR 23,51%, vòng đời mỏ 21 năm và thời gian hoàn vốn sau thuế 1,9 năm. Vốn đầu tư ban đầu là 567 triệu USD bao gồm dự phòng. Trữ lượng có thể khai thác ban đầu đạt 23,4 triệu tấn với hàm lượng 2,30% kẽm, 1,13% chì, 0,45% đồng, 53 g/t bạc và 1,07 g/t vàng.
30 Oct 2026 22:39 (GMT+8)
Thị trường đồng gặp khó khăn vì thay đổi thuế và thiếu hụt nguồn cung vào tháng 10 năm 2026
30 Oct 2026 19:47 (GMT+8)
Thị trường đồng gặp khó khăn vì thay đổi thuế và thiếu hụt nguồn cung vào tháng 10 năm 2026
Đọc thêm
Thị trường đồng gặp khó khăn vì thay đổi thuế và thiếu hụt nguồn cung vào tháng 10 năm 2026
Vào tháng 10 năm 2026, chênh lệch giá đã bao gồm thuế giữa kim loại nguyên sinh và phế liệu thu hẹp từ 3.979 nhân dân tệ/tấn vào đầu tuần xuống còn 1.896 nhân dân tệ/tấn, sau đó phục hồi về khoảng 2.826-2.976 nhân dân tệ/tấn. Chênh lệch giá giữa thanh đồng cathode và thanh đồng thứ cấp cũng bị nén từ 1.250 nhân dân tệ/tấn xuống mức cực thấp dưới 430 nhân dân tệ/tấn trước khi bật tăng lên 1.450 nhân dân tệ/tấn. Mặc dù lợi thế thay thế trên sổ sách có biến động, nhưng phần lớn thời gian nó đã bị các yếu tố chi phí bào mòn đáng kể.
30 Oct 2026 19:47 (GMT+8)
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
30 Oct 2026 18:41 (GMT+8)
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
Đọc thêm
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
30 Oct 2026 18:41 (GMT+8)