[SMM thread] the road of accumulation is not over, and the upward road of steel price is not over.

Đã xuất bản: Jul 16, 2020 17:47
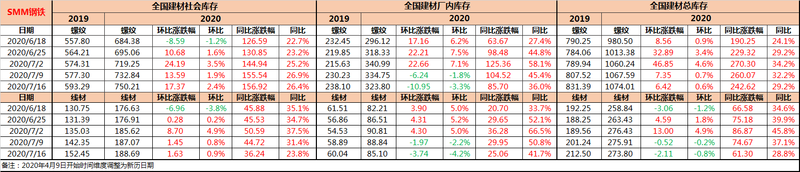
As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current year-on-year increase in inventory continues to narrow. (this week, the year-on-year increase of thread pool narrowed by 3%.


SMM7 March 16:

As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current inventory growth continues to narrow year-on-year (this week, the thread pool growth rate narrowed by 3 percentage points year-on-year).

Table 1: Overview of thread inventory
Source: SMM


Table 2: comparison of Thread inventory prices from 2018 to 2020
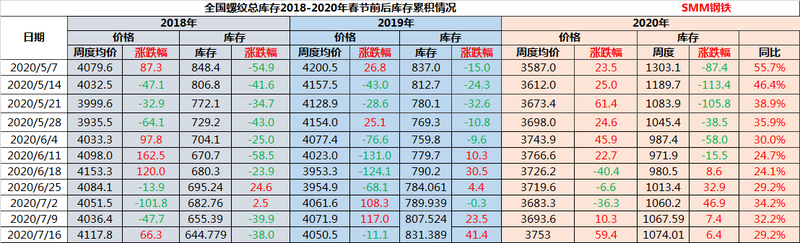
Note: due to the epidemic factors since 2020, due to the different opening times in different places, there is a certain error in the actual spot average price; the time dimension is the Gregorian calendar date.


Source: SMM

Specifically:

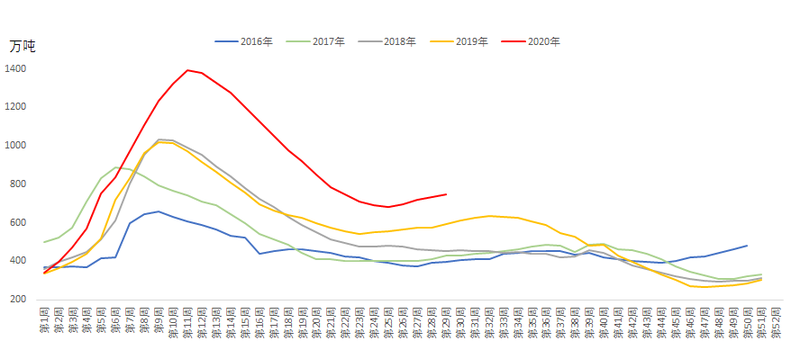
Social inventory of 7.5021 million tons, an increase of 173700 tons this week, + 2.4% month-on-month, + 26.9% year-on-year.

Under the background of a positive situation in the A-share bull market, the raw material side was led by the news side to rise first, driving the period snail to continue the strong situation in the past two weeks. The expectation of the spot market for the future is also improving, and the enthusiasm of traders to take goods has been significantly improved, accelerating the transfer of the factory warehouse to the social warehouse. While the terminal "steel needs" is "serious illness has not been cured", so the speed of accumulation has been accelerated.

Figure 1: an overview of the trend of threaded community library since 2016
Source: SMM

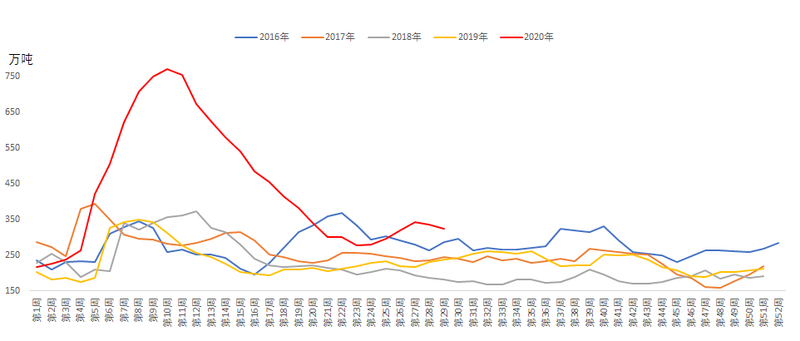
The inventory in the plant is 3.238 million tons, down 109500 tons this week,-3.3% month-on-month, + 36.0% year-on-year.

In addition to the market merchants' enthusiasm for taking goods driven by strong expectations, the decline in the output of steel mills is also an important reason for the decline in the factory warehouse. Under the dual pressure of high plant pressure and poor profitability, the overhaul and production reduction plans of steel mills have increased-according to SMM research, the planned rebar output of blast furnace steel mills in July decreased by 2% compared with the actual output in June, and the operating rate of electric furnace plants also dropped by about 11.52% compared with the same period in June.


Figure 2: an overview of the trend of thread factory warehouse from 2016 to now
Source: SMM

In the short term, the fundamentals of rebar are not unusual-the supply side is likely to maintain a small fluctuation at the current level, the demand side continues to be hit by precipitation, the road to rebar accumulation is not over, and steel prices are still in an awkward position of "neither up nor down". However, as more and more regions out of the "rainy season" haze, rush demand released as scheduled, thread fundamentals regained strong support, steel prices are expected to consolidate and continue to start.




Tuyên bố về Nguồn Dữ liệu: Ngoại trừ thông tin công khai, tất cả dữ liệu khác được SMM xử lý dựa trên thông tin công khai, giao tiếp thị trường và dựa trên mô hình cơ sở dữ liệu nội bộ của SMM. Chúng chỉ mang tính chất tham khảo và không cấu thành khuyến nghị ra quyết định.

Để biết thêm thông tin hoặc có thắc mắc gì, vui lòng liên hệ: lemonzhao@smm.cn
Để biết thêm thông tin về cách truy cập báo cáo nghiên cứu, vui lòng liên hệ:service.en@smm.cn
Tin Liên Quan
Úc Rà soát Thuế chống bán phá giá đối với Thép mạ kẽm từ Ấn Độ, Malaysia, Việt Nam trong bối cảnh lo ngại về kẽm
11 Sep 2026 18:30
Úc Rà soát Thuế chống bán phá giá đối với Thép mạ kẽm từ Ấn Độ, Malaysia, Việt Nam trong bối cảnh lo ngại về kẽm
Đọc thêm
Úc Rà soát Thuế chống bán phá giá đối với Thép mạ kẽm từ Ấn Độ, Malaysia, Việt Nam trong bối cảnh lo ngại về kẽm
Ngày 9 tháng 9 năm 2026, Australia khởi xướng rà soát cuối kỳ lần thứ hai đối với biện pháp chống bán phá giá thép mạ kẽm từ Ấn Độ, Malaysia và Việt Nam, đồng thời tiến hành rà soát cuối kỳ riêng đối với biện pháp chống trợ cấp áp dụng cho hàng nhập khẩu từ Ấn Độ. Kỳ rà soát từ tháng 7/2025 đến tháng 6/2026, với báo cáo cuối cùng dự kiến công bố trước ngày 11 tháng 2 năm 2027. Do thép mạ kẽm là lĩnh vực tiêu thụ kẽm lớn nhất, các biện pháp này ảnh hưởng trực tiếp đến chi phí xuất khẩu và năng lực cạnh tranh, có khả năng tác động đến nhu cầu kẽm nội địa và chuỗi cung ứng của Australia. Việc duy trì thuế sẽ mang lại sự bảo hộ nhất định cho năng lực sản xuất thép và mạ trong nước, trong khi chấm dứt thuế có thể làm gia tăng hàng nhập khẩu giá rẻ và ảnh hưởng đến tiêu thụ kẽm trong khu vực. Kết quả cuối cùng vẫn phụ thuộc vào quyết định của cơ quan chức năng.
11 Sep 2026 18:30
Dự án mở rộng trị giá 200 triệu USD của JCC Hongyuan Copper đặt mục tiêu nâng công suất lên 550.000 tấn vào năm 2027
7 Sep 2026 15:43
Dự án mở rộng trị giá 200 triệu USD của JCC Hongyuan Copper đặt mục tiêu nâng công suất lên 550.000 tấn vào năm 2027
Đọc thêm
Dự án mở rộng trị giá 200 triệu USD của JCC Hongyuan Copper đặt mục tiêu nâng công suất lên 550.000 tấn vào năm 2027
Dự án mở rộng sản xuất đồng cathode 300.000 tấn/năm của Công ty Đồng Hồng Nguyên JCC, công ty con của Tập đoàn Đồng Giang Tây, đã bước vào giai đoạn thông báo công khai trước khi phê duyệt đánh giá tác động môi trường vào ngày 4 tháng 9, với tổng vốn đầu tư khoảng 1,416 tỷ nhân dân tệ. Dự kiến khởi công vào tháng 9 năm 2026 và hoàn thành vào tháng 12 năm 2027. Sau khi hoàn thành, tổng công suất của Hồng Nguyên JCC sẽ tăng từ 250.000 tấn lên 550.000 tấn.
7 Sep 2026 15:43
Đồng Yên Nhật tăng giá, USD/JPY giảm xuống dưới 159 giữa đồn đoán can thiệp
3 Sep 2026 19:00
Đồng Yên Nhật tăng giá, USD/JPY giảm xuống dưới 159 giữa đồn đoán can thiệp
Đọc thêm
Đồng Yên Nhật tăng giá, USD/JPY giảm xuống dưới 159 giữa đồn đoán can thiệp
[SMM Tin nhanh Kim loại quý] Đồng yên Nhật tăng vọt trong phiên giao dịch thứ Tư, với tỷ giá USD/JPY giảm xuống dưới 159 và đóng cửa giảm 0,92% ở mức 158,69, làm dấy lên đồn đoán về sự can thiệp tiền tệ của Nhật Bản. Chỉ số đô la cũng giảm mạnh, với môi trường đô la yếu hơn hỗ trợ cho kim loại quý.
3 Sep 2026 19:00

