

SHANGHAI, Feb 14 (SMM) – Prices of electrolytic manganese in China have surged about 2,000 yuan/mt since the market reopened after the Chinese New Year holiday, as China’s virus containment efforts shut producers, delayed resumption and slowed deliveries, leading to supply shortages in the spot market. Improved demand also gave a lift to manganese prices as steelmakers in China stepped up procurement in their tenders for the new month.
Quotes for spot electrolytic manganese in Guangxi were heard at 12,500-13,000 yuan/mt as of Wednesday February 13, and quotes in major trading hubs were generally offered in this range. Manganese prices are expected to remain bullish in the short term.
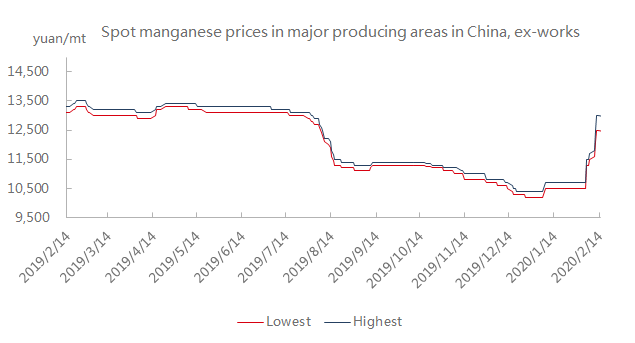
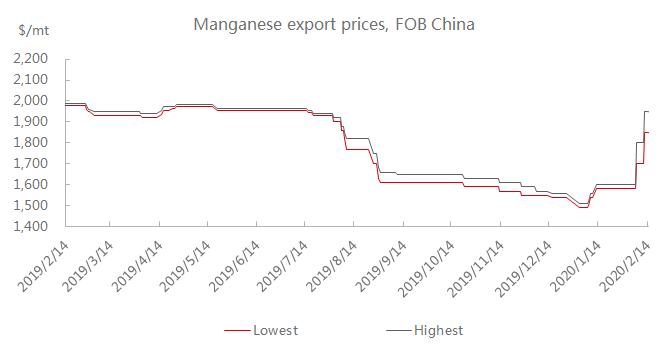
Producers of electrolytic manganese in major producing areas such as Hubei, Yunnan and Shaanxi suspended production after authorities intensified control amid the novel coronavirus outbreak that began in late January, ahead of the CNY holiday. They have yet to resume production as of the middle of February. Notably, manganese producers stockpiled manganese ore before the holiday to prepare for post-holiday production, as most of mines in the “Manganese Delta” at the junction of Guizhou, Hunan, and Chongqing would halt production during the CNY holiday. Logistics constraints caused by the epidemic, meanwhile, forced manganese producers to delay deliveries for orders made before the holiday, tightening supply to the spot market.
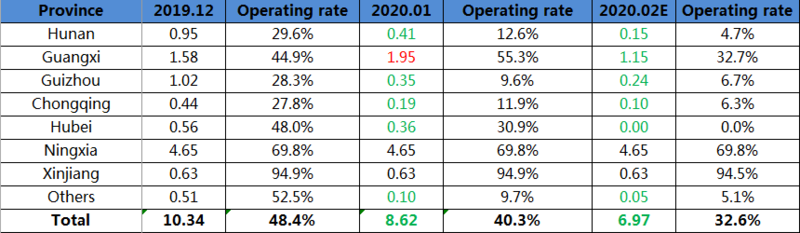
Manganese producers in the virus epicentre of Hubei are expected to remain shut for two to three months, while producers in Ningxia and Xinjiang, where felt less impact, have resumed production, with operating rates and daily output barely changed from levels seen before the holiday.
Daily production of electrolytic manganese in China stood at 3,900-4,200 mt in December, showed an SMM survey. The daily output fell to 3,700 mt in January, before declining further to about 2,400 mt in February, which was down 35.14% from January. Manganese producers in Ningxia and Xinjiang now maintain normal production, while small output is seen from Hunan, Sichuan, Chongqing and Guizhou. Tianyuan Manganese in Ningxia is the largest producer in terms of daily output, as its feedstock—ore imported from Ghana and captive sulphuric acid plant keep its manganese production from being affected.
The “Manganese Delta” at the junction of Guizhou, Hunan, and Chongqing: Daily output across all manganese producers in Hunan was below 70 mt in the middle of February, while daily output in Chongqing, where most of producers remained shut, was 20-30 mt. Major manganese producers in Guizhou have daily output of about 40 mt. Manganese producers in this region struggled to resume production as authorities tightened their approval for resumption. Required virus prevention measures and transportation restrictions also deterred manganese producers from resuming operations immediately.
Guangxi: Operating rates across manganese producers in Guangxi and daily output were slightly higher than the Manganese Delta, as Qinzhou port enabled logistics to recover faster. But strict inspections at ports subdued production, with daily manganese output in Guangxi now standing at about 500 mt.
Shaanxi: Manganese producers in Shaanxi remain shut as they face stricter control from authorities. Shaanxi is bordered by the epicentre of Hubei. Workers from other regions are restricted from returning to factories, while closed roads affected the deliveries of raw materials.
The South Korean steelmaker—POSCO (Pohang Iron and Steel Company) plans to buy 4,180 mt of electrolytic manganese in its tender for March, up 1,900 mt from February. It also raised its purchasing price by $332/mt to $1,840/mt. Demand improvement, coupled with a tight market, significantly bolstered manganese prices.
Some 200-series stainless steel producers, meanwhile, stepped up procurement of manganese metal for February, and raised purchasing prices by 1,000-1,500 yuan/mt. Most of 200-series stainless steel producers stockpiled manganese ahead of the CNY holiday, but they are likely to see raw material shipments struggling to arrive in the near term, given logistics constraints amid the outbreak.
Prices of high-purity manganese sulphate in China inched up after the CNY holiday, and are likely to follow electrolytic manganese higher. Major producers of high-purity manganese sulphate are located in Guizhou and Hunan. Large plants in Guizhou did not suspend production, while small-scale ones shut briefly. SMM learned that large-scale high-purity manganese sulphate producers in Guizhou secured a large number of orders before the CNY holiday, but prices were low. Deliveries of some high-purity manganese sulphate orders may be delayed due to the logistics constraints.



