[SMM Analysis] Significant Growth and Structural Changes: A Comprehensive Review of Anode Materials in 2024H1

เผยแพร่แล้ว: Jul 25, 2024 10:30 (GMT+8)
แหล่งที่มา: SMM
Half of 2024 has passed. During this period, despite the persistent low prices and overcapacity in the anode materials market, the early surge in downstream demand has invigorated the anode market in H1.

Half of 2024 has passed. During this period, despite the persistent low prices and overcapacity in the anode materials market, the early surge in downstream demand has invigorated the anode market in H1. For companies, the past six months have been complex. In the same market environment, different expectations and strategies led to varied choices and outcomes. In my view, "significant growth and structural changes" best describe the anode market in H1.

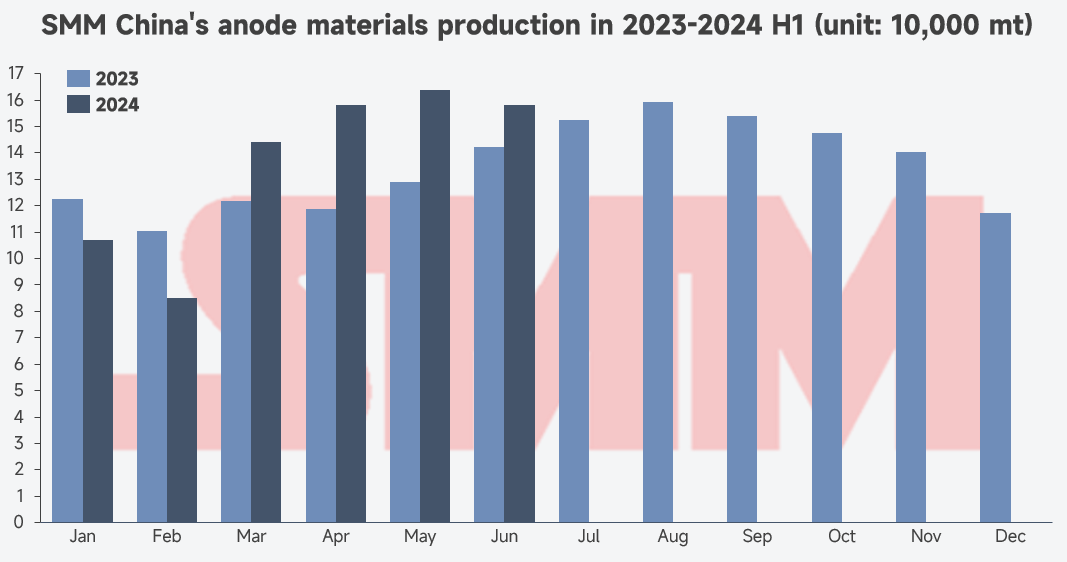
According to SMM, in 2024H1, China's graphite anode materials production reached 816,400 mt, up 9.6% YoY.
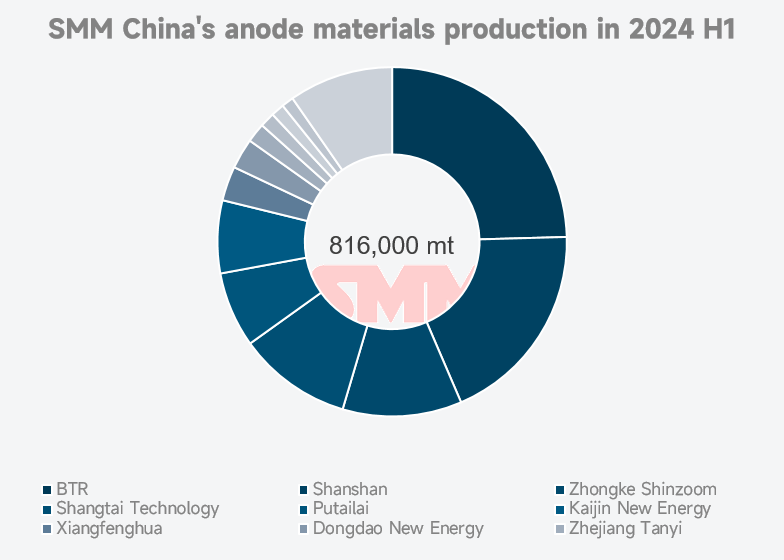
In 2024H1, BTR maintained its leading position in the anode materials industry, with a total share of about 25%. Due to varying predictions on the duration of the anode market downturn and differences in companies' finances, inventory, and market focus, the strategic routes chosen by leading companies diverged significantly, altering the industry's "three major" structure.
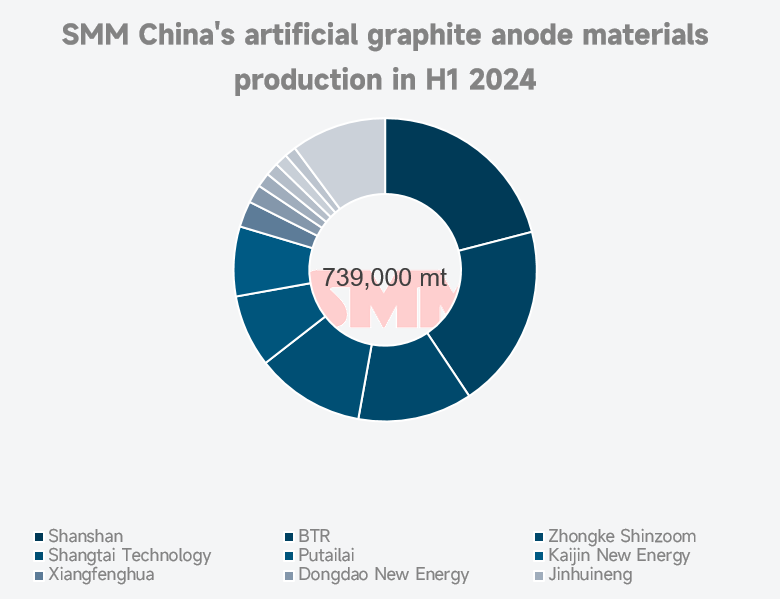
In 2024H1, with the continued weakness in raw material and graphitization costs, artificial graphite anodes still had a clear cost and price advantage. Meanwhile, as natural graphite exports were strictly controlled by the graphite bill, overall demand weakened. Additionally, the production and sales growth of silicon-based and hard carbon anode products was lower than expected, further increasing the market share of domestic artificial graphite anodes. According to SMM, in 2024H1, China's artificial graphite anode production was 739,000 mt, accounting for about 91%, up 11% YoY. Shanshan continued to dominate the artificial graphite materials industry, with a total share of about 21%.

End-users' performance requirements for anode materials also contributed to the increased share of artificial graphite anodes. NEV sales saw significant growth in H1, and power battery cells demanded higher performance in fast charging. Leading companies, leveraging their technical advantages, captured the fast-charging anode materials market. Shanshan and BTR maintained top positions, while Zhongke Shinzoom and Shangtai Technology also saw an increase in their shares. Energy storage sector, as the market heated up, the iteration of 314Ah batteries also raised higher specifications for energy storage anode materials. New entrants like Sunrise New Energy seized the development opportunities in the energy storage market, actively responded to new product demands from customers, and significantly increased their shipments and industry share.
In 2024H1, industry concentration continued to rise, with CR6 reaching 78%. In the current context of limited cost and price reduction room for anodes, downstream customers are more focused on "quality" and "stable supply" rather than "low prices." For battery cell manufacturers, anode companies that can timely respond to customer needs and ensure quality and quantity in supply are more worthy of selection than those offering merely low prices. For anode companies, this is not only the "confidence" to maintain product quality and scale amid the market downturn but also raises higher requirements for controlling production processes.
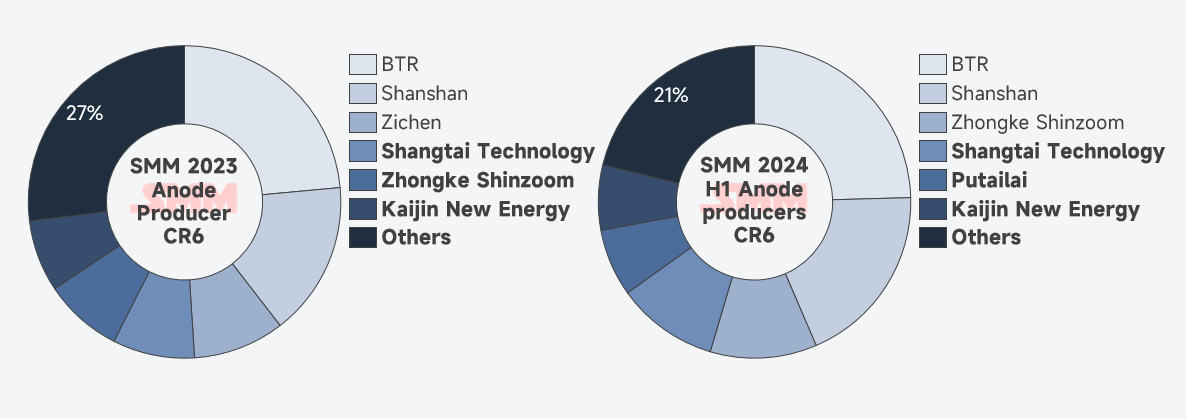
Looking back, although there was significant growth in 2024H1, the anode industry still faces persistent issues, and it cannot be considered a "spring bloom." The demand highlight may even fade in Q3 as downstream enthusiasm cools. However, the industry downturn is not entirely without benefits for companies: optimizing and upgrading product structures, managing inventory and finances, and improving the upstream and downstream chains are perpetual challenges that become even more crucial now. While industry and supply chain prosperity are essential for company growth, when the "wind" weakens, only strong "internal improvement" can ensure higher and more stable standing.

คำชี้แจงแหล่งที่มาของข้อมูล: นอกจากข้อมูลที่เปิดเผยต่อสาธารณะแล้ว ข้อมูลอื่นๆ ทั้งหมดได้รับการประมวลผลโดย SMM จากข้อมูลสาธารณะ การสื่อสารกับตลาด และการพึ่งพาแบบจำลองฐานข้อมูลภายในของ SMMข้อมูลเหล่านี้มีไว้เพื่ออ้างอิงเท่านั้น ไม่ถือเป็นข้อเสนอแนะในการตัดสินใจ

หากมีข้อสงสัยหรือต้องการทราบข้อมูลเพิ่มเติม กรุณาติดต่อ: lemonzhao@smm.cn
หากต้องการข้อมูลเพิ่มเติมเกี่ยวกับวิธีการเข้าถึงรายงานการวิจัยของเรา โปรดติดต่อ:service.en@smm.cn
ข่าวที่เกี่ยวข้อง
[SMM News] หน่วยงานกำกับดูแลของบราซิลสั่งระงับการดำเนินงานบางส่วนที่เหมือง Sigma Lithium เนื่องจาก “ความเสี่ยงที่ใกล้จะเกิดขึ้น”
2 ชั่วโมงที่แล้ว
[SMM News] หน่วยงานกำกับดูแลของบราซิลสั่งระงับการดำเนินงานบางส่วนที่เหมือง Sigma Lithium เนื่องจาก “ความเสี่ยงที่ใกล้จะเกิดขึ้น”
อ่านเพิ่มเติม
[SMM News] หน่วยงานกำกับดูแลของบราซิลสั่งระงับการดำเนินงานบางส่วนที่เหมือง Sigma Lithium เนื่องจาก “ความเสี่ยงที่ใกล้จะเกิดขึ้น”
[SMM News] หน่วยงานกำกับดูแลของบราซิลสั่งระงับการดำเนินงานบางส่วนที่เหมือง Sigma Lithium เนื่องจาก “ความเสี่ยงที่ใกล้จะเกิดขึ้น”
เมื่อวันที่ 2 ตุลาคม ซิกมา ลิเธียม ได้ระงับกิจกรรมการทำเหมืองและอุตสาหกรรมทั้งหมดที่แหล่งโกรตา ดู ซีรีรู ในบราซิล ซึ่งเป็นสินทรัพย์การผลิตเพียงแห่งเดียวของบริษัท ระหว่างรอคำตัดสินของศาลอุทธรณ์กลางเกี่ยวกับคำสั่งคุ้มครองชั่วคราวเรื่องใบอนุญาตด้านสิ่งแวดล้อม สำนักงานเหมืองแร่แห่งชาติบราซิล (ANM) ได้สั่งให้หยุดการทำเหมืองบนลาดด้านตะวันออกของหลุมเหนือ ผลผลิตหัวแร่จากแหล่งดังกล่าวหยุดชะงักระหว่างการระงับ ขณะที่การขายผงลิเธียมยังดำเนินต่อไป ซิกมาเลื่อนเป้าหมายการผลิต 12 เดือนที่ 240,000 ตันออกไปสามเดือน และคงเป้าหมายปี 2570 ไว้ที่ 330,000 ตันของหัวแร่
2 ชั่วโมงที่แล้ว
[SMM News] Lithium Argentina เผยแผนขยายกำลังการผลิตแบบเฟสสำหรับ Cauchari-Olaroz
2 ชั่วโมงที่แล้ว
[SMM News] Lithium Argentina เผยแผนขยายกำลังการผลิตแบบเฟสสำหรับ Cauchari-Olaroz
อ่านเพิ่มเติม
[SMM News] Lithium Argentina เผยแผนขยายกำลังการผลิตแบบเฟสสำหรับ Cauchari-Olaroz
[SMM News] Lithium Argentina เผยแผนขยายกำลังการผลิตแบบเฟสสำหรับ Cauchari-Olaroz
ลิเธียม อาร์เจนตินา ยืนยันการขยายระยะที่ 2 ที่โครงการทะเลสาบเกลือ Cauchari-Olaroz ในอาร์เจนตินา โดยเพิ่มกำลังการผลิตลิเธียมคาร์บอเนต 45,000 ตันต่อปี และทำให้กำลังการผลิตรวมเป็น 85,000 ตันต่อปี ในจำนวนนี้ โมดูลเริ่มต้น 10,000 ตันต่อปีที่ใช้เทคโนโลยีการสกัดลิเธียมโดยตรงแบบดูดซับ คาดว่าจะเริ่มเดินเครื่องได้ในปี 2571 โดยประมาณการมูลค่าปัจจุบันสุทธิหลังหักภาษีที่ 3.1 พันล้านดอลลาร์สหรัฐ และอัตราผลตอบแทนภายในที่ 28.5% ณ ราคาลิเธียมคาร์บอเนต 18,000 ดอลลาร์สหรัฐต่อตัน โดยมีต้นทุนการดำเนินงาน 5,006 ดอลลาร์สหรัฐต่อตัน เงินลงทุนรวมสำหรับระยะที่ 2 อยู่ที่ 1 พันล้านดอลลาร์สหรัฐ โครงการยังคงต้องได้รับการอนุมัติจากหน่วยงานกำกับดูแล และงานวิศวกรรมรายละเอียดสำหรับโมดูลเริ่มต้นมีกำหนดแล้วเสร็จภายในปลายปีนี้ ปริมาณอุปทานเพิ่มเติมมีกำหนดเริ่มตั้งแต่ปี 2571 เป็นต้นไป
2 ชั่วโมงที่แล้ว
[SMM News] Patagonia Lithium เสร็จสิ้นการทดสอบสูบน้ำ 72 ชั่วโมงที่ Cilon
2 ชั่วโมงที่แล้ว
[SMM News] Patagonia Lithium เสร็จสิ้นการทดสอบสูบน้ำ 72 ชั่วโมงที่ Cilon
อ่านเพิ่มเติม
[SMM News] Patagonia Lithium เสร็จสิ้นการทดสอบสูบน้ำ 72 ชั่วโมงที่ Cilon
[SMM News] Patagonia Lithium เสร็จสิ้นการทดสอบสูบน้ำ 72 ชั่วโมงที่ Cilon
ปาตาโกเนีย ลิเธียม เสร็จสิ้นการทดสอบสูบน้ำ 72 ชั่วโมงที่หลุมเจาะหมายเลข 8 บนสัมปทานซีลอน ด้วยอัตราการไหล 2,043 ลิตรต่อชั่วโมง และสูบน้ำขึ้นมา 146,800 ลิตร ความเข้มข้นของลิเธียมอยู่ที่ 232 ppm ที่ความลึก 250 เมตร มีลิเธียมถูกสูบขึ้นมาประมาณ 34 กิโลกรัม เทียบเท่าลิเธียมคาร์บอเนต (LCE) 180 กิโลกรัม ในการทดสอบการฟื้นตัว 24 ชั่วโมง ระดับน้ำกลับจาก 52.4 เมตร สู่ระดับคงที่ 3.64 เมตร บริษัทระบุชั้นหินอุ้มน้ำที่น่าสนใจระหว่างความลึก 226 ถึง 324 เมตร และกำลังปรับปรุงประมาณการทรัพยากรแร่ โดยจะจัดทำรายงานขอบเขตโครงการต่อไป โครงการยังอยู่ในขั้นสำรวจ และยังไม่มีการประกาศกรอบเวลาการผลิต
2 ชั่วโมงที่แล้ว