China Weekly Inventory Summary and Data Wrap (Dec 3)

เผยแพร่แล้ว: Dec 3, 2021 20:00
This is a roundup of China's metals weekly inventory as of December 3.

SHANGHAI, Dec 3 (SMM) - This is a roundup of China's metals weekly inventory as of December 3.

Aluminium Social Inventories Dropped 15,000 mt on Week

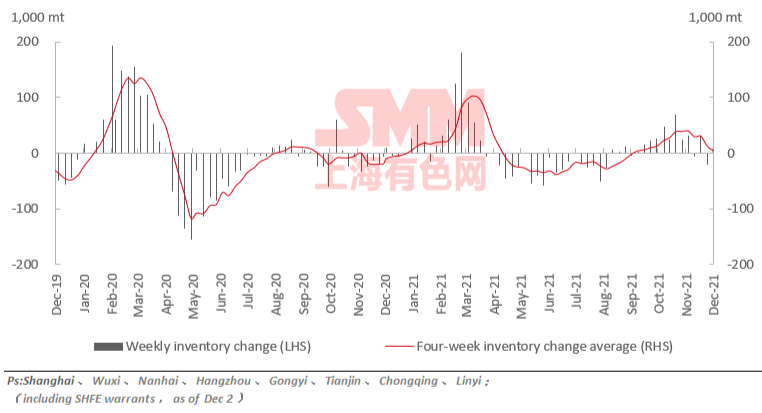
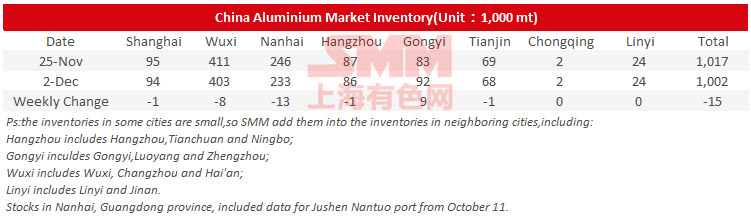
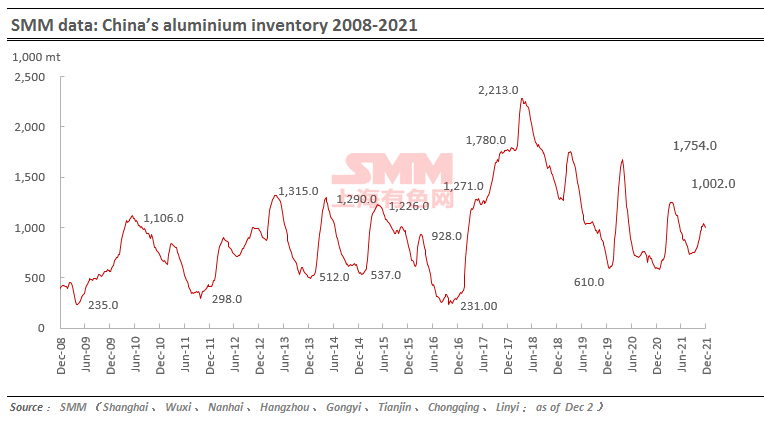
SMM data showed that China's social inventories of aluminium across eight consumption areas dropped 15,000 mt on the week to 1 million mt as of December 2, mainly contributed by Nanhai, Shanghai and Wuxi. The inventory in Gongyi rose on the week.
Aluminium Billet Inventories Down 7,200 mt on Week

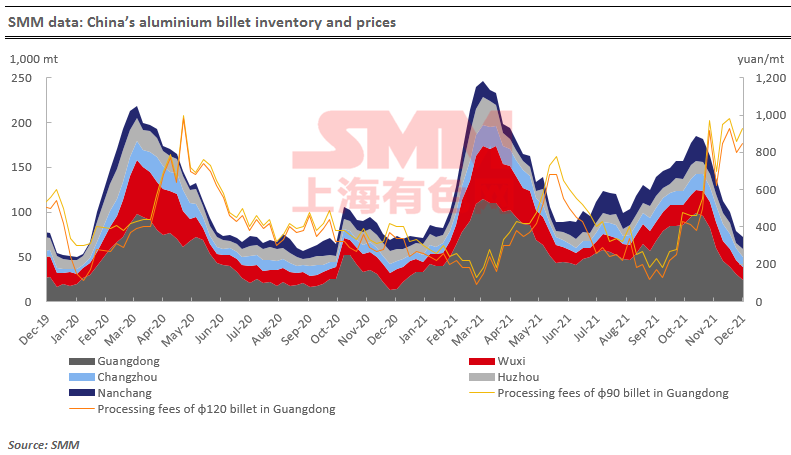
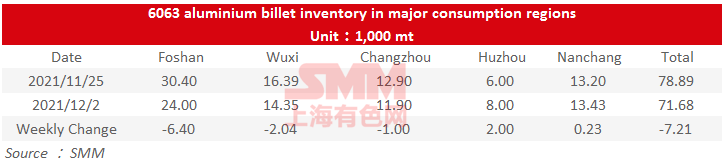
The stocks of aluminium billet in five major consumption areas dropped 7,200 mt to 71,700 mt on December 2 from a week ago, a decrease of 9.14%. And the inventory has been falling for seven straight weeks.

Foshan was still the largest contributor to the falling social inventory, and the local inventory dropped 6,400 mt or 21.05% on the week. The inventories in Wuxi and Changzhou also declined, while Huzhou and Nanchang both saw slightly rising inventories. The declines of weekly social inventory was still caused by the falling arrivals for aluminium billet.

Looking forward, the downstream sectors of aluminium billet became less interest in purchasing, and some of them turned to aluminium ingot as the conversion margin of aluminium billet was high compared with the re-smelting costs. Meanwhile, the warehouses reported that the transportation in north-west China is still disrupted. Hence the social inventory will keep falling but at a much slower pace, and there is also possibility that the inventory would rise on the week.
Copper Inventory in Major Chinese Markets Dipped 6,700 mt on Week

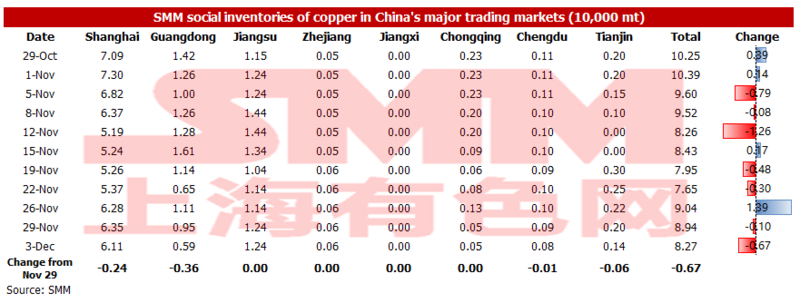
As of Friday December 3, the copper inventory across major Chinese markets fell 6,700 mt from Monday to 82,700 mt. The declines were mainly seen in Shanghai, Guangdong and Tianjin.

Specifically, the inventory in Shanghai decreased by 2,400 mt to 61,100 mt, and the inventory in Guangdong decreased 3,600 mt to 5,900 mt. The inventory in Tianjin declined 600 mt to 1,400 mt. The copper price continued to fall this week. And downstream companies stockpiled actively on adequate cash flows at the start of the month, which were the main reasons for the decline in inventories.

In addition, the invoice issuance issue for imported copper remains as a trouble in December, making it difficult to clear a large volume of imported copper into the domestic market. The smelters that undertook maintenance resume production. The volume of imported copper is unlikely to grow. The total supply is likely to grow slightly. The consumption is expected to remain stable as long as the copper prices do not rise sharply. Therefore, the inventory may increase slightly. And there is room for the spot premiums to drop, but the decline will not be significant.
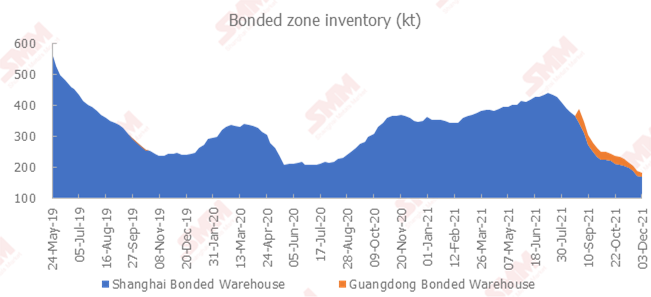
Copper Inventory in China Bonded Area Dipped 5,700 mt

The copper inventories in the domestic bonded zones dipped 5,700 mt from November 26 to 183,500 mt as of Friday December 3, the eighth consecutive week of decline, according to the most recent SMM survey.

The inventory in the Shanghai bonded zone decreased 4,700 mt to 169,600 mt, and the inventory in the Guangdong bonded zone fell 1,000 mt to 13,900 mt. There were inflows of cargoes under warrants which were imported when the SHFE/LME copper price ratio was profitable. The arriving shipments decreased. Meanwhile, it has been difficult for some ships to call at ports due to the strengthening of the customs' quarantine work on inbound ships. And the port work efficiency was low. As such, the bonded zone inventories continued to decline.
Zinc Inventories Down 5,000 mt on the Week

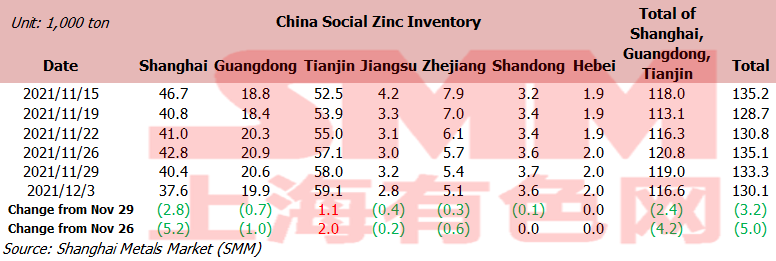
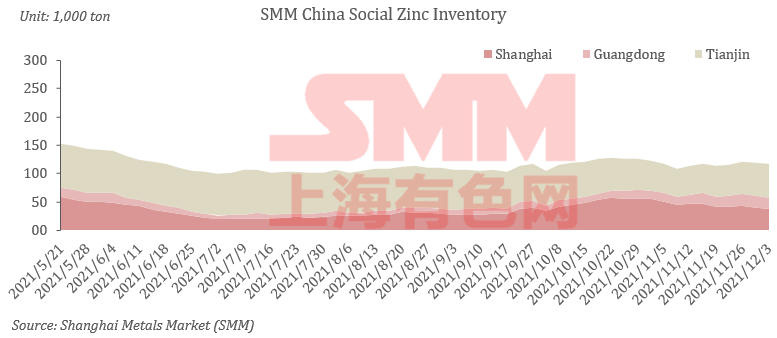
SHANGHAI, Dec 3 (SMM)—Total zinc inventories across seven Chinese markets stood at 130,100 mt as of December 3, down 3,200 mt from November 29 and 5,000 mt from November 26.

The inventory in Shanghai declined as only a small amount of imported zinc arrived and downstream producers began to restock goods after digesting government stockpiles. The stocks in Guangdong declined slightly as the arrivals of goods declined on the week and shipments stabilised. Tianjin saw an increase in the stocks as downstream producers mainly restocked on rigid demand. Inventories in Shanghai, Guangdong and Tianjin fell 4,200 mt, and inventories across seven Chinese markets decreased 5,000 mt.
Lead Ingot Social Inventory Down 6,300 mt on Week

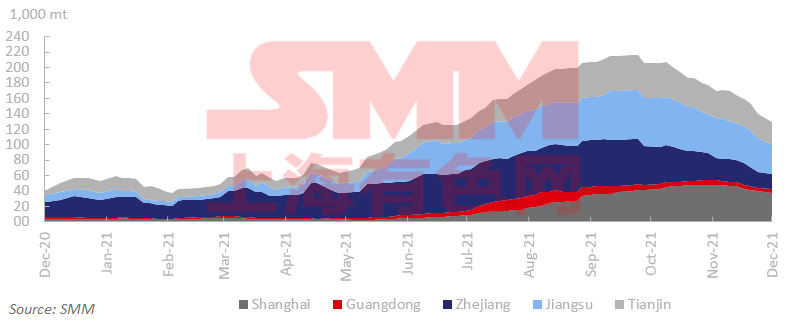
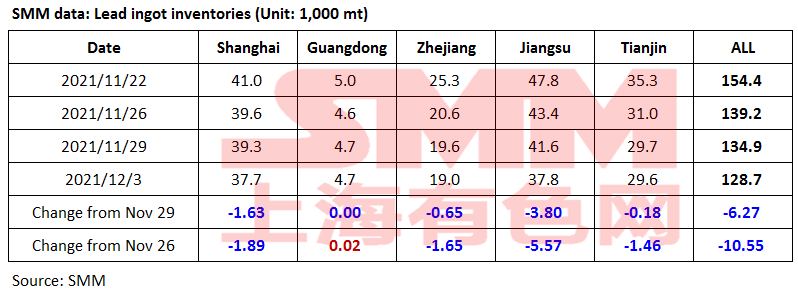
The social inventory of lead ingots across Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin decreased 10,600 mt from November 26 and 6,300 mt from November 29 to 128,700 mt as of December 3.

The secondary lead smelters in Jiangsu and Anhui continued the maintenance, and some smelters in Jianxi reduced the production under the inspections of Solid Waste Management Centre.

The Ministry of Ecology issued a notice on December 1 that the second round of the fifth batch of central environmental protection inspections was fully launched, and four inspection teams will be stations in Heilongjiang, Guizhou, Shaanxi, and Ningxia for one month. Some secondary lead smelters in Guizhou have reduced the production, and the downstream users consumed the social stocks in surrounding areas.

Some primary lead smelters will end maintenance next week, and the output is expected to increase. The lead ingot exports may drop as the export causes losses amid rising SHFE/LME price ratio. The lead ingot social inventory may drop more slowly.
Silicon Metal Social Inventory Increased 3,000 mt on Week

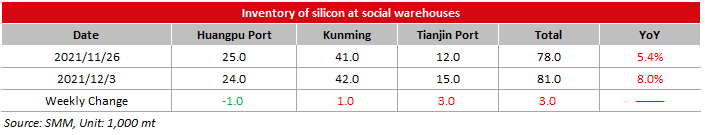
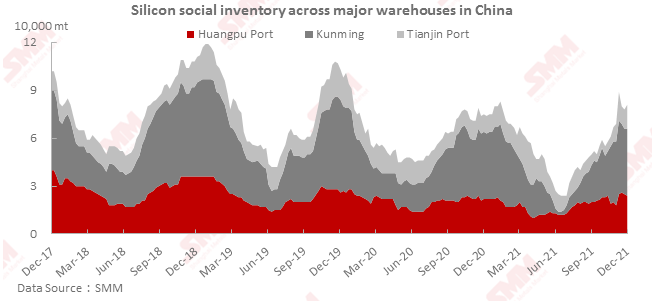
The social inventory of silicon metal across Huangpu port, Kunming city and Tianjin port increased 3,000 mt from the previous week to 81,000 mt as of Friday December 3.

The operating rates across the plants in south and north China remained hight. The silicon metal inventories were transferred from factories to social warehouses. The social inventory increased amid sluggish transactions.
Nickel Ore Inventories at Chinese Ports Fell 169,000 wmt

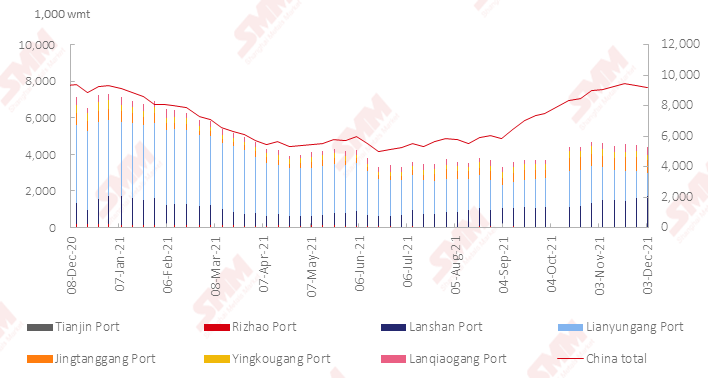
The nickel ore inventory at Chinese ports fell 169,000 wmt to 9.18 million wmt as of December 3. Total Ni content stood at 72,100 mt. The total inventory at seven major ports stood at around 4.39 million wmt, a decline of 129,000 wmt from a week earlier.

Lanshan port saw a severe backlog of cargoes and face great pressure of slow shipments from ports. Jingtang port also met difficulties in shipping cargoes.

The arriving shipments of nickel ore have decreased recently. The nickel ore inventory is expected to slide further in the short term.
SHFE/LME Nickel Price Ratio Rallied

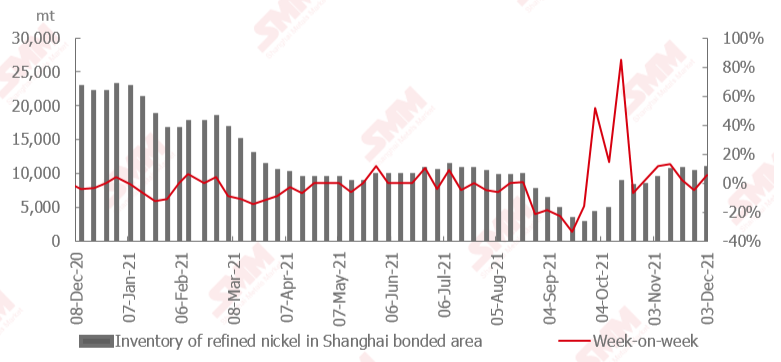
The SHFE/LME nickel price ratio rallied this week after remaining sluggish for several consecutive weeks. SMM believes that the resurgence of the COVID-19 pandemic has triggered overseas concerns over the collapse in the demand.

The domestic demand was stable. Meanwhile, the arriving shipments in China continued to decrease. However, the output of nickel sulphate and stainless steel remained high. The domestic nickel inventory declined this week.

Large volumes of planned shipments arrivals of nickel briquette and nickel plate may impact the domestic supply. This combined with the weak downstream buying interest will increase domestic inventory. As such, the upside room for the SHFE/LME nickel price ratio will be limited.
คำชี้แจงแหล่งที่มาของข้อมูล: นอกจากข้อมูลที่เปิดเผยต่อสาธารณะแล้ว ข้อมูลอื่นๆ ทั้งหมดได้รับการประมวลผลโดย SMM จากข้อมูลสาธารณะ การสื่อสารกับตลาด และการพึ่งพาแบบจำลองฐานข้อมูลภายในของ SMMข้อมูลเหล่านี้มีไว้เพื่ออ้างอิงเท่านั้น ไม่ถือเป็นข้อเสนอแนะในการตัดสินใจ

หากมีข้อสงสัยหรือต้องการทราบข้อมูลเพิ่มเติม กรุณาติดต่อ: lemonzhao@smm.cn
หากต้องการข้อมูลเพิ่มเติมเกี่ยวกับวิธีการเข้าถึงรายงานการวิจัยของเรา โปรดติดต่อ:service.en@smm.cn
ข่าวที่เกี่ยวข้อง
[SMM ข่าวโครเมียม] Transnet มีกำไรครั้งแรกในรอบ 4 ปี ปริมาณขนส่งทางรางเพิ่มขึ้น 4.9% เป็น 167.9 ล้านตัน
5 ชั่วโมงที่แล้ว
[SMM ข่าวโครเมียม] Transnet มีกำไรครั้งแรกในรอบ 4 ปี ปริมาณขนส่งทางรางเพิ่มขึ้น 4.9% เป็น 167.9 ล้านตัน
อ่านเพิ่มเติม
[SMM ข่าวโครเมียม] Transnet มีกำไรครั้งแรกในรอบ 4 ปี ปริมาณขนส่งทางรางเพิ่มขึ้น 4.9% เป็น 167.9 ล้านตัน
[SMM ข่าวโครเมียม] Transnet มีกำไรครั้งแรกในรอบ 4 ปี ปริมาณขนส่งทางรางเพิ่มขึ้น 4.9% เป็น 167.9 ล้านตัน
กลุ่มโลจิสติกส์ขนส่งสินค้าของรัฐแอฟริกาใต้ Transnet รายงานกำไร 4.6 พันล้านแรนด์สำหรับปีการเงินสิ้นสุดวันที่ 31 มีนาคม 2026 ซึ่งเป็นกำไรประจำปีครั้งแรกในรอบสี่ปี พลิกจากขาดทุน 1.9 พันล้านแรนด์ในปีก่อนหน้า รายได้เพิ่มขึ้น 7.1% เป็น 88.6 พันล้านแรนด์ โดยได้แรงหนุนจากปริมาณการขนส่งทางรางและท่อที่สูงขึ้น ประกอบกับการปรับขึ้นอัตราค่าบริการถัวเฉลี่ยถ่วงน้ำหนัก ปริมาณการขนส่งทางรางซึ่งดำเนินการโดยหน่วยธุรกิจที่ใหญ่ที่สุดของ Transnet เพิ่มขึ้น 4.9% เป็น 167.9 ล้านตัน จาก 160.1 ล้านตันในปีก่อนหน้า ขณะที่ปริมาณการขนส่งทางท่อเพิ่มขึ้น 6.9% เป็น 14.3 พันล้านลิตร EBITDA เพิ่มขึ้น 0.7% เป็น 30.9 พันล้านแรนด์ โดยอัตรากำไร EBITDA ลดลง 2.2 จุดเปอร์เซ็นต์เหลือ 34.8% และค่าใช้จ่ายดำเนินงานสุทธิเพิ่มขึ้น 10.8% เป็น 57.7 พันล้านแรนด์ กำไรส่วนใหญ่มาจากธุรกรรมที่เกิดขึ้นครั้งเดียวมากกว่าการดำเนินงาน Transnet ขายหุ้น 49.999% ในท่าเรือ Durban Gateway Terminal ให้แก่ International Container Terminal Services Inc. มูลค่า 10.5 พันล้านแรนด์ มีผลตั้งแต่วันที่ 1 มกราคม 2026 ก่อให้เกิดกำไรจากการขาย 12.5 พันล้านแรนด์ รวมถึงการปรับมูลค่ายุติธรรมที่เกี่ยวข้อง Michelle Phillips ประธานเจ้าหน้าที่บริหารกลุ่มกล่าวว่า บริษัทยังมีหนทางอีกยาวไกลในการฟื้นตัว โดยระบุว่าปริมาณการขนส่งทางรางยังต่ำกว่าเป้าหมาย 180 ล้านตันที่ประกาศไว้ก่อนหน้านี้ ซึ่งเธออธิบายว่าเป็นเงื่อนไขจำเป็นสำหรับธุรกิจหลักที่จะถึงจุดคุ้มทุน เงินกู้ยืมเพิ่มขึ้นเป็น 150.7 พันล้านแรนด์ และการลงทุนรวมอยู่ที่ 23.3 พันล้านแรนด์ในระหว่างปี โดยมีแผนลงทุนเพิ่มอีก 129.1 พันล้านแรนด์ในอีกห้าปีข้างหน้า ผลประกอบการดังกล่าวมีความสำคัญต่อภาคโครมของแอฟริกาใต้ ซึ่งพึ่งพาเครือข่ายรางและท่าเรือของ Transnet ในการขนส่งปริมาณการส่งออกแร่โครมที่ทำสถิติสูงสุดเป็นประวัติการณ์ และข้อจำกัดด้านโลจิสติกส์ทางรางและท่าเรือถูกหน่วยงานอุตสาหกรรมกล่าวถึงซ้ำแล้วซ้ำเล่าว่าเป็นอุปสรรคเชิงโครงสร้างต่อความสามารถในการแข่งขันของอุตสาหกรรมเฟอร์โรอัลลอยด์ บีบให้ต้องพึ่งพาการขนส่งทางถนนที่มีต้นทุนสูงกว่า Transnet ยังรายงานความคืบหน้าในการเปิดเครือข่ายรางให้ผู้ประกอบการรายที่สามเข้าดำเนินการ โดยได้ลงนามข้อตกลงการเข้าถึงรางกับบริษัทเดินรถไฟ 11 ราย และคาดว่าบริการแรกจะเริ่มขึ้นในปีการเงิน 2026/27 ผลประกอบการของ Transnet ไม่ได้เปิดเผยปริมาณเฉพาะของแร่โครมหรือเฟอร์โรอัลลอยด์ในตัวเลขรางหรือท่าเรือ ทำให้ขอบเขตของการปรับปรุงประสิทธิภาพด้านโลจิสติกส์เฉพาะโครมยังไม่สามารถระบุเป็นตัวเลขได้
5 ชั่วโมงที่แล้ว
[SMM โครเมียมแฟลช] เอาต์โตคุมปู ลงนามข้อตกลงสนับสนุนภาคพื้นดินระยะยาวสำหรับเคมิ เหมืองโครเมียมที่ยังดำเนินการอยู่เพียงแห่งเดียวในยุโรป
6 ชั่วโมงที่แล้ว
[SMM โครเมียมแฟลช] เอาต์โตคุมปู ลงนามข้อตกลงสนับสนุนภาคพื้นดินระยะยาวสำหรับเคมิ เหมืองโครเมียมที่ยังดำเนินการอยู่เพียงแห่งเดียวในยุโรป
อ่านเพิ่มเติม
[SMM โครเมียมแฟลช] เอาต์โตคุมปู ลงนามข้อตกลงสนับสนุนภาคพื้นดินระยะยาวสำหรับเคมิ เหมืองโครเมียมที่ยังดำเนินการอยู่เพียงแห่งเดียวในยุโรป
[SMM โครเมียมแฟลช] เอาต์โตคุมปู ลงนามข้อตกลงสนับสนุนภาคพื้นดินระยะยาวสำหรับเคมิ เหมืองโครเมียมที่ยังดำเนินการอยู่เพียงแห่งเดียวในยุโรป
เจนมาร์ ผู้ให้บริการผลิตภัณฑ์โครงสร้างพื้นฐานด้านเหมืองแร่ระดับโลก ได้ลงนามความร่วมมือระยะยาวกับเอาท์โอกุมปุ คอร์ปอเรชัน ผู้ผลิตสเตนเลสสตีล เพื่อจัดหาผลิตภัณฑ์ค้ำยันพื้นดินสำหรับเหมืองเคมิในฟินแลนด์ ซึ่งเป็นเหมืองใต้ดินที่ใหญ่ที่สุดของประเทศและเป็นเหมืองโครเมียมที่ยังดำเนินการอยู่เพียงแห่งเดียวในยุโรป เจนมาร์ได้จัดตั้งบริษัทเจนมาร์ ฟินแลนด์ขึ้นโดยเฉพาะเพื่ออำนวยความสะดวกด้านธุรกรรมเชิงพาณิชย์ให้แก่เอาท์โอกุมปุและทีมผู้บริหารของเหมือง ภายใต้ข้อตกลงระยะเวลาหลายปี เจนมาร์จะจัดหาอุปกรณ์ค้ำยันพื้นดินครบวงจรที่ออกแบบให้เหมาะกับสภาพใต้ดินของเหมืองเคมิ ซึ่งรวมถึงสลักยึดหลังคา สลักเคเบิล ตาข่ายเหล็ก อุปกรณ์เสริมเหล็ก และเรซินแบบสูบได้ บริษัทระบุว่าจะใช้เครือข่ายห่วงโซ่อุปทานระดับโลกและความเชี่ยวชาญด้านเทคนิคเพื่อสนับสนุนความปลอดภัย ความมั่นคง และประสิทธิภาพการผลิตของเหมือง พร้อมทั้งจะทำงานร่วมกับฝ่ายบริหารเหมืองเคมิและทีมเทคนิคใต้ดินในกระบวนการบริหารการเปลี่ยนแปลงอย่างเป็นระบบเพื่อเพิ่มประสิทธิภาพการทำเหมือง ไมค์ เพตโควิช ประธานเจนมาร์ ยุโรป กล่าวถึงเหมืองเคมิว่าเป็นหนึ่งในเหมืองที่ใหญ่และน่าประทับใจที่สุดในยุโรป เหมืองเคมิมีกำลังการแปรรูปแร่ 2.7 ล้านตันต่อปี และเป็นแหล่งป้อนโครเมียมให้แก่การผลิตเฟอร์โรโครมและสเตนเลสสตีลของเอาท์โอกุมปุที่เมืองทอร์นิโอทางตอนเหนือของฟินแลนด์ นับเป็นตัวอย่างที่หาได้ยากของห่วงโซ่คุณค่าโครเมียมแบบครบวงจรตั้งแต่เหมืองจนถึงสเตนเลสที่ดำเนินการภายในยุโรป เอาท์โอกุมปุดำเนินโรงงานผลิตในฟินแลนด์ เยอรมนี สวีเดน เนเธอร์แลนด์ สหรัฐอเมริกา และเม็กซิโก ข้อตกลงนี้ตอกย้ำการลงทุนอย่างต่อเนื่องในความน่าเชื่อถือด้านการดำเนินงานของแหล่งแร่โครเมียมในประเทศเพียงแห่งเดียวของยุโรป ในช่วงเวลาที่ผู้ผลิตเฟอร์โรโครมในภูมิภาคต้องเผชิญการแข่งขันอย่างต่อเนื่องจากวัสดุนำเข้าที่มีต้นทุนต่ำกว่า
6 ชั่วโมงที่แล้ว
[SMM โครเมียมรายวัน] แร่โครเมียมเป็นหนึ่งในสองภาคเหมืองแร่ของแอฟริกาใต้ที่เติบโตในเดือนกรกฎาคม ขณะที่ผลผลิตโดยรวมลดลง 7.5%
6 ชั่วโมงที่แล้ว
[SMM โครเมียมรายวัน] แร่โครเมียมเป็นหนึ่งในสองภาคเหมืองแร่ของแอฟริกาใต้ที่เติบโตในเดือนกรกฎาคม ขณะที่ผลผลิตโดยรวมลดลง 7.5%
อ่านเพิ่มเติม
[SMM โครเมียมรายวัน] แร่โครเมียมเป็นหนึ่งในสองภาคเหมืองแร่ของแอฟริกาใต้ที่เติบโตในเดือนกรกฎาคม ขณะที่ผลผลิตโดยรวมลดลง 7.5%
[SMM โครเมียมรายวัน] แร่โครเมียมเป็นหนึ่งในสองภาคเหมืองแร่ของแอฟริกาใต้ที่เติบโตในเดือนกรกฎาคม ขณะที่ผลผลิตโดยรวมลดลง 7.5%
ผลผลิตเหมืองแร่ของแอฟริกาใต้ลดลง 7.5% เมื่อเทียบรายปีในเดือนกรกฎาคม 2026 โดยภาคเหมืองแร่ 10 ใน 12 สาขาของประเทศบันทึกการลดลง ตามรายงานล่าสุดด้านการผลิตและการจำหน่ายเหมืองแร่ของสำนักงานสถิติแอฟริกาใต้ แร่โครเมียมเป็นหนึ่งในสองสาขาเดียวที่เติบโต เพิ่มขึ้น 13.7% เมื่อเทียบรายปี ควบคู่กับแร่แมงกานีสที่ 4.9% โลหะกลุ่มแพลทินัมเป็นปัจจัยลบที่ใหญ่ที่สุด โดยผลผลิตลดลง 13.5% และฉุดตัวเลขรวมลง 3.2 จุดเปอร์เซ็นต์ ผลผลิตถ่านหินลดลง 7.5% มีส่วนฉุด 2 จุดเปอร์เซ็นต์ ขณะที่แร่เหล็กลดลง 8.1% คิดเป็น -1.3 จุดเปอร์เซ็นต์ เพชรบันทึกการลดลงรุนแรงที่สุดที่ 48.2% โดยนิกเกิลลดลง 18.8% ควบคู่กับผลผลิตทองคำและทองแดงที่อ่อนตัวลง เมื่อปรับฤดูกาลแล้ว ผลผลิตเหมืองแร่ลดลง 1.9% เมื่อเทียบรายเดือนในเดือนกรกฎาคม หลังเพิ่มขึ้นเล็กน้อย 0.1% ในเดือนมิถุนายน และลดลง 5.6% ในเดือนพฤษภาคม แร่โครเมียมยังโดดเด่นในด้านยอดจำหน่าย ยอดจำหน่ายแร่ ณ ราคาปัจจุบันลดลง 5.6% เมื่อเทียบรายปีในเดือนกรกฎาคม โดยทองคำเป็นปัจจัยลบที่ใหญ่ที่สุด เนื่องจากยอดจำหน่ายลดลง 33.4% ฉุดลง 8.5 จุดเปอร์เซ็นต์ ยอดจำหน่ายแร่อโลหะอื่นลดลง 26% และยอดจำหน่ายนิกเกิลลดลง 51.7% ในทางตรงกันข้าม ยอดจำหน่ายแร่โครเมียมเพิ่มขึ้น 20% มีส่วนสนับสนุน 1.6 จุดเปอร์เซ็นต์ และเป็นปัจจัยบวกที่ใหญ่ที่สุด โดยยอดจำหน่ายถ่านหินเพิ่มขึ้น 5% คิดเป็นอีก 1 จุดเปอร์เซ็นต์ ยอดจำหน่ายแร่ ณ ราคาปัจจุบันที่ปรับฤดูกาลแล้วลดลง 15.1% เมื่อเทียบรายเดือนในเดือนกรกฎาคม หลังเพิ่มขึ้น 2% ในเดือนมิถุนายน ฌอง-ปิแอร์ เทอร์บลานช์ นักสถิติสำรวจอาวุโสของ Stats SA ระบุว่าเดือนดังกล่าวเป็นการลดลงรายปีอย่างมีนัยสำคัญสำหรับภาคเหมืองแร่โดยรวม โดยแร่โครเมียมและแมงกานีสเป็นข้อยกเว้นท่ามกลางการหดตัวในวงกว้าง
6 ชั่วโมงที่แล้ว
ข่าวที่เกี่ยวข้อง