Impact from high copper prices and secondary copper slowed recovery in copper rods produced with copper cathode

เผยแพร่แล้ว: Mar 23, 2021 10:27 (GMT+8)
Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues.

SHANGHAI, Mar 23 (SMM)—Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues. Cash flow issues are expected to intensify due to high tax payment in April. As such, factories and suppliers should liquidate stocks.
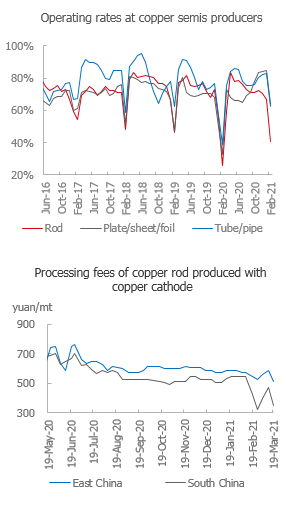
Operating rates at copper rod producers using secondary copper as raw material should return to a high level in March against accumulated orders, boosting secondary copper demand. However, decreased new orders at the end of last week and increased cash flow issues have limited the interest in purchasing. That combined with the demand for stock liquidation at suppliers, will keep normal supply and demand.

The average weekly price of #1 bare bright copper without invoice stood at 59,930 yuan/mt, an increase of 200 yuan/mt compared with the previous week, and the weekly average price difference between copper cathode and copper scrap stood at 2,217 yuan/mt, an increase of 385 yuan/mt. The average weekly discount of copper rod produced with secondary copper stood at 1,464 yuan/mt against the SHFE front-month copper contract, growing the advantage compared to copper rod produced with copper cathode.

For imported copper scrap, cif quotes for #1 copper scrap were Comex July copper less $0.21/lb, and offers for birch/cliff were Comex July copper less $0.36/lb. US brass was quoted at $5,650-5,850/mt. The coefficient for copper granules (98%) against LME copper stood at 93%, and the coefficient for bare bright copper against LME copper at 96-96.5%, on a cif basis.

Improved consumption of copper rod produced with secondary copper had significant impact on consumption of copper rod produced with copper cathode

Many producers of copper rod using secondary copper as feedstock have seen high orders, reporting strong supply and demand. The price spread between copper cathode and copper scrap has returned to above 2,000 yuan/mt, and discounts of copper rod produced with secondary copper reached a high of 1,550 yuan/mt against the SHFE front-month copper contract. Low-priced copper rods produced with secondary copper have been more desirable for downstream companies amid high copper prices, and this depressed consumption of copper rod produced with copper cathode which has been already weak. 

The impact of poor wire and cable demand and secondary copper rods has slowed recovery in the market of copper rod produced with copper cathode. Most of the producers are unlikely to return to normal production levels in March. As consumption picks up amid warmer weather, the market sentiment of the wire and cable industry should rise. Consumption of copper rods produced with copper cathode is expected to improve in April. However, the overly high copper price will depressed consumption. The current inventory of finished products at copper rod producers using copper cathode as feedstock stands at high levels. Producers will prioritise stock depletion and new orders at end users are unlikely to pass to copper rod plants using copper cathode as raw material any time soon. We believe that consumption of copper rods produced with copper cathode in April would hardly return to the peak season level of previous years.
คำชี้แจงแหล่งที่มาของข้อมูล: นอกจากข้อมูลที่เปิดเผยต่อสาธารณะแล้ว ข้อมูลอื่นๆ ทั้งหมดได้รับการประมวลผลโดย SMM จากข้อมูลสาธารณะ การสื่อสารกับตลาด และการพึ่งพาแบบจำลองฐานข้อมูลภายในของ SMMข้อมูลเหล่านี้มีไว้เพื่ออ้างอิงเท่านั้น ไม่ถือเป็นข้อเสนอแนะในการตัดสินใจ

หากมีข้อสงสัยหรือต้องการทราบข้อมูลเพิ่มเติม กรุณาติดต่อ: lemonzhao@smm.cn
หากต้องการข้อมูลเพิ่มเติมเกี่ยวกับวิธีการเข้าถึงรายงานการวิจัยของเรา โปรดติดต่อ:service.en@smm.cn
ข่าวที่เกี่ยวข้อง
Emerita's Iberian Belt West Project PFS แสดงมูลค่าปัจจุบันสุทธิ 776 ล้านดอลลาร์ อายุเหมือง 21 ปี
30 Oct 2026 22:39 (GMT+8)
Emerita's Iberian Belt West Project PFS แสดงมูลค่าปัจจุบันสุทธิ 776 ล้านดอลลาร์ อายุเหมือง 21 ปี
อ่านเพิ่มเติม
Emerita's Iberian Belt West Project PFS แสดงมูลค่าปัจจุบันสุทธิ 776 ล้านดอลลาร์ อายุเหมือง 21 ปี
Emerita เปิดเผยผลการศึกษาเบื้องต้นสำหรับโครงการสังกะสี-ตะกั่ว-ทองแดง Iberian Belt West: มูลค่าปัจจุบันสุทธิ 776 ล้านดอลลาร์สหรัฐ อายุเหมือง 21 ปี Emerita Resources (TSXV: EMO) เปิดเผยเมื่อวันที่ 29 ตุลาคมถึงผลการศึกษาเบื้องต้นเชิงบวกสำหรับโครงการพหุโลหะ Iberian Belt West (IBW) ซึ่งบริษัทถือหุ้น 100% ในแถบไพไรต์ไอบีเรียของสเปน ผลการศึกษาแสดงมูลค่าปัจจุบันสุทธิหลังหักภาษี 776 ล้านดอลลาร์สหรัฐที่อัตราคิดลด 8% อัตราผลตอบแทนภายใน 23.51% อายุเหมือง 21 ปี และระยะเวลาคืนทุนหลังหักภาษี 1.9 ปี เงินลงทุนเริ่มต้น 567 ล้านดอลลาร์สหรัฐรวมค่าเผื่อความไม่แน่นอน ปริมาณสำรองน่าจะเป็นเริ่มต้นรวม 23.4 ล้านตัน เกรดสังกะสี 2.30% ตะกั่ว 1.13% ทองแดง 0.45% เงิน 53 กรัมต่อตัน และทองคำ 1.07 กรัมต่อตัน
30 Oct 2026 22:39 (GMT+8)
ตลาดทองแดงเผชิญแรงกดดันจากการเปลี่ยนแปลงภาษีและอุปทานขาดแคลนในเดือนตุลาคม 2026
30 Oct 2026 19:47 (GMT+8)
ตลาดทองแดงเผชิญแรงกดดันจากการเปลี่ยนแปลงภาษีและอุปทานขาดแคลนในเดือนตุลาคม 2026
อ่านเพิ่มเติม
ตลาดทองแดงเผชิญแรงกดดันจากการเปลี่ยนแปลงภาษีและอุปทานขาดแคลนในเดือนตุลาคม 2026
ในเดือนตุลาคม 2026 ส่วนต่างราคารวมภาษีระหว่างโลหะปฐมภูมิกับเศษโลหะปรับตัวแคบลงจาก 3,979 หยวน/ตัน ณ ต้นสัปดาห์ เหลือ 1,896 หยวน/ตัน จากนั้นฟื้นตัวกลับสู่ช่วง 2,826-2,976 หยวน/ตัน ส่วนต่างราคาระหว่างแท่งทองแดงแคโทดกับแท่งทองแดงทุติยภูมิก็บีบตัวลงจาก 1,250 หยวน/ตัน สู่ระดับต่ำสุดต่ำกว่า 430 หยวน/ตัน ก่อนดีดกลับขึ้นไปที่ 1,450 หยวน/ตัน แม้ข้อได้เปรียบด้านการทดแทนตามบัญชีจะผันผวน แต่ส่วนใหญ่ถูกบั่นทอนด้วยปัจจัยด้านต้นทุนเกือบตลอดช่วงเวลา
30 Oct 2026 19:47 (GMT+8)
【แฟลช | โมลิบดีนัมออกไซด์ปูซานดีดตัวขึ้น หลังกิจกรรมการซื้อพุ่งทะลัก】
30 Oct 2026 18:09 (GMT+8)
【แฟลช | โมลิบดีนัมออกไซด์ปูซานดีดตัวขึ้น หลังกิจกรรมการซื้อพุ่งทะลัก】
อ่านเพิ่มเติม
【แฟลช | โมลิบดีนัมออกไซด์ปูซานดีดตัวขึ้น หลังกิจกรรมการซื้อพุ่งทะลัก】
SMM สำรวจตลาดพบว่า โมลิบดีนัมออกไซด์ที่ปูซานดีดตัวขึ้นอย่างรวดเร็วจากจุดต่ำสุดเมื่อวันที่ 28 ตุลาคมที่ 32.30 ดอลลาร์สหรัฐ/ปอนด์โม โดยมีการซื้อขายจริงต่อเนื่องที่ 33.10–33.30 ดอลลาร์สหรัฐ/ปอนด์โม มีการยืนยันการซื้อขายหนึ่งตู้คอนเทนเนอร์ที่ 33.30 ดอลลาร์สหรัฐ/ปอนด์โม กิจกรรมการซื้อที่ปูซานเพิ่มขึ้นอย่างมีนัยสำคัญ และ SMM ประเมินเบื้องต้นว่าปริมาณการซื้อขายวันนี้อยู่ที่เจ็ดถึงแปดตู้คอนเทนเนอร์แล้ว โดยยังมีดีลเพิ่มเติมเกิดขึ้นอีก SMM จะอัปเดตปริมาณรวมและระดับราคาล่าสุดต่อไป
30 Oct 2026 18:09 (GMT+8)